

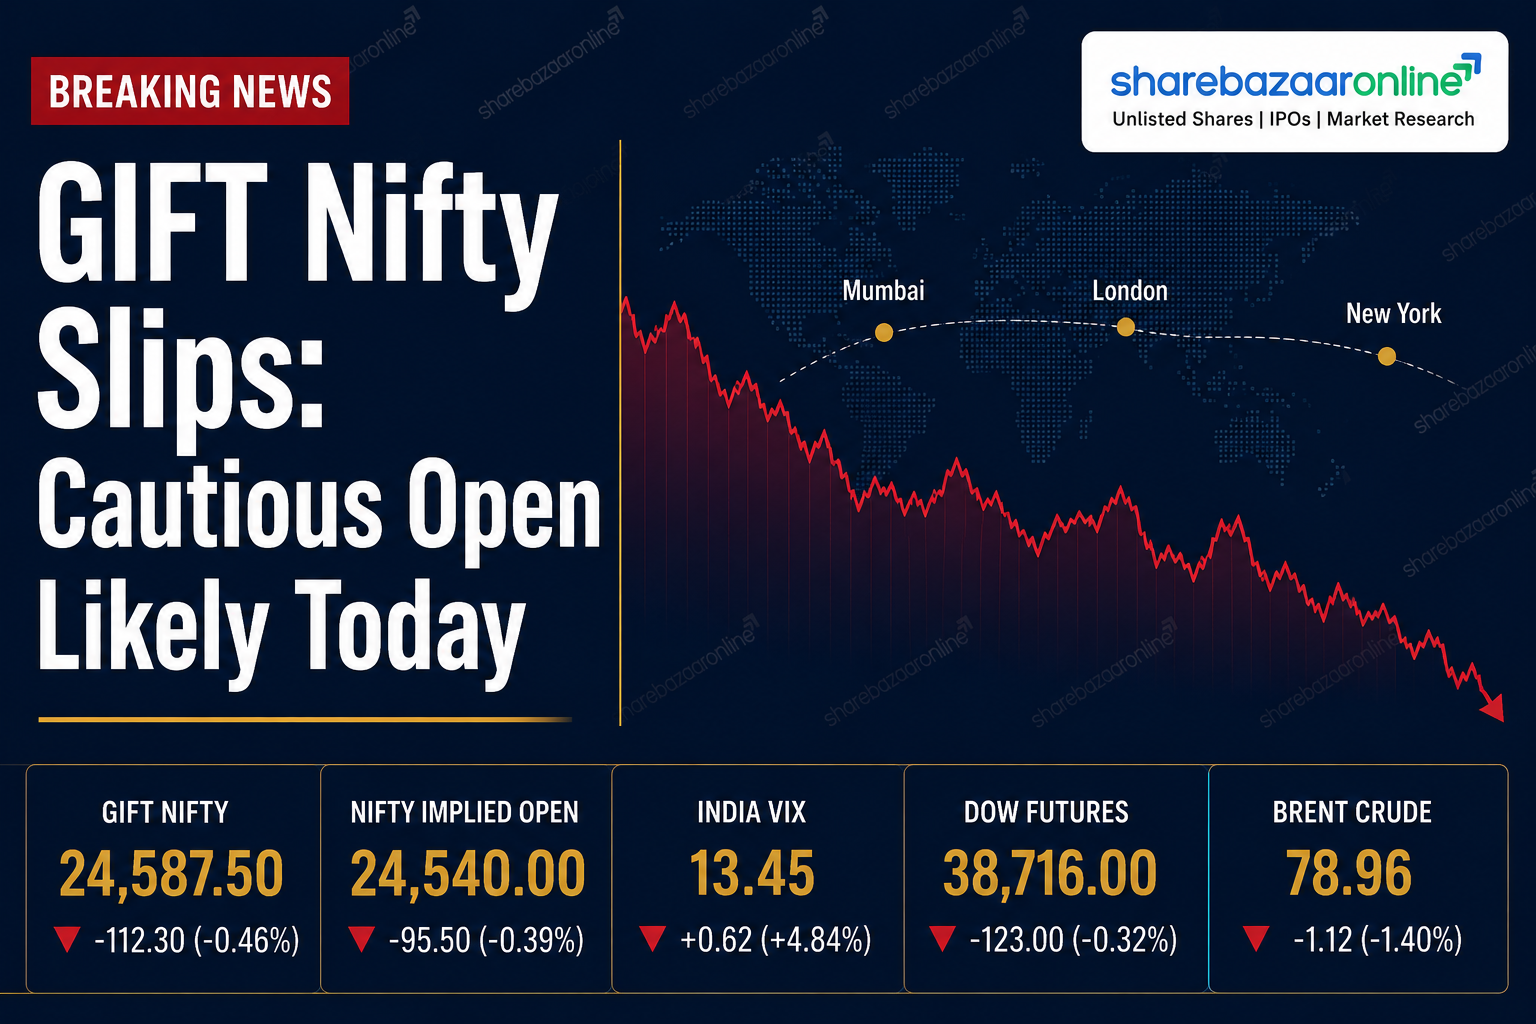
Dalal Street walks into Wednesday's session with its guard partly up. GIFT Nifty futures were trading slightly in the red heading into the bell, a signal that traders are reading as a request for patience rather than a verdict on direction. The setup is familiar by now: foreign institutional investors keep trimming positions, domestic institutions keep buying the dip, and global markets keep doing just enough to stop the mood from turning sour. Wall Street closed firm overnight, European benchmarks held their ground, and India's own fear gauge sits at levels that suggest nobody is bracing for fireworks. What's missing is a fresh catalyst, and that absence is itself the story.
Why This Matters
Markets rarely move on data alone; they move on what the data implies about what comes next. A flat-to-cautious opening cue from GIFT Nifty, layered on top of persistent FII selling, tells a different story depending on which side of the trade you're on. For long-term investors, it's a reminder that domestic liquidity — the DII bid that has shown up day after day through mid-June — has effectively become the market's shock absorber. For traders, a quiet GIFT Nifty print often precedes a session that takes its real direction from the first hour, not the opening bell. And for anyone watching specific names like Groww or Prime Focus, today's broader tape matters less than the company-specific developments sitting underneath it.
Key Highlights
- GIFT Nifty futures indicated a slightly negative bias ahead of Wednesday's session, pointing to a range-bound start.
- Wall Street closed firm: the Dow Jones rose 0.96% to 51,713.11, the Nasdaq jumped 3.06% to 26,706.80, and the S&P 500 added 1.66% to close at 7,576.26.
- European indices were broadly positive — the FTSE 100 (+0.54%), DAX (+0.48%), CAC 40 (+0.66%), and STOXX 50 (+0.73%) all closed higher.
- India VIX, the market's volatility gauge, stood at 13.8375, up a modest 0.53%, suggesting traders aren't pricing in a turbulent session.
- FIIs were marginal net buyers on June 15 at ₹200 crore, a sharp moderation from the heavier selling seen across early June, while DIIs continued their now-familiar buying streak with a net purchase of ₹3,189.30 crore the same day.
- Prime Focus, the largest listed Media & Entertainment company by market capitalisation at roughly ₹18,639 crore, saw its MarketsMojo rating upgraded from Sell to Hold on June 15, with a Mojo Score of 50.0.
- Groww parent Billionbrains Garage Ventures was trading around ₹204–205 as of June 15, with a market capitalisation near ₹1.25 lakh crore and a price-to-earnings ratio above 75.
Detailed Analysis
The overnight tape from the US tells a cleaner story than the one Indian markets are likely to open with. A near-1% gain on the Dow and a sharp 3% pop on the Nasdaq isn't a quiet session — it's the kind of close that usually pulls Asian and emerging markets higher in sympathy. Yet GIFT Nifty isn't reflecting that enthusiasm, and that gap between global cheer and local caution is worth sitting with for a moment.
Part of the explanation lies in the tug-of-war between foreign and domestic flows that's defined Indian equities for weeks now. FIIs have been net sellers on most sessions through early-to-mid June, with outflows running into thousands of crores on several days — June 5 alone saw FIIs pull out ₹8,776.20 crore. What's kept the index from cracking under that pressure is the DII side of the ledger, which has been buying with almost mechanical consistency: ₹9,133.60 crore on June 5, ₹9,589.30 crore on June 2, and ₹3,189.30 crore as recently as June 15. That's not a coincidence; it's domestic mutual funds and insurers deploying SIP inflows and fresh allocations regardless of what foreign desks are doing, and it has functioned as a structural floor under the market for months.
The India VIX print adds a second layer to this. At 13.84, volatility expectations remain contained — nowhere near the levels that typically accompany genuine risk-off sentiment. A market that's nervous about an imminent shock usually shows it in the VIX first. This one isn't.
Market Impact
A cautious GIFT Nifty open against a backdrop of firm global cues usually resolves in one of two ways: either the early hesitation gets overridden once domestic buyers step in (which has been the pattern lately, given the DII trend), or the session stays rangebound until a fresh trigger — an earnings surprise, a policy headline, a global data print — gives it direction. Banking and IT names, which tend to be the most sensitive to global risk sentiment, are the ones worth watching first; a soft GIFT Nifty open with strong Nasdaq overnight often produces an early dip in financials followed by a recovery as the session progresses, assuming DII buying shows up on schedule.
Sector Impact
Cyclical and banking names stand to benefit most directly from firm US and European closes, since global risk appetite tends to flow first into rate-sensitive sectors. IT could see a mixed reaction — a strong Nasdaq is constructive for sentiment around the sector's US-exposed revenue base, but the rupee's trajectory and any commentary on US tech capex will matter just as much as the headline index move. Media and entertainment, a smaller and more idiosyncratic pocket of the market, has its own story playing out independent of the broader tape: Prime Focus's rating upgrade and its dominant 42.52% share of sector market capitalisation make it the one to track within that space, though the stock's ongoing NCLAT insolvency-related litigation (next hearing scheduled for July 9) remains an overhang that technical upgrades alone don't resolve.
Opportunities
Investors with a longer horizon may find the current setup — persistent FII selling met by equally persistent DII buying — to be a useful entry window rather than a warning sign, provided the broader macro backdrop (rate trajectory, crude prices, currency stability) doesn't deteriorate. The contained VIX print suggests the market isn't demanding a large risk premium right now, which historically has been a more constructive entry condition than buying into elevated volatility. For sector-specific opportunities, Prime Focus's rating upgrade is worth monitoring, though it should be weighed against the unresolved legal overhang rather than treated as a standalone buy signal.
Risks
The most obvious risk is that FII selling resumes at scale and DII buying simply can't keep pace indefinitely — domestic flows are strong but not infinite, and a sustained foreign exodus has historically been able to overwhelm local support during stress periods. A second risk sits specifically with Prime Focus: the NCLAT stay on the insolvency proceedings is interim, not final, and the next hearing on July 9 could reintroduce uncertainty regardless of where the stock's technical rating sits today. For Groww, a price-to-earnings ratio north of 75 leaves limited room for disappointment; any moderation in growth from new segments like commodity trading or wealth management could trigger a re-rating.
Future Outlook
3-Month Outlook
Expect continued tug-of-war between FII and DII flows to remain the dominant theme, with index direction likely to stay sensitive to US Federal Reserve commentary and crude oil price stability. A contained VIX argues against sharp near-term drawdowns, but range-bound trading is the more probable base case absent a fresh catalyst.
6-Month Outlook
The resolution of Prime Focus's NCLAT matter, expected around or after the July 9 hearing, could meaningfully reprice the stock in either direction. Broader market direction over this horizon will likely hinge on whether DII inflows — largely SIP-driven — hold steady through any global volatility spike.
12-Month Outlook
On a one-year view, the structural story remains domestic flows versus foreign flows, with India's relative growth profile versus other emerging markets likely to determine whether FII selling reverses into renewed buying. Newly listed fintech names like Groww will face their first full-cycle test of whether premium valuations can be sustained as growth normalizes from IPO-era highs.
Expert Observation
The persistence of DII buying through a stretch of FII selling is the kind of detail that tends to get lost in day-to-day headlines but matters enormously for how resilient the market actually is under the surface. It's also worth noting that a contained VIX alongside cautious index futures isn't a contradiction — it simply means the market expects a quiet, technical session rather than a directional one.
Investor Takeaway
Today's setup rewards patience over conviction. The signals — a cautious GIFT Nifty, firm global markets, contained volatility, and a familiar FII-DII flow pattern — don't point toward a sharp move in either direction. Investors holding core positions have little reason to react to the opening cues alone. Those looking at specific names should separate company-level catalysts, like Prime Focus's rating upgrade or Groww's growth trajectory, from the broader index narrative, since the two aren't necessarily moving in sync right now.
Conclusion
Wednesday's session looks set to open with more hesitation than conviction, shaped by a soft GIFT Nifty print, steady global cues, and a market structure where domestic buying continues to offset foreign selling. None of the individual data points scream urgency, and that's arguably the point: this is a market waiting for its next real trigger rather than reacting to the one it just had.
Stay ahead of every session with ShareBazaarOnline's live market coverage, sector breakdowns, and investor-first analysis — bookmark us before the bell rings tomorrow.