

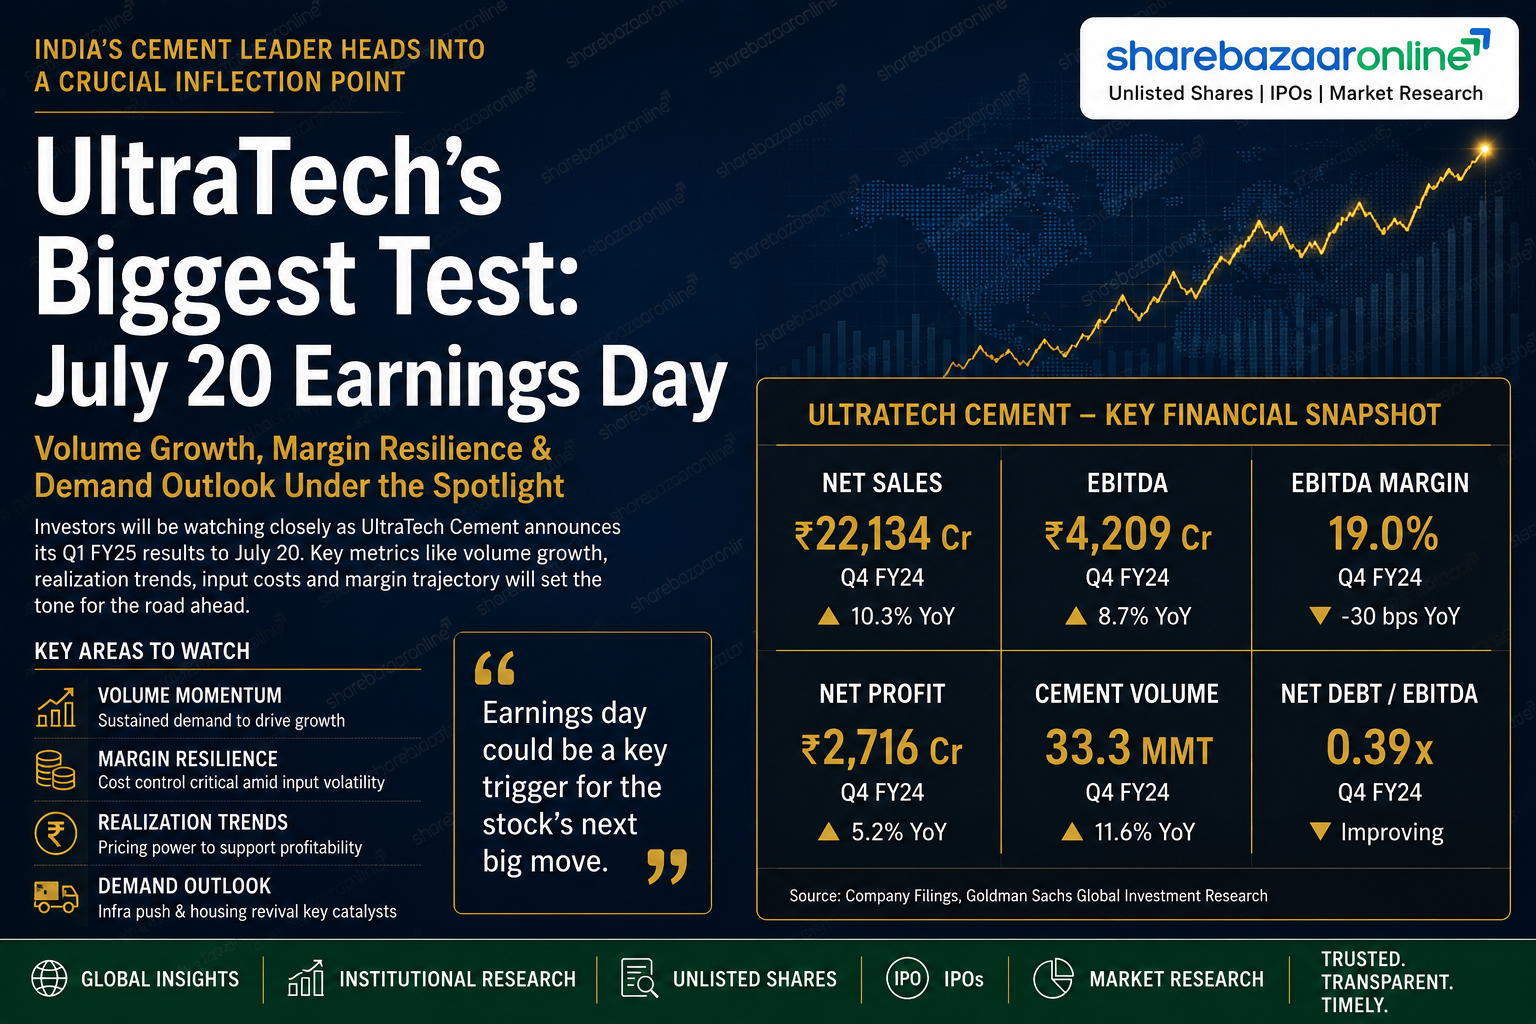
UltraTech Cement Q1 FY27 Results on July 20: What India's Largest Cement Maker Needs to Prove This Quarter
Earnings Date Confirmed | Dividend Watch | Share Price Near Key Support | FY27 Demand Guidance in Focus
India's largest cement company by installed capacity has a date with investors: July 20, 2026. UltraTech Cement's board has set July 20, 2026 as the meeting date to approve its Q1 FY27 financial results — the first quarterly earnings print of a fiscal year that carries considerable weight after a landmark FY26 performance. Ad Hoc News
The timing is significant. The April–June quarter is structurally the most challenging period for India's cement industry. Monsoon rains slow construction activity across large swathes of the country, suppressing volumes and putting pressure on realizations. Every earnings call in Q1 is as much about what management says about Q2 and Q3 as it is about the numbers themselves.
For UltraTech, the stakes are higher than usual.
Coming Off a Historic Year — and Investors Know It
FY26 was not just a good year for UltraTech. It was a year the company had been building toward for the better part of a decade.
Consolidated net sales for FY26 reached ₹87,384 crore, a 17% increase over the previous fiscal. Profit after tax (before exceptional items) rose 36% to ₹8,305 crore — the first time UltraTech's consolidated net profit has crossed the ₹8,000 crore threshold. InvestyWise
The company's domestic grey cement capacity also surpassed the 200 MTPA milestone during the year, and operating cash flows grew 50% year-on-year to ₹14,398 crore — the strongest in the company's history. UltraTech Cement
To cap that FY26 journey, the board did something it has never done before: UltraTech recommended a ₹240 per share special dividend — described as a 2400% payout on a face value of ₹10 each — subject to shareholder approval at the upcoming AGM. Upstox
That kind of year creates its own pressure. Investors who bought into the FY26 story are now asking whether FY27 can sustain even a fraction of that trajectory.
Q4 FY26: The Launchpad
Before dissecting what Q1 FY27 might look like, it helps to understand where UltraTech is starting from.
The company's Q4 FY26 net profit rose 21% year-on-year to ₹3,000 crore, while revenue from operations climbed nearly 12% to ₹25,799 crore. Earnings per share improved to ₹101.41 from ₹84.38 in the same quarter a year earlier. Upstox
The Q4 operating PBIDT hit an all-time quarterly high of ₹5,688 crore — up 20% year-on-year — with operating margins expanding 200 basis points and PBIDT per tonne rising 11% to ₹1,253. InvestyWise
Grey cement sales volumes in India reached 42.41 million tonnes in Q4, growing 9.3% year-on-year, with capacity utilisation surging to 89% — propelled by demand from housing, infrastructure, and commercial construction. UltraTech Cement
On costs, the picture was equally reassuring. Energy costs declined 3% year-on-year, powered by a higher green power mix — which stood at 43% of total consumption versus 34.4% a year earlier. UltraTech Cement
The Q1 FY27 Equation: Volume vs. Monsoon
History provides context here. When UltraTech reported Q1 FY26 results — covering the April–June 2025 quarter — the numbers were strong but the backdrop was unusually supportive.
In Q1 FY26, UltraTech posted a 48.9% year-on-year jump in net profit to ₹2,226 crore, on total income of ₹21,455.68 crore — up 13% from the same period a year earlier. Consolidated volume growth ran at 9.7% year-on-year, aided by the recently absorbed India Cements business. business-standard
EBITDA per tonne stood at ₹1,248 per million tonnes in Q1 FY26, up ₹337 per MT year-on-year, while energy costs fell 12% as fuel prices eased. business-standard
That's the base Q1 FY27 must now beat — or at minimum, hold respectably against.
Street estimates have not been published in uniform consensus form yet, but the directional view among analysts is cautious. The monsoon arrived ahead of schedule in several key demand geographies in 2026, and cement despatches industry-wide slowed through May. Whether June bounced back fast enough to rescue the quarter's volume tally is the central question.
What the Earnings Call Will Really Be About
Numbers will tell part of the story on July 20. Management commentary will tell the rest.
Three things will dominate the Q1 FY27 earnings call:
Realizations. Cement prices in India have been under pressure. Competitive dynamics with Adani-affiliated brands (Ambuja and ACC) have introduced pricing discipline questions across markets. Whether UltraTech held per-bag realizations close to Q4 FY26 levels — or saw sequential softness — will shape near-term margin forecasts.
Energy cost tailwind. One of the defining stories of FY26 was the company's push toward green power. At 43% green power mix, every percentage point increase structurally reduces fuel cost exposure. If that ratio continued climbing into Q1 FY27, it could partially offset any volume weakness.
Demand guidance for H2 FY27. The government's infrastructure spending cycle — roads, railways, metro projects, affordable housing — remains the long-cycle cement demand story. Management's read on how that pipeline translates into H2 volumes will matter enormously for the stock.
Share Price: At an Interesting Level
As of early June 2026, UltraTech was trading at a trailing price-to-earnings ratio of approximately 41.1, versus an industry multiple closer to 34.7 — a meaningful premium to domestic cement peers. Ad Hoc News
The stock's 52-week range runs from ₹10,325 to ₹13,110, with the market capitalisation standing around ₹3.38 lakh crore. INDmoney
The three-month share performance turned weaker, with the stock moving below major moving averages ahead of the results — a pattern that often sets up asymmetric post-result moves. A beat on EBITDA per tonne tends to compress that premium concern rapidly; a miss on volumes could send the stock back toward the lower end of its range. Ad Hoc News
Dividend Watch
The next dividend payment for UltraTech shareholders carries an expected ex-date of July 27, 2026 and a payment date of August 21, 2026 — both closely tied to the results cycle. Stock Events
The ₹240/share special dividend from FY26 is subject to AGM approval. Income-oriented shareholders will be tracking both the AGM confirmation date and whether the board signals any interim dividend consideration alongside Q1 FY27 results.
Market Impact
UltraTech's earnings do not occur in a vacuum. As the capacity leader with over 200 MTPA domestically, its results function as a de facto sector health check. A volume beat lifts the entire cement sector — Shree Cement, Dalmia Bharat, JK Cement, and smaller regional players all trade in UltraTech's wake on results day.
The Q1 print will also inform the inflation narrative. Cement is a key construction input; if UltraTech's management suggests price increases are coming in Q2 or Q3, real estate and infrastructure stocks could see a sympathetic re-rating — or a cost-concern selloff depending on the magnitude.
Sector Impact
India's cement sector is in the middle of its largest capacity-addition cycle in recent history. The industry added significant capacity in FY24–FY26, creating a structural overcapacity situation in certain regions — particularly North and Central India. The outcome of Q1 FY27 will provide the first real read on whether absorption of that new supply has begun, or whether pricing remains challenged heading into the peak construction season of Q3. Univest
Opportunities
- Green power cost advantage compounds with each quarter. At 43%+ renewable mix, UltraTech's structural cost edge over peers widens.
- Infrastructure demand pipeline: PM Gati Shakti and National Infrastructure Pipeline projects continue to push cement offtake.
- Integration of India Cements capacity — which boosted Q1 FY26 volumes — enters its second full year, with operational synergies still being realized.
- Potential for further debt reduction, given the ₹14,398 crore operating cash flow achievement in FY26.
Risks
- Monsoon-induced volume pressure is the obvious near-term headwind.
- Cement pricing wars with Adani group entities in key states remain a margin risk.
- Coal and petcoke price volatility could reverse the energy cost tailwind.
- High PE premium (41.1x vs sector 34.7x) leaves limited room for earnings disappointment without meaningful share price correction.
Future Outlook
3-Month Outlook (July–September 2026): Q1 results set the tone. Post-monsoon demand recovery in September typically signals the start of the strong construction season. Watch management's monsoon progress commentary closely.
6-Month Outlook (July–December 2026): Q2 FY27 is seasonally the weakest volume quarter due to peak monsoon. However, Q3 — covering October to December — is historically strong. If the government's infrastructure budget execution accelerates in H2, volume growth of 8–12% year-on-year is achievable.
12-Month Outlook (FY27 Full Year): With 200+ MTPA capacity fully operational and green energy costs structurally lower, UltraTech is positioned to build on FY26's ₹8,305 crore PAT base. Street consensus, where available, points toward continued profit growth — but the pace depends heavily on pricing discipline across the sector and the infrastructure spend cycle.
Expert Observation
The July 20 board meeting arrives at a moment when UltraTech's valuation demands proof that the FY26 supercycle wasn't a one-time event. The special dividend and the historic PAT crossing ₹8,000 crore set extraordinarily high expectations. What the market needs to see now isn't just another quarter of growth — it's evidence that the structural cost advantages built over the last two years (green power, India Cements integration, debt reduction) are durable. If management can credibly signal that Q2 and Q3 volumes will recover sharply once construction activity picks up post-monsoon, the premium valuation has a reasonable defense.
Investor Takeaway
UltraTech's Q1 FY27 results on July 20 are a quarterly event with longer-cycle implications. The immediate read will be volume growth, EBITDA per tonne, and management guidance. But the underlying story — a company that crossed ₹8,000 crore in annual profit for the first time, declared a ₹240/share special dividend, and built 200 MTPA+ capacity — doesn't change in a single monsoon quarter. Long-term investors should use any post-result volatility as an opportunity to reassess entry points rather than react to seasonal noise. Short-term traders should respect the PE premium and position sizing accordingly heading into the July 20 announcement.
Conclusion
India's largest cement maker is four weeks from its next earnings test. The question on July 20 isn't whether UltraTech is a well-run company — that argument was settled in FY26. The question is whether the first quarter of FY27 shows enough resilience to justify a stock trading at a meaningful premium to its sector peers, and whether the management's tone on demand recovery can extend the confidence built through a historic year. For the cement sector broadly, and for investors tracking India's construction and infrastructure supercycle, this is one of the season's key events.
Explore More Investment Opportunities
Want to track India's unlisted and listed market movements before they hit the index?
👉 Explore pre-IPO opportunities, unlisted share prices, and FPI flow data — only on ShareBazaar Online.