
Dividend Snapshot – Colgate-Palmolive (India) Limited
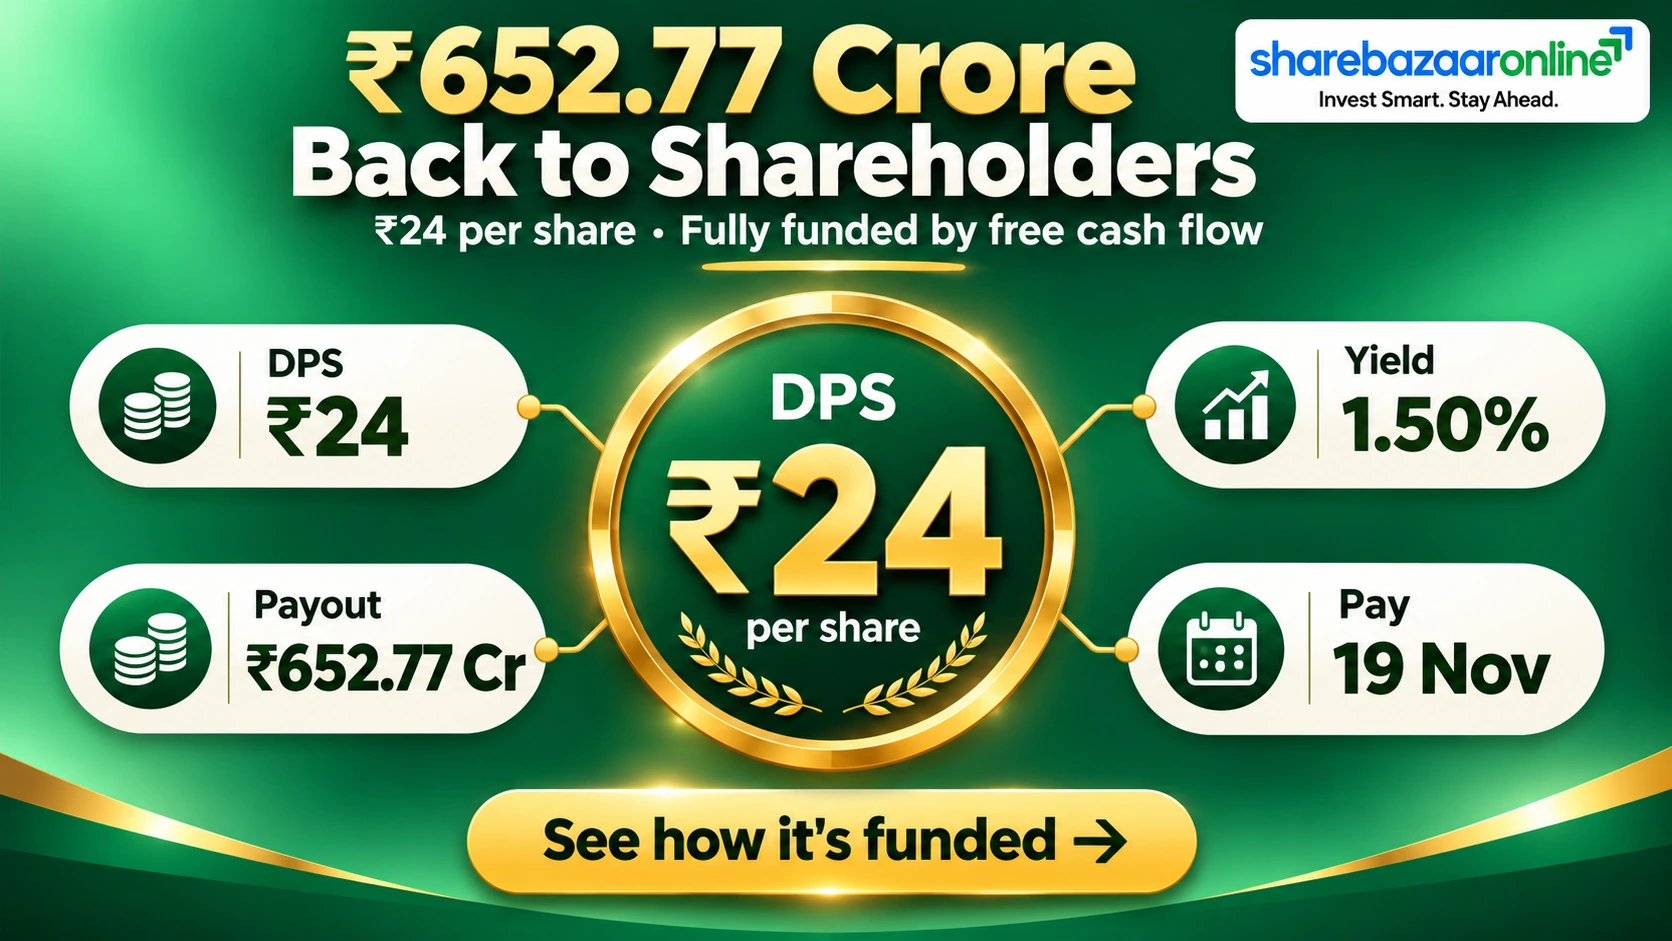
The Colgate-Palmolive (India) dividend for FY2026-27 is a First Interim Dividend of ₹24 per equity share on a face value of ₹1, declared with the Q2 FY27 results on 22 October 2026. The headline looks like a 2,400% dividend, but on the market price of about ₹1,594.70 (NSE close, 30 Oct 2026), the real interim yield is only 1.50%. Including the ₹24 paid in June 2026, the trailing-twelve-month payout of ₹48 gives a yield of about 3.01% (cited: Screener/TipRanks).
Dividend Per Share
₹24.00
First Interim, FY2026-27 (Face Value ₹1)
Interim Yield (on CMP ₹1,594.70)
1.50%
TTM yield (₹48): 3.01%
Record Date
02 Nov 2026
Payment on & from 19 Nov 2026
Total Dividend Outflow
₹652.77 Cr
On 27.20 crore shares
Colgate-Palmolive (India) Limited: Company Overview
Colgate-Palmolive (India) Limited (NSE: COLPAL, BSE: 500830, ISIN: INE259A01022) is the country’s market leader in Oral Care, operating across toothpaste, toothbrush, mouthwash and personal care (Palmolive). It is a multinational subsidiary of Colgate-Palmolive Company, USA, which holds 51% of the equity. The company has no subsidiaries, so its consolidated and standalone accounts are identical, and it reports a single primary segment, Personal Care (including Oral Care). For Q2 FY27 it posted net sales of ₹1,691.57 crore (up 12.2% year-on-year) and net profit of ₹341.57 crore. Managing Director & CEO Mr. Manish Anandani described it as a second straight quarter of double-digit topline growth, led by premium toothpaste and Colgate MaxFresh.
Colgate-Palmolive (India) Financial Analysis
Colgate-Palmolive (India) remains a high-margin, asset-light, essentially debt-free business. In Q2 FY27 gross margin expanded about 40 bps to 69.6% (management figure), yet net profit grew only 4.3% against 12.2% sales growth — because the company re-invested heavily in brand-building. Half-year (H1 FY27) net profit was ₹684.65 crore (EPS ₹25.17) on sales of ₹3,282.13 crore. For the full year FY26, net profit was ₹1,325.31 crore (EPS ₹48.73), down 7.8% on broadly flat sales. The company reports an exceptionally high ROE of ~158% and ROCE of ~179% for FY26 (cited: Screener) — inflated by a very small equity base kept thin by near-full dividend payouts.
Colgate-Palmolive (India) Dividend History Table
Annual dividend per share paid by Colgate-Palmolive (India) Limited over recent financial years (dividends grouped by the financial year they relate to; source: exchange records via TipRanks). The ₹10 special dividend in May 2024 is included in FY24.
| Financial Year | Total Dividend Per Share | Notes |
|---|---|---|
| FY2026-27* | ₹24.00 | First Interim only (ongoing) |
| FY2025-26 | ₹48.00 | ₹24 + ₹24 |
| FY2024-25 | ₹51.00 | ₹24 + ₹27 |
| FY2023-24 | ₹58.00 | ₹22 + ₹26 + ₹10 special |
| FY2022-23 | ₹39.00 | ₹18 + ₹21 |
| FY2021-22 | ₹40.00 | ₹19 + ₹21 |
| FY2020-21 | ₹38.00 | ₹18 + ₹20 |
*FY27 reflects the first interim only; a second interim is typically declared in May.
Expert Commentary on the Colgate-Palmolive (India) Dividend
The real story behind the Colgate-Palmolive (India) dividend is not the ₹24 cheque — it is the denominator. The “2,400% dividend” headline is a face-value optical illusion; the cash return on money actually invested is just 1.50% on the current price. The trailing yield has drifted up to 3.01% largely because the share price has fallen roughly 28% over the past year (cited: exchange data) to near a 52-week low, not because the dividend has surged. Separately, a near-40% jump in advertising spend is the specific reason Q2 profit grew only 4.3% while sales rose 12.2%. Investors should read this as a brand-reinvestment quarter dressed in a steady, cash-funded dividend.
Colgate-Palmolive (India) Future Outlook
Management has guided for continued “robust growth” anchored by a science-backed portfolio and stepped-up advertising — disclosed commentary, not a forecast of future dividends. On the dividend itself, the pattern suggests the first interim of ₹24 is usually followed by a second interim around May; over the last three years total annual payout has ranged between ₹48 and ₹58. Whether that continues depends on earnings, which are currently growing in low-single digits after a GST-transition-affected FY26. With net cash of about ₹1,539 crore and strong cash generation, the company retains ample capacity to sustain distributions, though any special dividend remains undisclosed. No forward dividend amount beyond this interim has been announced.
Colgate-Palmolive (India) Dividend Announcement Summary
At its board meeting on 22 October 2026, Colgate-Palmolive (India) Limited approved its unaudited Q2 and H1 FY27 results and declared a First Interim Dividend of ₹24 per equity share of face value ₹1 for the financial year 2026-27. As an interim dividend declared by the Board, it does not require separate shareholder/AGM approval. The company disclosed a total payout of ₹652.77 crore (₹65,277 lakh). The dividend is payable on and from 19 November 2026 to shareholders on the Register of Members/Beneficial Owners as on the record date, 2 November 2026. The Board also noted management changes and a postal-ballot process for the MD & CEO appointment — separate from the dividend.
Colgate-Palmolive (India) Key Dates Timeline
Announcement Date
22 October 2026
Ex-Dividend Date
02 November 2026
Record Date
02 November 2026
Payment Date
On & from 19 November 2026
Under India’s T+1 settlement regime, the ex-dividend date and record date for Colgate-Palmolive (India) fall on the same day, 2 November 2026 — consistent with the company’s recent dividends. The record date is the company-disclosed date; eligibility was determined by holdings registered as on that date.
Colgate-Palmolive (India) Dividend Yield Analysis
This is where the face-value illusion matters most. The ₹24 dividend on a ₹1 face value reads as 2,400%, but dividend yield is always measured against the market price. On the latest price of ₹1,594.70, the interim yield is 1.50%; against the announcement-day reference price of about ₹1,685 it is 1.42%. Counting both interim dividends of the last twelve months (₹48), the trailing yield is 3.01%. So the number that matters to a buyer today is between 1.5% (per interim) and ~3% (annualised) — not 2,400%, and not a fixed-deposit substitute.
Colgate-Palmolive (India) Dividend History Analysis
On consistency, Colgate-Palmolive (India) is a textbook Consistent Payer: it has paid dividends every year for well over a decade, twice a year, without a single suspension in recent history. On growth, the annual payout rose from ₹38 (FY21) to a peak of ₹58 (FY24), helped by a one-time ₹10 special dividend, then normalised to ₹51 (FY25) and ₹48 (FY26). The slight step-down tracks softer FY26 earnings rather than a change in policy — there have been no dividend cuts in the ordinary payout. The FY27 first interim of ₹24 is unchanged from the prior two first-interim payments, signalling policy continuity.
Colgate-Palmolive (India) Financial Performance Analysis
The operating-leverage picture explains the quarter. In Q2 FY27, sales rose 12.2% but total expenses rose 16.0%, so profit before tax grew only 4.1% and net profit 4.3%. The single biggest driver of the gap was advertising spend, up ~39.9% year-on-year (₹314.82 crore vs ₹225.10 crore), as management funded premiumisation and new launches. Employee cost rose 15.1% and material cost 9.2%. This is deliberate margin re-investment, not margin erosion — gross margin actually improved. H1 FY27 net profit grew 5.6%, while FY26 profit had fallen 7.8% on flat sales. The business is growing the top line strongly; profit flow-through is being traded for brand investment.
Colgate-Palmolive (India) Cash Flow Analysis
Reported profits are an opinion; cash is a fact — and here the cash backs the profit. In H1 FY27, operating cash flow was ₹838.79 crore against net profit of ₹684.65 crore, an OCF/PAT ratio of 1.23x — healthy, high-quality earnings conversion. After capex of just ₹58.05 crore, free cash flow was ₹780.74 crore. Trade receivables rose about 8%, below the 12% sales growth, so there is no receivables red flag. Crucially, the interim dividend outflow of ₹652.77 crore is comfortably funded by current free cash flow (1.20x FCF coverage), not by borrowings or asset sales. The dividend is paid out of genuine operating cash.
Colgate-Palmolive (India) Balance Sheet Strength
Colgate-Palmolive (India) is effectively debt-free. As at 30 September 2026 it held ₹1,587.74 crore in cash and cash equivalents (plus ₹42.56 crore of other bank balances), against only lease liabilities of about ₹48.72 crore and no borrowings — a net cash position of roughly ₹1,539 crore. Total equity stood at ₹1,617.64 crore. The cash pile alone covers the entire ₹652.77 crore interim outflow 2.43 times over. This fortress balance sheet is why the dividend, while large relative to profit, carries little solvency risk. The flip side is a deliberately small equity base, which is what produces the eye-catching (but somewhat mechanical) ROE and ROCE figures.
Colgate-Palmolive (India) Dividend Sustainability Analysis
Applying a four-test scorecard to the Colgate-Palmolive (India) dividend:
- Earnings coverage: Trailing payout ratio is ~95.9% (FY26 ~98.5%) — very high; coverage of only 1.05x leaves little cushion.
- Operating cash coverage: Strong — OCF/PAT of 1.23x means profits are cash-backed.
- Free cash flow coverage: Adequate — FCF covers the interim outflow 1.20x.
- Liquidity/cash coverage: Excellent — cash covers the outflow 2.43x, with no debt.
Verdict: Sustainable in cash terms, but earnings-stretched — a thin payout cushion means dividend growth now depends on earnings recovery, not balance-sheet capacity.
Colgate-Palmolive (India) Peer Comparison
Against listed FMCG peers, Colgate-Palmolive (India)’s trailing yield screens above most staples, though below ITC. Figures are indicative, cited from public sources (Trendlyne/Screener, 2026) and move with price.
| Company | Approx. Dividend Yield | Approx. ROE |
|---|---|---|
| Colgate-Palmolive (India) | ~3.0% (TTM) | ~158% |
| ITC | ~4.6% | ~48% |
| Hindustan Unilever | ~1.8% | ~21% |
| Dabur India | ~1.9% | ~17% |
| Godrej Consumer | ~1.9% | ~15% |
| Nestlé India | ~0.8% | ~87% |
| Marico | ~0.8% | ~42% |
The Nifty FMCG index yields roughly 1.0%–1.2% currently, so Colgate’s ~3% screens high — but that gap partly reflects Colgate’s share-price fall, not uniquely generous payouts. On capital efficiency, Colgate and Nestlé lead on ROE.
Colgate-Palmolive (India) Promoter Impact Analysis
With the US parent holding 51%, the promoter receives the largest single share of every dividend. Of the ₹652.77 crore interim outflow, approximately ₹332.91 crore flows to the promoter group; on a trailing ₹48 annual basis that is about ₹665.86 crore a year. The remaining ~49% (about ₹319.86 crore this interim) is shared among public shareholders, FIIs and domestic institutions. A notable governance signal: over two years FII holding fell sharply from 24.51% to 13.71% while DII holding rose from 5.82% to 15.45% (Sep 2026, cited: Screener) — a large ownership rotation out of foreign and into domestic hands, even as the promoter stake stayed steady at 51%. High dividends benefit all holders proportionally, but the near-full payout also limits reinvestment of retained earnings.
Colgate-Palmolive (India) Dividend Taxation Analysis
In India, dividends are taxable in the hands of the shareholder at their applicable income-tax slab rate. The company deducts TDS at 10% under Section 194 if total dividend paid to a resident exceeds ₹5,000 in a financial year (a valid Form 15G/15H or lower-deduction certificate can reduce this). The TDS is adjusted against final tax liability.
Worked example — 1,000 shares, 30% tax slab:
- Gross dividend (1,000 × ₹24): ₹24,000
- TDS at 10% (Section 194): ₹2,400 withheld
- Tax at 30% + 4% cess: ₹7,488
- Net dividend after full tax: ₹16,512
- Post-tax effective yield (on ₹15,94,700 invested at CMP): ~1.04% for this interim
Surcharge may apply at higher incomes. This is general information, not tax advice.
Colgate-Palmolive (India) Key Risks
- Thin payout cushion: With payout near 96-98% of earnings, any dip in profit directly pressures future dividend growth.
- Earnings under GST/pricing pressure: FY26 profit fell 7.8%; sales were flat, and rising advertising/input costs can compress net profit even when sales grow.
- Share-price weakness: The stock is down roughly 28% over a year near 52-week lows; a high trailing yield can mask capital erosion.
- Category concentration: Heavy reliance on oral care/toothpaste leaves little diversification if that category slows.
- Competition & premiumisation cost: Defending share requires sustained ad spend, which caps margin expansion.
- FII exit: Foreign holding has dropped from 24.5% to 13.7%, a sentiment overhang despite steady DII buying.
What to Monitor in Colgate-Palmolive (India)
- Volume growth vs value growth: Watch whether double-digit sales are volume-led or price-led in coming quarters.
- Advertising-to-sales ratio: Track whether the ~40% ad-spend step-up normalises and lets profit growth catch up with sales.
- The second interim dividend (usually May): Its size will confirm whether total FY27 payout holds near ₹48-51.
- Gross and operating margin trend: Sustaining the ~69.6% gross margin amid input-cost swings.
- Premium portfolio traction: Growth in premium toothpaste and personal care, the stated growth engine.
- Institutional ownership: Whether DII buying continues to absorb FII selling.
Conclusion: Colgate-Palmolive (India) Dividend
The Colgate-Palmolive (India) first interim dividend of ₹24 per share is a steady, fully cash-funded payout from a debt-free market leader — but it is best understood in real terms, not as a 2,400% headline. Positives: consistent payer, 2.43x cash coverage, 1.23x OCF/PAT, strong 12.2% sales growth. Negatives: near-96% payout leaves little room; FY26 profit fell 7.8%; the ~3% trailing yield is flattered by a ~28% price fall. Risks centre on earnings pressure and FII exit; monitoring should focus on the ad-spend ratio and the next interim. The dividend is safe in cash terms today; its growth depends on an earnings recovery. Readers should weigh these facts and decide for themselves.
Frequently Asked Questions About the Colgate-Palmolive (India) Dividend
What dividend has Colgate-Palmolive (India) announced?
What is the Colgate-Palmolive (India) dividend yield?
What is the record date for the Colgate-Palmolive (India) dividend?
What is the ex-dividend date for Colgate-Palmolive (India)?
When will the Colgate-Palmolive (India) dividend be paid?
Who is eligible for the Colgate-Palmolive (India) dividend?
How is the Colgate-Palmolive (India) dividend taxed?
Is the Colgate-Palmolive (India) dividend sustainable?
What is the Colgate-Palmolive (India) dividend history?
Why did Colgate-Palmolive (India) profit grow slower than sales?
What should investors monitor in Colgate-Palmolive (India)?
What are the NSE and BSE codes for Colgate-Palmolive (India)?
Disclaimer – Colgate-Palmolive (India) Limited
This article is for informational and educational purposes only and is based on publicly disclosed company filings and cited public sources as of 2 November 2026. It is not investment, legal or tax advice, and does not constitute a buy, sell or hold recommendation. ShareBazaar Online is not a SEBI-registered investment adviser. Market prices, yields and figures change and may differ from values shown here; readers should verify data against official NSE/BSE and company disclosures and consult a qualified financial or tax professional before making any decision. Dividend taxation depends on individual circumstances. Investments in securities are subject to market risks.