
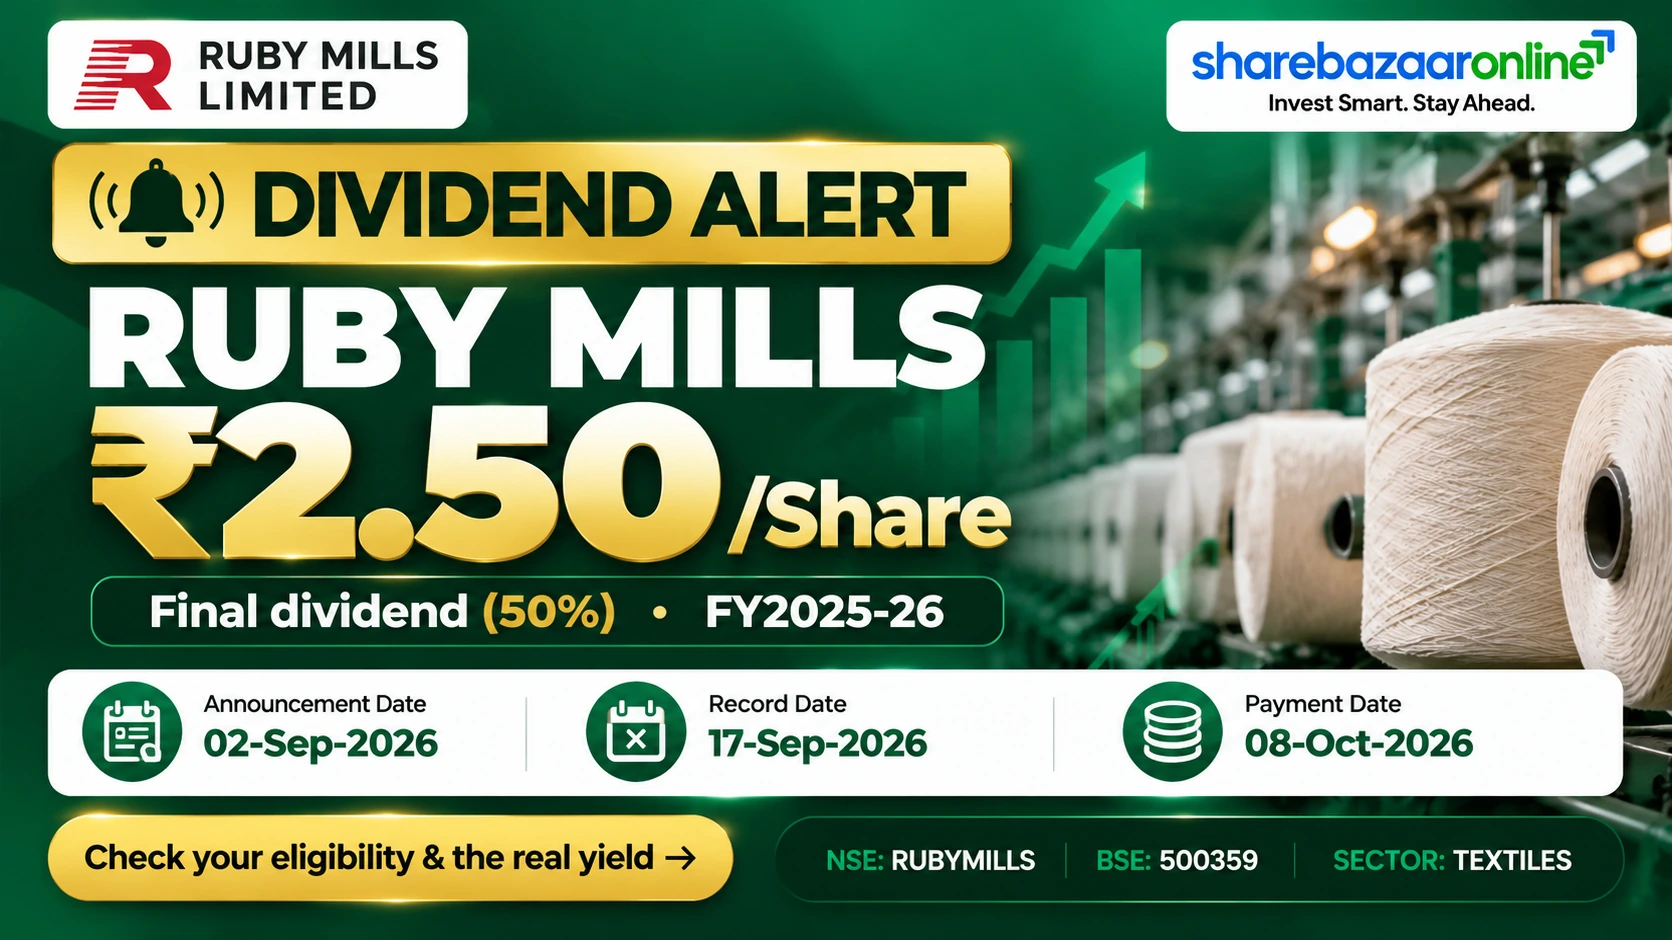
Dividend Snapshot – The Ruby Mills Limited
The Ruby Mills Limited (NSE: RUBYMILLS, BSE: 503169) has declared a final dividend of ₹2.50 per equity share for FY2025-26, recommended by its Board on 28 May 2026 and subject to shareholder approval at the AGM. On the ₹5 face value, this works out to a headline 50% dividend — but the real Ruby Mills dividend yield on the market price is far smaller, which is the number income investors should focus on.
Headline Figures
- Dividend per share: ₹2.50
- Dividend %: 50% of ₹5 face value
- Dividend type: Final (FY2025-26)
- Record date: 17 September 2026
What It Means for Yield
- Market yield on CMP (~₹494): ~0.51%
- Total payout: ₹8.36 Cr
- Payout ratio: 19.2% of PAT
- EPS cover: 5.21x
Company Overview – The Ruby Mills Limited
The Ruby Mills Limited is a Mumbai-based company incorporated in 1917, operating across two very different segments: a composite textile business (cotton and blended yarn and fabric, with plants at Khopoli) and a real-estate arm that develops and leases commercial property. This dual identity matters for any Ruby Mills dividend analysis, because textile margins and property income behave differently through a cycle. In FY2025-26 the company also incorporated two wholly-owned subsidiaries, Ruby Greentech T and Ruby Greentech K (March 2026), signalling fresh capital deployment. Promoters hold a high 74.90% stake, so the free float is thin and the stock can be volatile — a point that directly shapes how the dividend is distributed and how the yield reads.
Financial Analysis – The Ruby Mills Limited
The headline FY2025-26 numbers look strong, but the mix is the real story. Consolidated revenue jumped ~46% to ₹358.60 Cr, yet net profit rose only ~3% to ₹43.58 Cr. That gap is the single most important finding in this Ruby Mills dividend review: revenue growth did not convert into profit growth. Net margin fell from roughly 17.2% to 12.2%, and about 33% of pre-tax profit (₹17.56 Cr of ₹53.01 Cr) came from other income rather than core operations. EBITDA was ₹75.37 Cr (~21% margin) and EPS stood at ₹13.03. The dividend is comfortably covered by earnings, but the quality and durability of those earnings deserve scrutiny.
The Ruby Mills Limited Dividend History Table
| Financial Year | Dividend/Share | % of Face Value | Type |
|---|---|---|---|
| FY2020-21 | ₹0.75 | 15% | Final |
| FY2021-22 | ₹3.00 | 60% | Final |
| FY2022-23 | ₹1.25 | 25% | Final |
| FY2023-24 | ₹1.75 | 35% | Final |
| FY2024-25 | ₹1.75 | 35% | Final |
| FY2025-26 | ₹2.50 | 50% | Final |
The ₹2.50 payout is a clear step up from the ₹1.75 held for two years, yet it still sits below the FY2021-22 peak of ₹3.00. The pattern is uneven, not steadily rising. Historical dividend figures are compiled from public exchange and market sources.
Expert Commentary on The Ruby Mills Limited Dividend
For income-seekers, the critical lesson from the Ruby Mills dividend is the face-value illusion. A "50% dividend" sounds generous, but 50% is calculated on the ₹5 face value, not the market price. At a market price of roughly ₹494, the actual cash yield is only about 0.51% — far below a bank savings account. The ₹2.50 payout is better read as a modest shareholder reward attached to a stock that has re-rated sharply (the price ran from a 52-week low near ₹169 to a high above ₹500). The dividend is not the investment case here; the operating turnaround, real-estate monetisation, and margin trend are. Investors chasing yield will find little; those watching the business should watch margins.
The Ruby Mills Limited Dividend Outlook
The forward picture depends on whether The Ruby Mills Limited can turn its top-line surge into durable profit. Revenue has nearly doubled over recent years, but margins compressed in FY2025-26, and the two new Greentech subsidiaries plus heavy investing outflows suggest capital is being directed toward growth rather than larger distributions. On that basis, a dramatic jump in dividend per share is not indicated by current disclosures. The company has lifted its payout from ₹1.75 to ₹2.50, but it remains a low-payout, reinvestment-focused business. The realistic outlook is a stable-to-gradually-rising dividend tracking profit, not a high-yield income stream. Any forward view here is editorial context, not a forecast of future corporate action.
The Ruby Mills Limited Dividend Announcement Summary
Disclosed by the Company
- Dividend: ₹2.50/share (Final, FY2025-26)
- Board recommendation: 28 May 2026
- Record date: 17 September 2026
- Book closure: 18–24 September 2026
- AGM approval: Required
Identifiers & Scale
- NSE / BSE: RUBYMILLS / 503169
- ISIN: INE301D01026
- Face value: ₹5
- Shares outstanding: ~3.34 Cr
- Total dividend outflow: ₹8.36 Cr
The payment date was not disclosed in the record-date intimation. Under the Companies Act, 2013, a final dividend must be paid within 30 days of its declaration at the AGM.
The Ruby Mills Limited Dividend Key Dates Timeline
| Event | Date | Status |
|---|---|---|
| Board recommendation | 28 May 2026 | Disclosed |
| Ex-date | 17 September 2026 | Same as record date (T+1 regime) |
| Record date | 17 September 2026 | Disclosed |
| Book closure | 18–24 September 2026 | Disclosed (AGM & dividend) |
| Payment date | Not Disclosed by Company | Within 30 days of AGM |
Eligibility was fixed by the 17 September 2026 record date, which has now passed. Shareholders on the register that day were entitled to the ₹2.50 per share. Under India's current settlement cycle, the ex-date and record date fall on the same day.
The Ruby Mills Limited Dividend Yield Analysis
This is where the Ruby Mills dividend yield needs a reality check. The ₹2.50 payout equals 50% of face value, but on the market price of about ₹494 (early October 2026), the real yield is only ~0.51%. Even against the lower price around the May announcement (~₹300), the yield was still only about 0.83%. The reason the headline looks large and the yield looks tiny is simple: the share has re-rated more than 2.5x off its 52-week low, so the denominator (price) has grown far faster than the numerator (dividend). For comparison, that 0.51% is well below both the textile-sector average and a bank deposit — confirming this is a growth/value stock, not an income stock.
The Ruby Mills Limited Dividend History Analysis
Judged over six years, The Ruby Mills Limited is best classified as an irregular / cyclical dividend payer, not a consistent grower. The per-share dividend went ₹0.75 (FY21) → ₹3.00 (FY22) → ₹1.25 (FY23) → ₹1.75 (FY24) → ₹1.75 (FY25) → ₹2.50 (FY26). That is a sharp spike, a steep cut, then a gradual climb — the opposite of a smooth dividend-growth record. Importantly, the latest ₹2.50 is still 17% below the ₹3.00 paid in FY2021-22. For dividend-history seekers, the takeaway is that payouts here move with profits and management's capital-allocation mood, so past peaks are not a reliable guide to the next payout.
The Ruby Mills Limited Financial Performance Analysis
The operating-leverage picture is unusual: revenue surged but profit barely moved. FY2025-26 consolidated revenue rose +46.2% to ₹358.60 Cr, EBITDA was about ₹75.37 Cr (~21% margin), yet PAT grew just +3.0% to ₹43.58 Cr. In Q4 specifically, profit actually fell ~31% year-on-year despite revenue rising over 50%. The reasons are margin compression (a higher share of lower-margin revenue), higher costs including interest, and a heavy reliance on other income, which made up roughly 33% of pre-tax profit. Net margin slipped from ~17.2% to ~12.2%. The dividend is funded from genuine earnings, but the earnings engine weakened in quality even as the top line grew.
The Ruby Mills Limited Cash Flow Analysis
Cash is fact, and here the facts are mixed. FY2025-26 operating cash flow was roughly ₹62.82 Cr — healthy, and about 7.5x the ₹8.36 Cr dividend outflow. So the dividend itself is easily funded from operations. The catch sits below that line: investing outflow was about ₹111.50 Cr (capex plus the new subsidiaries and investments), which exceeded operating cash by nearly ₹49 Cr. The company bridged that gap with ~₹52.51 Cr of fresh financing (borrowings). In plain terms, the dividend is covered by operating cash, but the company is simultaneously raising debt to fund expansion. That is acceptable for a growth phase, but it means free cash flow after investment was effectively negative this year.
The Ruby Mills Limited Balance Sheet Strength
The balance sheet is moderately geared rather than stretched. Book value per share is roughly ₹190, giving net worth in the region of ₹600–640 Cr on a ₹16.72 Cr equity base. The debt-to-equity ratio is around 0.36 — manageable, but notable because borrowings rose in FY2025-26 to fund investment even as the dividend was paid. Cash and equivalents of about ₹60 Cr cover the ₹8.36 Cr dividend around 7.2x, so near-term distribution capacity is not in question. Returns are soft, however: ROE is roughly 6.5% and ROCE in the mid-single digits, both below the cost of capital. A solid asset base supports the dividend; weak returns on that base are the longer-term concern.
The Ruby Mills Limited Dividend Sustainability Analysis
Four-Test Sustainability Scorecard
- Earnings cover (EPS ₹13.03 vs DPS ₹2.50): 5.21x — Strong
- Operating-cash-flow cover (₹62.82 Cr vs ₹8.36 Cr): 7.5x — Strong
- Free-cash-flow cover (after ₹111.5 Cr investing): Negative FCF — Weak
- Liquidity cover (cash ~₹60 Cr): 7.2x — Adequate
Verdict: Moderately Sustainable. The small ₹2.50 dividend is easily affordable from earnings, cash and operating flows. The only caution is that free cash flow turned negative after heavy investment, and debt rose in the same year — so sustainability rests on profits holding up, not on surplus free cash.
The Ruby Mills Limited Peer Comparison
| Company | Div. Yield | ROE | Net Margin |
|---|---|---|---|
| The Ruby Mills | ~0.5% | ~6.5% | ~10.8% |
| Arvind | ~1%+ | ~11.1% | ~4.3% |
| Garware Technical | Low | ~16.6% | ~12.4% |
| Raymond | Low | ~1.1% | ~2.8% |
Against peers, The Ruby Mills Limited offers a sector-typical low dividend yield and a below-average ROE, though its net margin is respectable thanks to its property income. In short, dividend yield is not where Ruby Mills stands out among textile names. Peer figures are compiled from public market sources.
The Ruby Mills Limited Promoter Impact Analysis
With promoters holding 74.90%, the economics of this dividend flow mostly to the promoter group. Of the ₹8.36 Cr total outflow, roughly ₹6.26 Cr goes to promoters and only about ₹2.09 Cr to all public shareholders combined. That is not wrong — every shareholder receives the same ₹2.50 per share — but it frames the decision: a low-payout, reinvestment strategy keeps more capital inside a company the promoters overwhelmingly own. The thin ~25% free float also explains the stock's sharp price swings. For minority investors, the practical point is that dividend policy is effectively set by a controlling family whose interests are served about equally by paying out and by reinvesting.
The Ruby Mills Limited Dividend Taxation Analysis
In India, dividends are taxed in the investor's hands at their income-tax slab rate. Under Section 194, the company deducts 10% TDS only if total dividend from it exceeds ₹10,000 in a financial year (threshold raised from ₹5,000 effective FY2025-26). Below that, no TDS is cut, but the dividend remains fully taxable.
Worked Example — 1,000 shares, 30% slab
- Gross dividend: 1,000 × ₹2.50 = ₹2,500
- TDS u/s 194 (below ₹10,000): ₹0
- Tax at 30% slab (paid on filing): ₹750
- Net dividend in hand: ₹1,750
- Post-tax effective yield (on ~₹494): ~0.35%
This is general information, not tax advice; investors should confirm their own position with a qualified professional.
Key Risks for The Ruby Mills Limited Investors
- Margin compression: Revenue rose 46% but PAT only 3% and net margin fell to ~12.2%; profitability is not keeping pace with growth.
- Earnings quality: About 33% of pre-tax profit came from other income, which can be lumpy and may not repeat.
- Rising debt & negative FCF: Investing outflow exceeded operating cash, bridged by fresh borrowing, so free cash flow after capex was negative.
- Thin free float & volatility: With 74.90% promoter holding, ~25% float makes the stock prone to sharp swings (52-week range ~₹169 to ~₹524).
- Negligible dividend yield: At ~0.51%, the payout offers almost no income cushion if the price corrects.
- Cyclical dual business: Textiles face input-cost and demand cycles; real-estate income can be irregular.
What to Monitor in The Ruby Mills Limited
- Margin trajectory: Whether EBITDA and net margins recover toward prior-year levels in upcoming quarters.
- Core vs other income: How much of profit comes from operations rather than fair-value or one-off gains.
- Debt trend: Whether borrowings keep rising to fund investment, and the direction of the debt-to-equity ratio.
- Greentech subsidiaries: Capital committed to Ruby Greentech T and K, and the returns they generate.
- Payout policy: Whether the dividend per share holds, rises toward the ₹3.00 FY22 peak, or is trimmed in a weaker year.
- Real-estate monetisation: Progress on property development and lease income, a key swing factor for profits.
Conclusion – The Ruby Mills Limited Dividend
The Ruby Mills Limited's ₹2.50 final dividend for FY2025-26 is a genuine step up from ₹1.75, comfortably covered by earnings (5.21x) and operating cash (7.5x), and so moderately sustainable. But the Ruby Mills dividend yield of around 0.51% tells investors this is not an income stock — the 50% headline is purely a face-value artefact. The sharper signals sit in the financials: revenue up 46% but profit up only 3%, margins compressing, a third of profit from other income, and expansion funded partly by new debt. The positives are a long asset base, a modest reliable payout and real-estate optionality; the negatives are weak returns and earnings quality. We present the facts and the risks — the decision rests with the reader.
Frequently Asked Questions About The Ruby Mills Limited Dividend
What dividend has The Ruby Mills Limited announced for FY2025-26?
What is The Ruby Mills Limited dividend yield?
What is the record date for The Ruby Mills dividend?
What is the ex-date for The Ruby Mills dividend?
When will The Ruby Mills Limited pay the dividend?
Who was eligible for The Ruby Mills dividend?
How is The Ruby Mills dividend taxed?
Is The Ruby Mills Limited dividend sustainable?
What is The Ruby Mills Limited dividend history?
What should investors monitor after The Ruby Mills dividend?
Why is the Ruby Mills dividend yield so low despite a 50% dividend?
How much of The Ruby Mills dividend goes to promoters?
What is the total dividend outflow for The Ruby Mills Limited?
Disclaimer – The Ruby Mills Limited Dividend Analysis
This article is for informational and educational purposes only and does not constitute investment, legal or tax advice, nor a recommendation to buy, sell or hold any security. ShareBazaar Online is not a SEBI-registered investment adviser. Dividend-related figures disclosed by The Ruby Mills Limited are drawn from its official exchange filings; market prices, financial ratios, dividend history, shareholding and peer data are compiled from publicly available sources and may contain errors or become outdated. Figures marked "Not Disclosed by Company" were unavailable at the time of writing. Taxation depends on individual circumstances and prevailing law. Investors should verify all data independently and consult a qualified financial or tax professional before making any decision. Past dividends are not a guide to future payouts.