
Dividend Snapshot – Ramky Infrastructure Limited
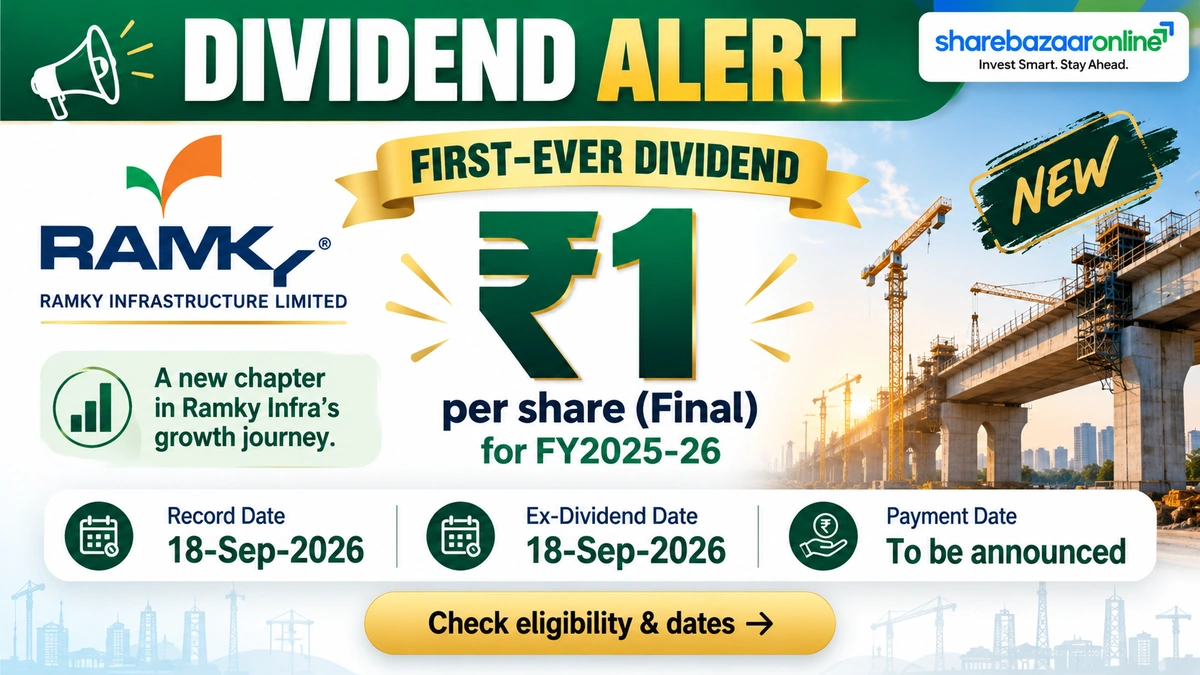
Ramky Infrastructure Limited (NSE: RAMKY, BSE: 533262) has declared its first-ever dividend as a listed company — a final dividend of ₹1 per equity share for FY2025-26. The headline reads as a 10% dividend, but that figure is calculated on the ₹10 face value. At the latest market price near ₹321.95, the real Ramky Infrastructure dividend yield is just 0.31%. This is a symbolic payout from a company that paid nothing for over a decade while it worked down a heavy debt load.
Company Overview – Ramky Infrastructure Limited
Ramky Infrastructure Limited is the flagship construction and infrastructure-development arm of the Hyderabad-based Ramky Group, incorporated in 1994 and listed since 2010. It runs an integrated engineering, procurement and construction (EPC) business across water and wastewater, irrigation, transportation, industrial and building construction, alongside a developer business of annuity and PPP assets.
The company spent much of the last decade repairing a stressed balance sheet. Borrowings fell roughly 82%, from about ₹3,240 Cr in FY2014 to ₹570 Cr in FY2025, and management described the firm as effectively debt-free by late 2025. Its order book has since crossed ₹13,000 crore, anchored by large water and wastewater wins. This FY26 maiden dividend marks the point at which Ramky Infrastructure began returning cash to shareholders.
Financial Analysis – Ramky Infrastructure Limited
Profitability (Consolidated)
FY26 consolidated net profit rose to about ₹283 Cr, up roughly 40% from ₹202 Cr a year earlier, lifting EPS to ₹39.17. ROCE stands near 16.8% and ROE near 10.9%. Importantly, FY26 profit was helped by a one-time exceptional gain of ₹59.46 Cr from the sale of a 51% stake in subsidiary Visakha Pharmacity — a point we revisit under sustainability.
Scale & Valuation
Market capitalisation is around ₹2,200–2,500 Cr at recent prices, with a P/E near 13x and book value of about ₹297 per share (P/B ~1.1x). Revenue from operations in FY26 was broadly flat-to-lower versus FY25, so the profit jump came more from margin, lower interest cost and the exceptional item than from top-line expansion.
Ramky Infrastructure Limited Dividend History
Ramky Infrastructure dividend payment history shows no payout across the decade before FY26. The table below reflects the dividend payout ratio reported by the company for each year.
| Financial Year | Dividend / Share | Payout Ratio | Status |
|---|---|---|---|
| FY2025-26 | ₹1.00 | ~2.45% | First dividend |
| FY2024-25 | ₹0.00 | 0% | No payout |
| FY2023-24 | ₹0.00 | 0% | No payout |
| FY2022-23 | ₹0.00 | 0% | No payout |
| FY2021-22 | ₹0.00 | 0% | No payout |
| FY2014-15 to FY2020-21 | ₹0.00 | 0% | No payout |
Source: company filings / Screener.in consolidated payout data.
Expert Commentary – Ramky Infrastructure Limited Dividend
The single most important thing retail investors should understand about the Ramky Infrastructure dividend is the gap between the headline and the reality. A ₹1 dividend on a ₹10 face value is correctly described as 10%, but that is not what the investor earns. On the market price of about ₹321.95, the actual cash return is 0.31% — roughly one-thirtieth of the headline.
The more meaningful signal is intent, not amount. After paying nothing for over a decade, the board choosing to pay anything is a statement that the balance-sheet repair is viewed as durable. CFO commentary tied the decision to ₹6.92 Cr of total outflow — about 2.45% of FY26 profit — a deliberately conservative first step that preserves cash for equity commitments to new projects.
Ramky Infrastructure Limited Dividend Outlook
Because this is a maiden dividend, there is no track record to extrapolate and the company has not disclosed a formal dividend policy or future payout target. What can be said factually is that the payout is tiny relative to earnings and cash generation, which leaves ample room for the board to raise it in future years if profitability holds — though no such commitment has been made.
The outlook for the Ramky Infrastructure dividend therefore rests on two visible levers: continued execution of the ₹13,000+ crore order book, and whether FY26's one-time stake-sale gain is replaced by recurring operating profit. Investors should treat any future increase as possible but unconfirmed.
Dividend Announcement Summary – Ramky Infrastructure Limited
At its board meeting on 27 May 2026, the board of Ramky Infrastructure Limited recommended a final dividend of 10% — ₹1 per equity share of ₹10 each — for the financial year 2025-26, subject to shareholder approval at the Annual General Meeting. Via a Regulation 42 intimation dated 10 September 2026, the company fixed Friday, 18 September 2026 as the record date for determining shareholder entitlement. The AGM was held on Saturday, 26 September 2026, and the filing stated the approved dividend would be paid within 30 days of the AGM, subject to deduction of tax at source as applicable.
Key Dates Timeline – Ramky Infrastructure Limited Dividend
Under India's T+1 settlement, the ex-date and record date coincide on 18 September 2026 as confirmed across exchange data sources.
Ramky Infrastructure Limited Dividend Yield
The dividend yield is where the headline and the reality diverge most sharply. The "10%" figure is a face-value calculation; the yield that matters is on the price you actually pay.
| Basis | Price | Yield |
|---|---|---|
| Face value (headline) | ₹10.00 | 10.0% |
| Announcement close (27 May) | ₹463.55 | 0.22% |
| Latest close (18 Sep) | ₹321.95 | 0.31% |
Even at the depressed recent price, the Ramky Infrastructure dividend yield of 0.31% is far below typical fixed-deposit or high-yield-stock returns. This is a signalling dividend, not an income dividend.
Ramky Infrastructure Limited Dividend History Analysis
On a dividend-history basis, Ramky Infrastructure is best classified as a first-time payer rather than a consistent, cyclical or irregular one — there is simply no prior series to characterise. Across FY2014 to FY2025, the company's dividend payout ratio was 0% in every single year, even in FY2023 when a large one-off pushed reported profit above ₹1,100 Cr.
That history is not a sign of stinginess so much as necessity: through most of this period the company was servicing heavy debt and had limited distributable surplus. The FY26 dividend is the first data point in what may — or may not — become a track record. There are no special dividends, dividend cuts or suspensions to report because there were no prior dividends at all.
Financial Performance Analysis – Ramky Infrastructure Limited
The operating-leverage picture tells you where FY26 profit really came from.
| Metric | FY25 | FY26 | Change |
|---|---|---|---|
| Consolidated PAT (₹ Cr) | ~202–210 | ~283 | +35% to +40% |
| EPS (₹) | 28.54 | 39.17 | +37% |
| Revenue from operations | ~₹2,045 Cr | ~flat / lower | Marginal dip |
The red flag: profit grew sharply while revenue did not. The uplift came from lower interest cost (deleveraging), better margins and a one-time ₹59.46 Cr gain on the Visakha Pharmacity stake sale — not from higher project execution. Investors should separate recurring profit from one-off gains when judging earnings quality.
Cash Flow Analysis – Ramky Infrastructure Limited
Reported profit is an opinion; cash is a fact — so the key question is whether the dividend is funded by real cash. Here the answer is clearly yes. FY25 operating cash flow was about ₹373 Cr against a dividend outflow of only ₹6.92 Cr, giving operating-cash coverage of roughly 54 times. With minimal capital expenditure, free cash flow covers the payout a similar number of times.
The dividend is therefore funded from current operating cash generation, not from borrowings or asset sales. Receivables discipline has improved as well — debtor days fell from triple digits a few years ago to the high-60s — which supports the quality of that operating cash. On cash grounds, this is one of the most comfortably funded dividends an investor will encounter.
Balance Sheet Strength – Ramky Infrastructure Limited
Deleveraging
Borrowings fell from about ₹3,240 Cr (FY14) to ₹570 Cr (FY25) — an 82% reduction — with management calling the company effectively debt-free by late 2025. Net worth has rebuilt to roughly ₹1,900–2,050 Cr, with a book value near ₹297 per share.
What It Means for the Dividend
A repaired balance sheet is precisely what makes a maiden dividend possible. With interest costs down sharply and reserves rebuilt, the company can pay without compromising its ability to fund equity commitments on new projects. The ₹6.92 Cr outflow is immaterial against this base.
Ramky Infrastructure Limited Dividend Sustainability
Applying a four-test sustainability scorecard to the Ramky Infrastructure dividend:
| Test | Reading | Result |
|---|---|---|
| Earnings coverage | EPS ₹39.17 vs DPS ₹1 = 39x | Pass |
| Operating-cash coverage | OCF ₹373 Cr vs ₹6.92 Cr = 54x | Pass |
| Free-cash coverage | ~52x | Pass |
| Liquidity / debt position | Effectively debt-free | Pass |
Verdict: Highly Sustainable. The payout is so small relative to earnings and cash that there is no realistic affordability risk. The only caveat is that FY26 profit was flattered by a one-time gain; the size of any future dividend will depend on recurring earnings, but the current dividend is comfortably covered many times over.
Peer Comparison – Ramky Infrastructure Limited
Against mid-cap construction and infrastructure peers, Ramky's dividend yield sits at the very bottom — because it is a first-time, token payout.
| Company | Dividend Yield | Payout Character |
|---|---|---|
| Ramky Infrastructure | ~0.31% | Maiden / token |
| NCC Ltd | ~0.9%–1.5% | Regular payer |
| KNR Constructions | ~0.2%–0.4% | Low payer |
| Afcons / Larger EPC | Varies | Policy-driven |
Peer yields are approximate and move with price; shown for directional context only. The construction/EPC sector is generally low-yield because capital is reinvested into order-book execution.
Promoter Impact Analysis – Ramky Infrastructure Limited
Promoters hold 69.81% of Ramky Infrastructure. Of the total ₹6.92 Cr dividend outflow, roughly ₹4.83 Cr flows to the promoter group and about ₹2.09 Cr to public and institutional shareholders (FII ~1.9%, DII ~0.9%, retail ~28%).
One governance point worth noting for context: around 25.70% of the promoter holding is pledged. This is disclosed, publicly available information. A dividend of this size does not materially change the promoter cash position, so it is better read as an alignment signal than as a vehicle for promoter cash extraction — the amounts involved are small for all shareholder classes.
Taxation Analysis – Ramky Infrastructure Limited Dividend
Under current Indian rules, dividends are taxable in the hands of the shareholder at their applicable income-tax slab rate. The company deducts TDS at 10% on dividend paid to a resident shareholder only where total dividend from that company exceeds ₹5,000 in a financial year (TDS is 20% where PAN is not furnished).
Worked Example (Ramky ₹1/share)
An investor holding 1,000 shares receives a gross dividend of ₹1,000. As this is below the ₹5,000 threshold, no TDS is deducted. At a 30% slab the tax is ₹300, leaving a net dividend of ₹700 — an effective post-tax yield near 0.22% on a ₹321.95 price.
Illustrative Example (₹10/share, larger holding)
For scale: on a ₹10/share dividend on 1,000 shares, gross is ₹10,000; TDS at 10% (₹1,000) applies as it exceeds ₹5,000; tax at a 30% slab is ₹3,000; net in hand is ₹7,000. This is general information, not tax advice; consult a qualified advisor for your situation.
Key Risks – Ramky Infrastructure Limited
- Earnings-quality risk: FY26 profit was aided by a one-time ₹59.46 Cr stake-sale gain; recurring profit is lower than the headline suggests.
- Flat revenue: revenue from operations was broadly flat-to-lower in FY26, so growth depends on converting the order book into executed, billed work.
- Promoter pledge: about 25.70% of promoter holding is pledged, a governance factor to monitor.
- Execution & working-capital risk: as an EPC/infra player, delays, receivable stretch and project concentration can pressure cash flows.
- Negligible income appeal: at a 0.31% yield, the dividend offers almost no income; the investment case rests on growth and re-rating, not payout.
What To Monitor – Ramky Infrastructure Limited
- Recurring vs one-off profit: whether FY27 earnings sustain without exceptional gains.
- Order-book execution: revenue conversion from the ₹13,000+ crore order book and margin trajectory.
- Future dividend policy: whether the board formalises a payout policy or raises the dividend — currently undisclosed.
- Promoter pledge trend: any change in the 25.70% pledged promoter stake.
- Working capital & debtor days: continuation of the improving receivables trend that supports operating cash.
Conclusion – Should You Consider Ramky Infrastructure Limited for Dividend Income?
The Ramky Infrastructure dividend is historically significant — the company's first-ever payout after more than a decade of nil dividends — but financially modest. The ₹1 per share works out to a real yield of just 0.31%, costs the company only ₹6.92 Cr, and is covered by earnings and cash flow dozens of times over.
Positives: a maiden dividend signalling balance-sheet confidence, 82% debt reduction, a large order book, and an extremely well-covered payout. Negatives: near-zero income yield, flat revenue, a one-time gain flattering FY26 profit, and a pledged promoter stake. For pure dividend-income seekers, this is not an income stock. For those tracking the turnaround story, the dividend is best read as a confidence signal. The information here is factual and analytical — the investment decision is yours.
Frequently Asked Questions About Ramky Infrastructure Limited Dividend
What dividend has Ramky Infrastructure announced?
What is the Ramky Infrastructure dividend yield?
What is the record date for the Ramky Infrastructure dividend?
What is the ex-dividend date for Ramky Infrastructure?
When will the Ramky Infrastructure dividend be paid?
Who was eligible for the Ramky Infrastructure dividend?
How is the Ramky Infrastructure dividend taxed?
Is the Ramky Infrastructure dividend sustainable?
What is Ramky Infrastructure's dividend history?
Why is the dividend called 10% if the yield is only 0.31%?
How much of the dividend goes to promoters?
What should investors monitor after this dividend?
Disclaimer
This article is for informational and educational purposes only and does not constitute investment, tax or legal advice, or any recommendation to buy, sell or hold securities. ShareBazaar Online is not a SEBI-registered investment adviser. All figures are drawn from publicly available company filings and third-party market-data sources and may contain errors or become outdated; market prices and computed yields change continuously. Dividend approval, record date and payment are subject to the company's disclosures and applicable regulations. Taxation depends on individual circumstances — consult a qualified financial or tax advisor before making any decision. Investments in securities are subject to market risks; read all related documents carefully.