
Dividend Snapshot – Bombay Metrics Supply Chain Limited
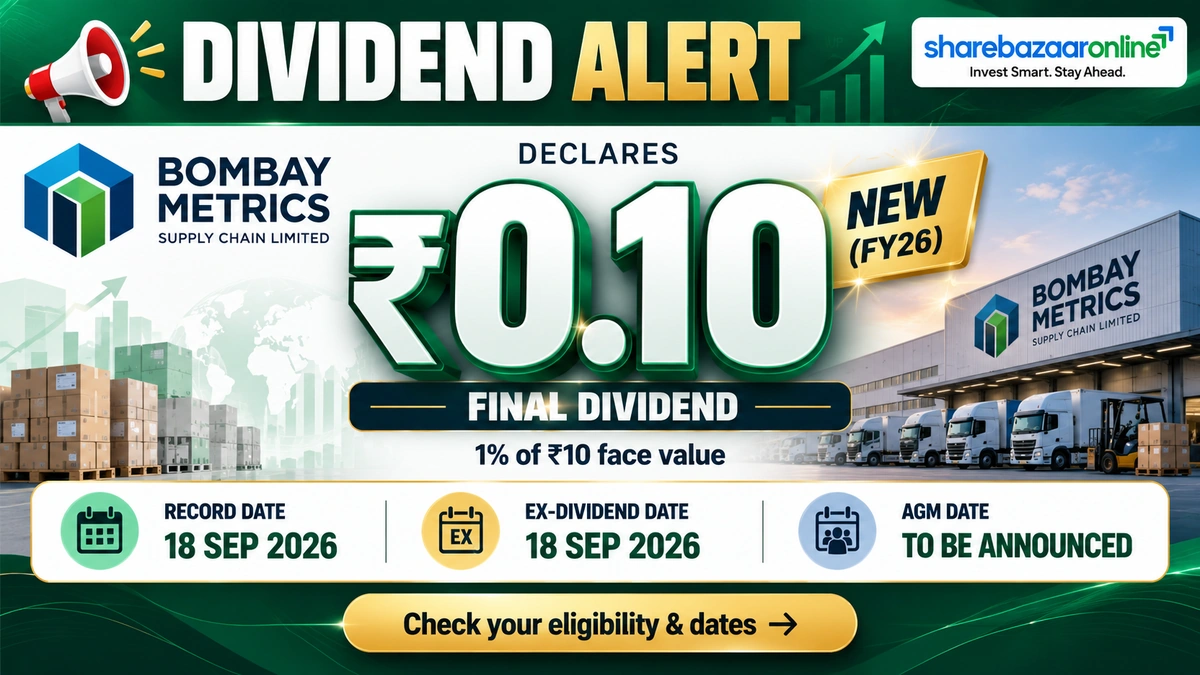
Bombay Metrics Supply Chain Limited (NSE: BMETRICS) has declared a final dividend of ₹0.10 per equity share for FY26, equal to 1% of the ₹10 face value. That headline percentage is where most retail investors are misled. On the market price of ₹35 (09 Oct 2026), the real dividend yield is just 0.29% — and even at the 52-week low of ₹31.05 it reaches only 0.32%. The payout is also half of last year’s ₹0.20, tracking a 63% fall in FY26 net profit. This is a token distribution, not an income opportunity.
| Dividend Type | Final Dividend (FY26) |
| Dividend Per Share | ₹0.10 |
| Dividend % | 1% of ₹10 face value |
| Real Yield (CMP ₹35) | 0.29% |
| Record Date | 18 Sep 2026 |
| NSE Symbol | BMETRICS |
| ISIN | INE0I3Y01014 |
| Total Outflow | ₹12.31 lakh |
| Payout Ratio | 7.44% of PAT |
| AGM Date | 25 Sep 2026 |
Company Overview – Bombay Metrics Supply Chain Limited
Bombay Metrics Supply Chain Limited is a Mumbai-headquartered company incorporated in 2015 and listed on the NSE. The business operates in the trading of engineering tools and components and provides supply chain management services, and is described as an official resale partner of MESH in the Asia-Pacific region. It is a micro-cap with a market capitalisation of about ₹43 crore (09 Oct 2026). The company is majority promoter-owned at 70.13%, with no reported FII or DII holding — the remaining 29.87% sits entirely with public shareholders. This is a thinly-held, promoter-driven trading enterprise rather than an institutionally tracked dividend play, which shapes how its distribution should be read.
Bombay Metrics Supply Chain Financial Analysis
FY26 was a difficult year for Bombay Metrics Supply Chain. Consolidated revenue slipped 8.7% to ₹92.63 crore, but the profit damage ran far deeper: EBITDA fell 46% to ₹4.57 crore and net profit dropped 63% to ₹1.65 crore. The EBITDA margin compressed from 8.31% to 4.88%. A modest revenue dip producing a profit collapse is the signature of operating deleverage — in a low-margin trading model, small cost pressures swing profits violently. Basic EPS fell from ₹3.66 to ₹1.34. The ₹0.10 dividend must be judged against this sharply weaker earnings base, not the stronger FY25 picture.
Bombay Metrics Supply Chain Dividend History Table
| Financial Year | Type | DPS (Nominal) | % of Face Value | Record Date |
|---|---|---|---|---|
| FY22 | Final | ₹0.80 | 8.0% | 19 Aug 2022 |
| FY23 | Final | ₹0.40 | 4.0% | 18 Aug 2023 |
| FY24 | Final | ₹0.45 | 4.5% | 30 Aug 2024 |
| FY25 | Final | ₹0.20 | 2.0% | 18 Sep 2025 |
| FY26 | Final | ₹0.10 | 1.0% | 18 Sep 2026 |
Nominal figures are not bonus-adjusted. A 1:1 bonus (record date around 30 Aug 2024) doubled the share count, so pre-bonus payouts halve when restated to the current base. Source: exchange filings and public dividend records.
Expert Commentary on Bombay Metrics Supply Chain Dividend
The honest read on this payout is that it is a symbolic gesture, not a shareholder-reward event. In rupee terms the company is distributing roughly ₹12.31 lakh — a sum so small it is almost immaterial to the balance sheet. The more meaningful signal is what the dividend cut says: management halved the payout as FY26 profit fell 63%, which is a disciplined, earnings-linked decision rather than a defence of a payout the business could not fund. Management attributes the weaker year to geopolitical uncertainty, shifting tariff structures and higher energy costs that squeezed trade flows and export demand (as disclosed). For income seekers, a 0.29% yield offers essentially nothing; the interest here is operational recovery, not distribution.
Bombay Metrics Supply Chain Dividend Outlook
The future dividend trajectory of Bombay Metrics Supply Chain is tied directly to margin recovery. The company has not disclosed any forward dividend guidance, so any outlook is inference from the pattern, not a forecast. The nominal payout has fallen every year since FY22 (₹0.80 → ₹0.10), and the FY26 cut followed the profit decline almost mechanically. If margins stabilise and earnings rebound, the token dividend has ample room to be maintained or restored, given it consumes under 8% of profit. If operating pressures persist, even this small payout signals caution. Investors should treat the dividend as a trailing indicator of profitability rather than a reason to own the stock.
Bombay Metrics Supply Chain Dividend Announcement Summary
The Board of Bombay Metrics Supply Chain first recommended the final dividend of ₹0.10 per share on 15 May 2026, alongside its FY26 audited results. At the board meeting on 04 August 2026, it fixed the record date as Friday, 18 September 2026 for ascertaining shareholder entitlement, subject to approval at the 11th Annual General Meeting on 25 September 2026. The dividend is declared on the ₹10 face value and will be paid only after shareholders approve it at the AGM. The same board meeting also approved appointment of a new statutory auditor for a five-year term and the AGM notice — routine governance items filed under SEBI Listing Regulation 30.
Bombay Metrics Supply Chain Key Dates Timeline
| Dividend Recommended | 15 May 2026 |
| Record Date Fixed (Board) | 04 Aug 2026 |
| Ex-Dividend Date | 18 Sep 2026 |
| Record Date | 18 Sep 2026 (Fri) |
| Book Closure | 19 Sep – 25 Sep 2026 |
| AGM (VC / OAVM) | 25 Sep 2026 (Fri) |
| Payment Date | Not disclosed (statutory: within 30 days of AGM) |
Under India’s T+1 settlement, the ex-date and record date fall on the same day (18 Sep 2026). A payment date was not specified in the filing; the Companies Act requires payment within 30 days of declaration at the AGM.
Bombay Metrics Supply Chain Dividend Yield Analysis
This is the single most important number to correct. The “1% dividend” headline is calculated on the ₹10 face value, not on what you actually pay for the share. At the market price of ₹35, ₹0.10 is a real yield of only 0.29%. The gap between the two is the face-value illusion — a 1% face-value dividend looks three times larger than the 0.29% a buyer actually earns.
Real Yield Across the Price Range
| At 52-week high ₹56.90 | 0.18% |
| At CMP ₹35.00 | 0.29% |
| At 52-week low ₹31.05 | 0.32% |
Across its entire 52-week range, the real yield never exceeds 0.32%. No matter when a buyer entered over the past year, this dividend has not been an income source. For context, large-cap Indian dividend payers routinely yield 2–7%.
Bombay Metrics Supply Chain Dividend History Analysis
On the surface, the nominal dividend has fallen steadily — ₹0.80, ₹0.40, ₹0.45, ₹0.20, ₹0.10 — which looks alarming. But part of that drop is a bonus-issue artefact: a 1:1 bonus (record date around 30 Aug 2024) doubled the share count, so FY22’s ₹0.80 restates to just ₹0.40 on today’s larger base. Even after that correction, the trend is a genuine decline. The cleaner measure is total rupee outflow, which our workings put at roughly ₹12 lakh (FY22), ₹25 lakh (FY23), ₹28 lakh (FY24), ₹24.62 lakh (FY25) and ₹12.31 lakh (FY26). The FY26 outflow is half of FY25. On this record, Bombay Metrics Supply Chain is best classified an irregular, declining payer, not a consistent dividend grower.
Bombay Metrics Supply Chain Financial Performance Analysis
| Metric (Consolidated) | FY26 | FY25 | Change |
|---|---|---|---|
| Revenue (₹ Cr) | 92.63 | 101.47 | -8.7% |
| EBITDA (₹ Cr) | 4.57 | 8.53 | -46.4% |
| EBITDA Margin | 4.88% | 8.31% | -3.43pp |
| Net Profit / PAT (₹ Cr) | 1.65 | 4.50 | -63.3% |
| Basic EPS (₹) | 1.34 | 3.66 | -63.4% |
The defining feature is operating deleverage: a 9% revenue dip produced a 46% EBITDA fall and a 63% PAT fall. In a thin-margin trading business, cost inflation and lost export volume magnify through the income statement. PAT margin fell from 4.38% to 1.76%.
Bombay Metrics Supply Chain Cash Flow Analysis
Reported profit is an opinion; cash is a fact — and here the two have diverged sharply. In FY25, Bombay Metrics Supply Chain reported a healthy standalone PAT of ₹4.32 crore yet its operating cash flow was negative ₹5.27 crore. A working-capital-heavy trading model ties up cash in receivables and inventory as it grows, so paper profits did not convert to cash. The gap was bridged with debt: borrowings jumped from ₹3.16 crore to ₹11.47 crore (+263%). The practical takeaway: the FY25 dividend was funded from reserves and borrowings, not operating cash. The FY26 cash-flow statement is not yet publicly disclosed; confirming whether cash generation has turned positive is the key integrity test for any future payout.
Bombay Metrics Supply Chain Balance Sheet Strength
The balance sheet is small and increasingly leveraged relative to its earlier debt-light history. Equity capital stands at ₹12.31 crore (1.231 crore shares of ₹10), with a book value near ₹15.5 per share. The concern is the rapid build-up of borrowings to ₹11.47 crore in FY25 from a near-zero base two years earlier, used largely to fund working capital in a growing trading book. Reported returns were strong on a trailing basis — ROE ~25% and ROCE ~29% — but these were earned before the FY26 profit collapse; on FY26 earnings, implied ROE falls to roughly 8% (editorial estimate). Against the ₹12.31 lakh dividend, affordability is never the issue; the leverage trend is.
Bombay Metrics Supply Chain Dividend Sustainability Analysis
Four-Test Scorecard
| Earnings coverage (13.4x) | Strong |
| Operating cash flow (FY25 negative) | Weak |
| Free cash flow (capex + WC heavy) | Weak |
| Outflow size (₹12.31 lakh) | Trivial |
Verdict: Sustainable by quantum, questionable by quality. The payout is so small (under 8% of profit, 13.4x covered by EPS) that the company can easily keep paying it. But the dividend has not been backed by operating cash — FY25 cash flow was negative. The ₹0.10 is an affordable token, not a payout anchored in free cash generation.
Bombay Metrics Supply Chain Peer Comparison
Clean, like-for-like peer dividend data for small NSE-listed engineering-tools traders is not reliably available in public sources, so specific competitor yields are not stated here to avoid fabricated figures. What can be said structurally: micro-cap trading and distribution companies typically pay little or no dividend, reinvesting into working capital, and where they do pay, real yields are usually well under 0.5%. Bombay Metrics Supply Chain’s 0.29% yield sits within that low band. By contrast, dedicated dividend-yield stocks in India — PSUs, utilities and mature FMCG names — commonly yield 2% to 7%. On yield alone, BMETRICS is not comparable to income-oriented large caps; its trailing ROE/ROCE (~25% / ~29%) were its stronger relative metric, though both pre-date the FY26 earnings fall.
Bombay Metrics Supply Chain Promoter Impact Analysis
With promoters holding 70.13%, the lion’s share of the dividend flows back to them. Of the total ₹12.31 lakh outflow, promoters receive about ₹8.63 lakh, while the entire public float of 29.87% shares just ₹3.68 lakh. This is a normal consequence of a concentrated holding structure, not a governance flag in itself — dividends are paid pro-rata to all shareholders at the same per-share rate. For a retail holder of, say, 1,000 shares, the FY26 dividend is a literal ₹100. The distribution is too small to be a meaningful promoter cash-extraction route, reinforcing the reading that this is a symbolic payout rather than a capital-return strategy.
Bombay Metrics Supply Chain Dividend Taxation Analysis
Since FY21, dividends are taxed in the hands of the shareholder at their applicable income-tax slab rate; there is no separate dividend distribution tax. TDS under Section 194 applies at 10% only if total dividend from a company exceeds ₹10,000 in a financial year (the threshold was raised from ₹5,000 in Budget 2025); 20% applies where PAN is not provided.
Worked Example
A holder of 1,000 BMETRICS shares earns 1,000 × ₹0.10 = ₹100 gross. This is far below the ₹10,000 TDS threshold, so no TDS is deducted; it is simply added to taxable income. At a 30% slab, tax is ₹30 and net dividend is ₹70. Even a 10,000-share holder receives ₹1,000 gross — still below the TDS threshold. The protocol illustration of 1,000 shares at a ₹10 dividend (₹10,000 gross, ₹3,000 tax, ₹7,000 net at 30%) shows the mechanics at the threshold, but BMETRICS’s actual ₹0.10 rate keeps virtually all retail holders outside TDS entirely.
Key Risks – Bombay Metrics Supply Chain
- Margin fragility: a 9% revenue dip caused a 63% profit fall — the thin-margin trading model amplifies any cost or demand shock.
- Cash conversion: FY25 operating cash flow was negative ₹5.27 crore despite positive profit; growth has not been self-funding.
- Rising leverage: borrowings surged to ₹11.47 crore (from ₹3.16 crore), increasing interest sensitivity for a small company.
- External dependence: management cites geopolitics, tariffs and energy costs hitting export demand — factors outside its control.
- Micro-cap liquidity: a ~₹43 crore market cap with no institutional holding means thin trading volumes and higher price volatility.
What To Monitor – Bombay Metrics Supply Chain
- EBITDA margin recovery: whether the margin can climb back from 4.88% toward its 8%+ FY25 level.
- Operating cash flow: the FY26 cash-flow statement — does cash generation turn positive and match reported profit?
- Debt trajectory: whether borrowings stabilise or keep rising to fund working capital.
- Revenue mix and exports: recovery in the export demand management flagged as weak.
- Dividend continuity: whether the next payout is held, cut further, or restored as an earnings-recovery signal.
Conclusion – Bombay Metrics Supply Chain Dividend FY26
The FY26 final dividend from Bombay Metrics Supply Chain is best understood as a token, earnings-linked gesture. The “1%” headline shrinks to a 0.29% real yield on the market price, and the payout was halved as net profit fell 63%. On the positive side, the dividend is trivially affordable (13.4x covered by earnings), the cut shows disciplined capital allocation, and trailing returns were historically strong. On the negative side, operating cash flow was recently negative, debt has risen sharply, and margins have compressed severely. For income investors, this dividend offers nothing material; the real story for shareholders is whether FY26’s profit slump reverses. We present the facts, positives, negatives and monitoring points — the decision is yours.
Frequently Asked Questions
What dividend has Bombay Metrics Supply Chain announced for FY26?
What is the real dividend yield of BMETRICS?
What is the record date for the Bombay Metrics Supply Chain dividend?
What is the ex-dividend date for BMETRICS?
When will the Bombay Metrics Supply Chain dividend be paid?
Who was eligible for the BMETRICS dividend?
How is the Bombay Metrics Supply Chain dividend taxed?
Is the Bombay Metrics Supply Chain dividend sustainable?
What is the dividend history of BMETRICS?
Why did Bombay Metrics Supply Chain cut its dividend?
What should investors monitor in Bombay Metrics Supply Chain?
What is the total dividend outflow and promoter share?
Does BMETRICS have any FII or DII holding?
Disclaimer
This article is for informational and educational purposes only and does not constitute investment, legal or tax advice, or any buy/sell/hold recommendation. ShareBazaar Online is not a SEBI-registered investment adviser. Dividend figures, dates and corporate-action details are based on company exchange filings; market prices, financial ratios and historical data are sourced from publicly available platforms and are subject to change — readers should verify against official NSE/BSE and company disclosures. Certain figures (including the FY26 cash-flow statement, exact payment date and bonus-adjusted history) were not disclosed by the company at the time of writing and are marked accordingly or shown as editorial estimates. Investments in securities, especially micro-cap stocks, carry market risk, including possible loss of capital. Please consult a qualified financial adviser before making any investment decision.