
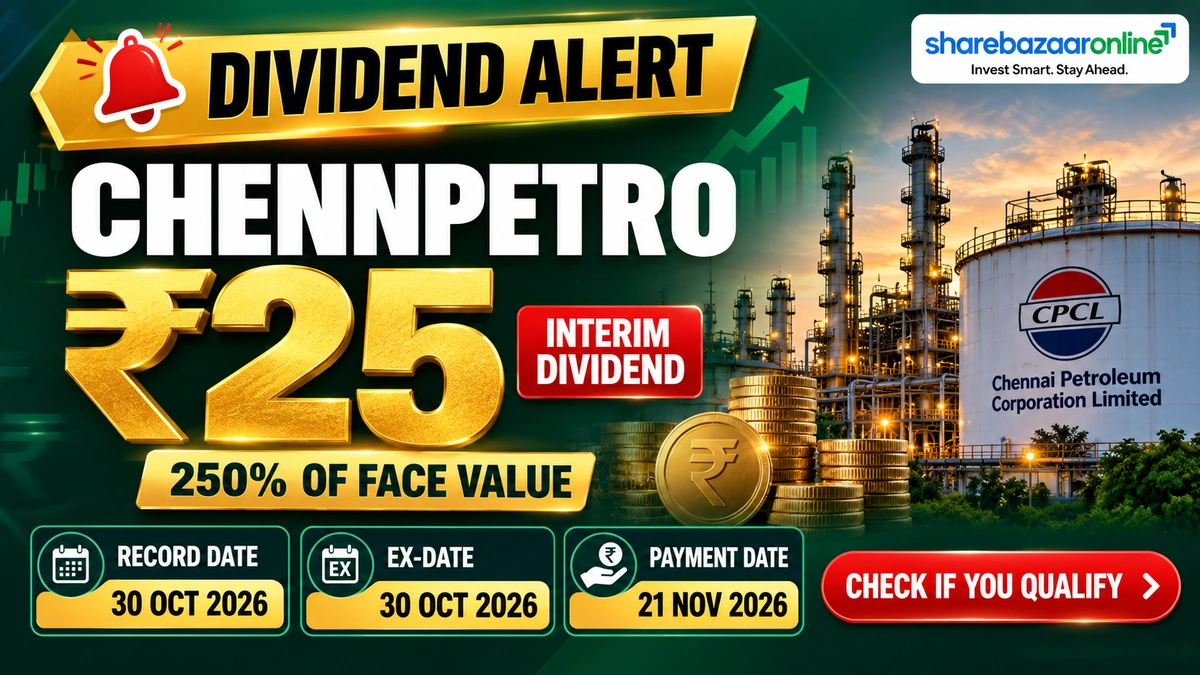
Dividend Snapshot – Chennai Petroleum Corporation Limited
Chennai Petroleum Corporation Limited (NSE: CHENNPETRO, BSE: 500110) has declared an interim dividend of ₹25 per equity share for FY2026-27, on a face value of ₹10 — a headline 250% payout. The Board approved it on 22 October 2026 alongside strong Q2 results, and fixed 30 October 2026 as the record date. While 250% sounds large, the real yield on the current market price of about ₹1,454.55 works out to roughly 1.72%. The total Chennai Petroleum dividend outflow is around ₹372 crore, comfortably covered by half-year earnings but landing when the company’s cash balance had fallen to just ₹0.28 crore.
Interim Dividend
₹25 per share
Face value ₹10 · 250% · FY2026-27
Approx. Dividend Yield (on CMP)
~1.72%
On CMP ₹1,454.55 (latest available)
Record Date
30 Oct 2026
Ex-date 30 Oct 2026 (inferred, T+1)
Payment By
21 Nov 2026
Outflow ~₹372 crore
Company Overview – Chennai Petroleum Corporation Limited
Chennai Petroleum Corporation Limited (CPCL), formerly Madras Refineries, is a Government of India enterprise and a group company of Indian Oil Corporation (IOCL). It refines crude oil into fuels and petrochemical feedstocks and makes lubricating-oil additives, operating mainly from its Manali refinery near Chennai with a second unit in the Cauvery Basin. As a single-segment refiner, CPCL’s profits swing with gross refining margins (GRM), making it a classic cyclical. The company reports on a one-segment basis and is majority-owned by IOCL, which anchors both crude supply and product off-take. Understanding this cyclicality is central to reading any Chennai Petroleum dividend, because payouts tend to rise and fall with the refining cycle rather than follow a smooth annual path.
Financial Analysis – Chennai Petroleum Corporation Limited
CPCL’s Q2 FY27 (quarter ended 30 September 2026) was exceptionally strong. Standalone net profit was ₹2,271.29 crore on revenue of ₹22,055.45 crore, with quarterly EPS of ₹152.53. For the half year, profit reached ₹3,287.96 crore (EPS ₹220.80) on revenue of ₹51,414.20 crore, up about 32.8% year on year. The driver was a sharp GRM recovery — reported at US$14.34 per barrel for April to September 2026 versus US$6.17 a year earlier, with Q2 GRM of US$20.41 (including an inventory gain of US$3.82). Profit-before-tax jumped roughly 381% on the half-year, a textbook example of refining operating leverage flowing straight to the bottom line.
Chennai Petroleum Corporation Limited Dividend History
Chennai Petroleum dividend history shows a strongly cyclical, earnings-linked pattern — generous in refining up-cycles, thin or nil in down years.
| Financial Year | Dividend / Share | Type | Percent of Face Value |
|---|---|---|---|
| FY2026-27 (interim) | ₹25.00 | Interim | 250% |
| FY2025-26 | ₹62.00 (₹8 interim + ₹54 final) | Interim + Final | 620% |
| FY2024-25 | ₹5.00 | Final | 50% |
| FY2023-24 | ₹55.00 | Final | 550% |
| FY2022-23 | ₹27.00 | Final | 270% |
| FY2021-22 | ₹2.00 | Final | 20% |
| FY2018-19 to FY2020-21 | Nil | — | 0% |
History compiled from exchange filings and market data sources; figures are per share at ₹10 face value.
Expert Commentary on Chennai Petroleum Corporation Limited Dividend
The headline number invites a reality check. A 250% dividend is calculated on the ₹10 face value, not the share price — so the real Chennai Petroleum dividend yield on a market price near ₹1,454.55 is only about 1.72%. Two forensic points stand out from the filing. First, despite half-year profit of ₹3,287.96 crore, operating cash flow was just ₹24.86 crore, as a ₹4,093 crore working-capital build (trade receivables ballooning to ₹2,007.57 crore) absorbed the earnings. Second, the company’s cash balance stood at ₹0.28 crore at 30 September 2026. The dividend is backed by profits, but not by idle cash — a distinction most wire coverage misses.
Chennai Petroleum Corporation Limited Dividend Outlook
The outlook for future Chennai Petroleum dividends hinges on one variable above all: gross refining margins. FY2026-27 has opened with GRMs far above the prior year, which is what funds a generous interim. But the recent past is a caution — FY2024-25 profit collapsed to around ₹208 crore and the dividend fell to just ₹5, before margins recovered. Investors should treat any single year’s payout as cycle-dependent rather than a run-rate. A large refinery expansion (the Cauvery Basin project) also implies rising capital commitments that compete with cash for dividends. The company has made no forward dividend commitment beyond this interim, so future payouts remain tied to realised margins and cash generation.
Chennai Petroleum Corporation Limited Dividend Announcement Summary
At its meeting on 22 October 2026, the Board of Chennai Petroleum Corporation Limited declared an interim dividend of ₹25 per equity share of face value ₹10 for the financial year 2026-27, under Regulation 30 of SEBI (LODR). Pursuant to Regulation 42, the Board fixed Friday, 30 October 2026 as the record date to determine shareholder eligibility. The interim dividend is to be paid to eligible shareholders on or before 21 November 2026. Being an interim dividend declared by the Board, it does not require separate shareholder approval at the AGM. The declaration accompanied audited Q2 and half-year results that carried an unmodified audit opinion.
Chennai Petroleum Corporation Limited Dividend Key Dates Timeline
Board / Announcement Date
22 October 2026
Record Date
30 October 2026 (Friday)
Ex-Dividend Date
30 October 2026 (inferred, T+1)
Payment Date
On or before 21 November 2026
Under India’s T+1 settlement, the ex-date and record date typically fall on the same day, so shares must be bought on or before the trading day prior to the record date to qualify. The ex-date above is inferred and should be confirmed against the official NSE/BSE corporate-action circular.
Chennai Petroleum Corporation Limited Dividend Yield Analysis
The gap between the headline and reality is the key insight. The 250% figure refers to ₹25 on a ₹10 face value. On the current market price of about ₹1,454.55, this single interim yields just ~1.72%. Viewed on a trailing basis, CPCL paid ₹62 across FY2025-26, which would equate to roughly 4.26% at today’s price — but that included an unusually large ₹54 final. The realistic forward yield depends entirely on how large the FY27 final dividend turns out to be, which in turn depends on refining margins. The announcement-date closing price (22 October 2026) was not publicly available at the time of writing and should be confirmed by the desk to compute the exact announcement-date yield.
Chennai Petroleum Corporation Limited Dividend History Analysis
On consistency, CPCL is best described as a cyclical payer, not a steady compounder. The record swings from nil dividends in the loss years of FY2019 to FY2021, to ₹55 in the FY2024 up-cycle, back down to ₹5 in FY2025, then up to ₹62 in FY2026. There have been outright suspensions during downturns and sharp cuts between good and bad years. This is normal for a standalone refiner whose earnings mirror GRMs. For income-focused readers, the practical takeaway is that Chennai Petroleum dividends should be expected to fluctuate widely year to year, and the current ₹25 interim should not be annualised into a stable expectation.
Chennai Petroleum Corporation Limited Financial Performance Analysis
The operating leverage is striking. Half-year revenue rose about 32.8% to ₹51,414.20 crore, but profit-before-tax surged roughly 381% to ₹4,397.13 crore — because refining profit is driven by the spread (GRM), not volume. In fact crude throughput actually fell to 5.438 MMT from 5.994 MMT a year earlier, so the entire profit jump came from wider margins, not more processing. Two items flattered the numbers: a one-time retrospective price revision adding ₹385.21 crore of revenue in Q1, and an inventory gain of US$3.82 per barrel embedded in Q2 GRM. Stripping these out, underlying margin strength is real but less extreme than the headline suggests.
Chennai Petroleum Corporation Limited Cash Flow Analysis
This is the most important section. Reported profit is an accounting result; cash is fact. For the half year, CPCL generated operating profit before working-capital changes of ₹4,747.27 crore — but after a ₹4,093.32 crore working-capital outflow, net operating cash flow was only ₹24.86 crore. Trade receivables jumped roughly 754% to ₹2,007.57 crore, while trade payables fell about 71%. After capex of ₹238.12 crore, free cash flow for the half was negative ₹213 crore. In short, the ₹372 crore interim dividend is backed by earnings, not by cash already in hand — it will be funded from Q3 collections and short-term borrowings.
Chennai Petroleum Corporation Limited Balance Sheet Strength
On leverage, CPCL remains conservatively geared: total borrowings of about ₹2,193 crore against equity of ₹13,293 crore give a debt-to-equity of just 0.16, with a healthy current ratio of 3.28. The concern is not solvency but liquidity timing. Cash and equivalents had dropped to ₹0.28 crore (from ₹905 crore in March 2026), with current investments of ₹159.43 crore. Net debt is roughly ₹2,034 crore. The balance sheet can clearly support the dividend over a full cycle, but the near-zero cash position at period end means the interim depends on incoming operating cash rather than an existing reserve — a point worth watching into Q3.
Chennai Petroleum Corporation Limited Dividend Sustainability
A four-test scorecard on the ₹25 interim (outflow ~₹372 crore):
| Test | Reading | Verdict |
|---|---|---|
| Earnings coverage | EPS ₹220.80 (H1) vs ₹25 = 8.8x | Strong |
| Payout ratio | ~11% of H1 profit | Comfortable |
| H1 free cash flow cover | FCF negative ₹213 cr | Weak |
| Liquidity / cash cover | Liquid ₹159.7 cr = 0.43x | Below 1x |
Overall verdict: Conditionally Sustainable. Earnings cover is ample, but the payout leans on future cash collection rather than existing reserves, and both margins and cash are cyclical.
Chennai Petroleum Corporation Limited Peer Comparison
Against other Indian refiners, CPCL is a small-cap, high-beta play on margins — its very high EPS against a modest share price gives it one of the lowest P/E ratios in the group (around 6–7x). Peer dividend yields below are indicative trailing figures and should be verified before publication.
| Company | Profile | Indicative Trailing Yield |
|---|---|---|
| Chennai Petroleum (CPCL) | Small-cap standalone refiner | ~1.7% (this interim) |
| Bharat Petroleum (BPCL) | Integrated OMC | ~3% (indicative) |
| Hindustan Petroleum (HPCL) | Integrated OMC | ~2–3% (indicative) |
| MRPL | Standalone refiner | ~1–2% (indicative) |
CPCL’s earnings and dividends are more volatile than the integrated OMCs, which smooth refining swings with marketing margins.
Chennai Petroleum Corporation Limited Promoter Impact Analysis
Promoters hold 67.29% of CPCL — Indian Oil Corporation at 51.89% plus a foreign promoter entity at 15.40%. Of the ~₹372 crore total interim payout, promoters receive about ₹250.5 crore, of which IOCL alone collects roughly ₹193 crore. Public and institutional shareholders (32.71%) share the remaining ~₹122 crore. For a cash-generating PSU, large dividends are a routine channel to upstream cash to the government and parent. Minority investors benefit proportionally, but it is worth recognising that the bulk of every CPCL dividend flows to the IOCL group rather than to the open-market float.
Chennai Petroleum Corporation Limited Dividend Taxation Analysis
Since the Finance Act 2020, dividends are taxed in the hands of the shareholder at their applicable income-tax slab rate; there is no separate Dividend Distribution Tax. The company deducts TDS at 10% on dividends above ₹5,000 per shareholder in a financial year (20% without a valid PAN). The TDS is adjustable against final tax liability.
Worked example — investor holding 1,000 CPCL shares at ₹25: Gross dividend = ₹25,000. TDS at 10% = ₹2,500 deducted at source. At a 30% slab, total tax = ₹7,500, leaving a net, after-tax dividend of ₹17,500. The effective post-tax yield for a top-slab investor is therefore materially lower than the gross figure.
Key Risks for Chennai Petroleum Corporation Limited Shareholders
- GRM cyclicality: Profit depends almost entirely on refining margins, which can collapse quickly — FY2025 PAT fell to around ₹208 crore.
- Cash-flow conversion: H1 operating cash was just ₹24.86 crore against ₹3,288 crore profit; a sustained receivables build could strain liquidity.
- Single-segment, single-commodity exposure: No marketing or diversification cushion to offset refining downturns.
- Capex competition for cash: The Cauvery Basin expansion requires large investment that competes with dividends.
- Related-party dependence: Crude supply and product off-take are largely routed through parent IOCL, concentrating counterparty risk.
- Governance note: Auditors flagged that the Board did not have the minimum required Independent Directors, including a Woman Independent Director, during the reporting period.
What To Monitor in Chennai Petroleum Corporation Limited
- Quarterly GRM trend: Whether the US$14–20 per barrel margin holds or mean-reverts.
- Working-capital normalisation: Whether the ₹2,008 crore receivables reverse to cash in Q3 and Q4.
- Operating cash flow recovery: A return of OCF toward FY26 levels (around ₹2,945 crore full year).
- FY27 final dividend size: The real indicator of full-year payout versus this interim.
- Capex drawdown on the refinery expansion: How much cash the Cauvery Basin project absorbs.
- Board composition compliance: Resolution of the Independent Director shortfall noted by auditors.
Conclusion – Chennai Petroleum Corporation Limited Dividend
Chennai Petroleum’s ₹25 interim dividend is a genuine reward funded by a strong refining half-year, but the picture is more nuanced than the 250% headline. The real yield is modest at around 1.72%, earnings cover is comfortable at 8.8x, yet the payout is backed by profit rather than cash, with operating cash flow at just ₹24.86 crore and a period-end cash balance of ₹0.28 crore. The dividend scores as Conditionally Sustainable — dependable while margins stay high, but cyclical by nature. The positives are strong profits, low leverage and a long payout track record; the negatives are weak cash conversion, a ballooning receivables book and GRM dependence. Readers can weigh these factors against their own objectives.
Frequently Asked Questions About Chennai Petroleum Corporation Limited Dividend
What dividend has Chennai Petroleum announced?
What is the Chennai Petroleum dividend yield?
What is the record date for the Chennai Petroleum dividend?
What is the ex-dividend date for CHENNPETRO?
When will the Chennai Petroleum dividend be paid?
Who is eligible for the CHENNPETRO interim dividend?
How is the Chennai Petroleum dividend taxed?
Is the Chennai Petroleum dividend sustainable?
What is the Chennai Petroleum dividend history?
What should investors monitor after this dividend?
How much is the total Chennai Petroleum dividend outflow?
Does the CHENNPETRO interim dividend need AGM approval?
Disclaimer – Chennai Petroleum Corporation Limited Dividend Analysis
This article is for informational and educational purposes only and does not constitute investment, legal or tax advice, or any buy, sell or hold recommendation. ShareBazaar Online is not a SEBI-registered investment adviser. Dividend figures and corporate-action dates are based on the company’s exchange filings; market price, yield, peer and historical figures are drawn from public data sources and should be independently verified before any decision. Dividend yield is dynamic and changes with the share price. Taxation depends on individual circumstances — consult a qualified professional. Investments in securities are subject to market risks. Readers should conduct their own due diligence or consult a registered financial adviser before investing.