
Dividend Snapshot – Cyber Media Research & Services Limited
Dividend Details
- Company: Cyber Media Research & Services Limited
- NSE Symbol: CMRSL | BSE Code: 535482
- ISIN: INE075Z01011
- Dividend Type: Final Dividend
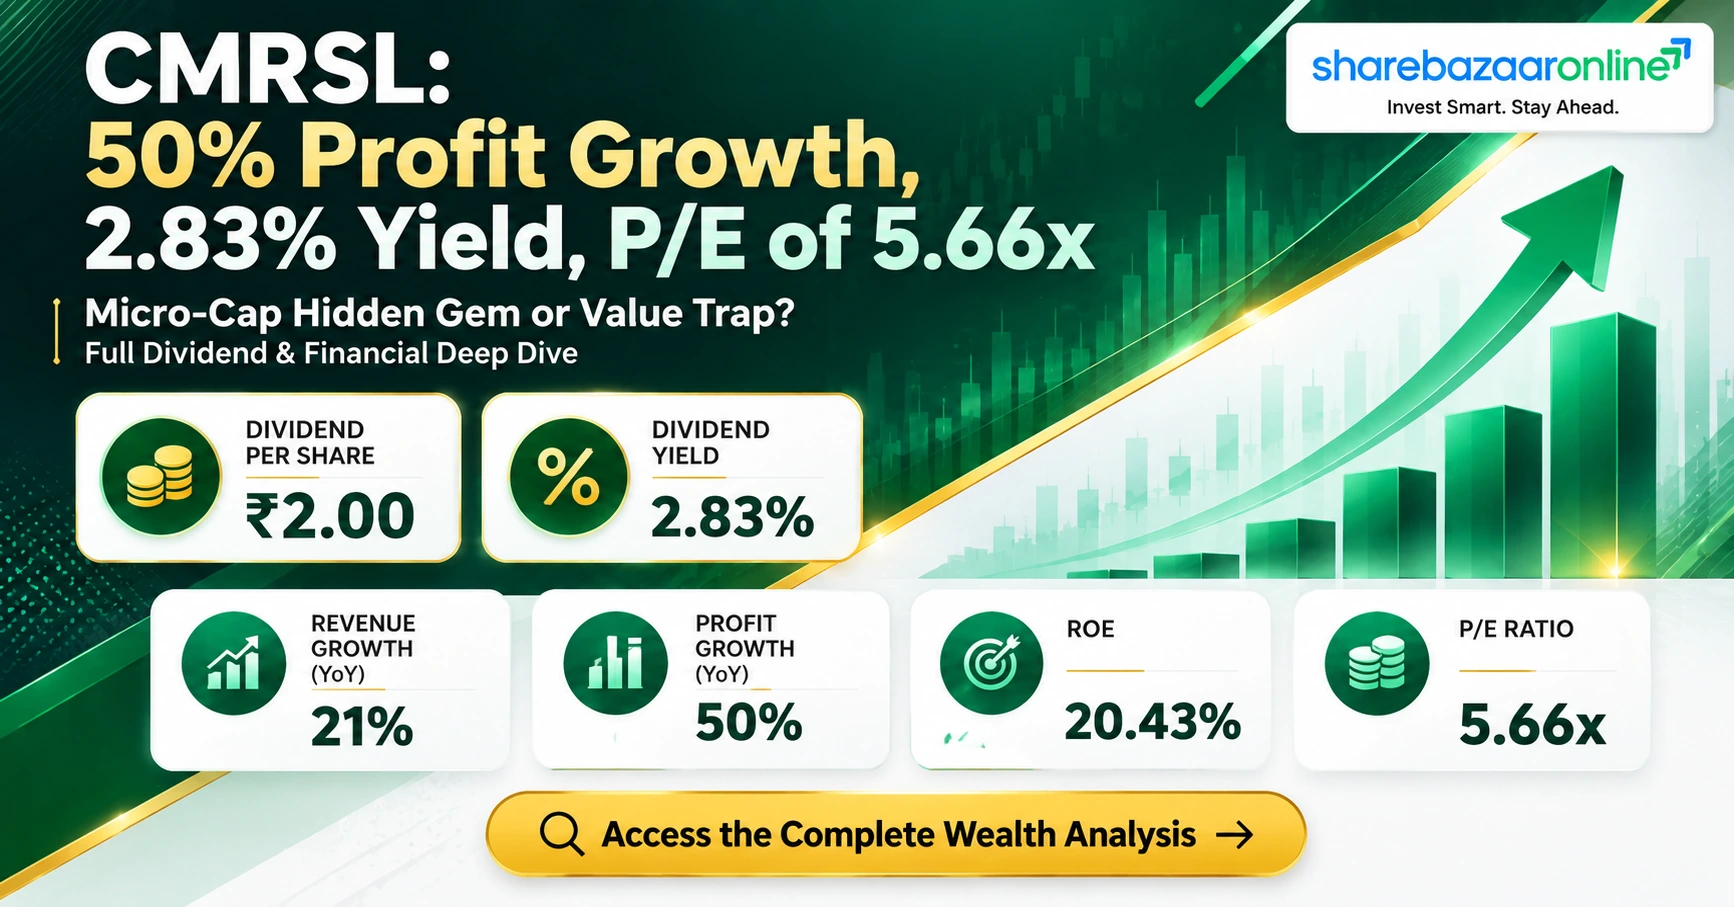
- Dividend Per Share: ₹2.00
- Dividend %: 20% (on Face Value ₹10)
- Financial Year: FY 2025-26
Market Data
- CMP: ₹70.65 (as of Sep 30, 2026)
- Market Cap: ₹20.69 Crore
- Dividend Yield: 2.83%
- Dividend Outflow: ₹0.59 Crore
- Payout Ratio: 16.84%
- Dividend Coverage: 5.95x
- 52-Week Range: ₹52.45 – ₹86.45
Cyber Media Research & Services Limited – Company Overview
Cyber Media Research & Services Limited (CMRSL) is part of the Cyber Media Group, one of India's established technology media and research houses. The company provides IT research, consulting, and advisory services to enterprises, technology vendors, and government organizations. Listed on both NSE and BSE under the Printing & Publishing sector, CMRSL operates with a market capitalization of just ₹20.69 Crore, placing it firmly in the micro-cap category. The company has 29.3 Lakh equity shares outstanding with a face value of ₹10 each. CMRSL's board has recommended a final dividend of ₹2 per share for FY 2025-26, subject to shareholder approval at the upcoming Annual General Meeting. Notably, a pending merger between CMRSL and Cyber Media (India) Limited is awaiting SEBI and stock exchange approvals.
Cyber Media Research & Services Limited – Financial Analysis
Consolidated FY26 Performance
- Revenue from Operations: ₹90.82 Crore (vs ₹75.03 Cr in FY25)
- Total Income: ₹91.60 Crore
- Profit Before Tax: ₹4.43 Crore
- Net Profit: ₹3.48 Crore (vs ₹2.32 Cr in FY25)
- EPS: ₹11.89 (vs ₹7.91 in FY25)
- Revenue Growth: +21.05% YoY
- Profit Growth: +50.24% YoY
Key Financial Ratios
- P/E Ratio: 5.66x
- P/B Ratio: 1.13x
- ROE: 20.43%
- ROCE: 22.74%
- Debt/Equity: 0.31
- Interest Coverage: 7.68x
- Current Ratio: 1.57
Key Insight: CMRSL delivered strong topline growth of 21% with profit expanding 50% on a consolidated basis. The company's ROE of 20.43% and ROCE of 22.74% are noteworthy for a micro-cap company. However, the operating profit margin remains thin at approximately 4.6%, indicating limited pricing power. The low P/E of 5.66x reflects the market's skepticism about the micro-cap's liquidity and scale rather than fundamental weakness.
Cyber Media Research & Services Limited – Dividend History
| Financial Year | Type | DPS (₹) | Dividend % | Record Date |
|---|---|---|---|---|
| FY 2025-26 | Final | ₹2.00 | 20% | 19-Aug-2026 |
| FY 2024-25 | Final | ₹2.00 | 20% | 19-Aug-2025 |
| FY 2023-24 | — | Nil | — | — |
| FY 2022-23 | — | Nil | — | — |
| FY 2021-22 | — | Nil | — | — |
Assessment: CMRSL has paid dividends for only 2 consecutive years (FY25 and FY26) after years of nil payouts. The company is classified as a recent dividend initiator rather than a consistent payer. The flat ₹2 per share payout in both years shows no dividend growth yet. Investors seeking reliable dividend income should treat this track record with caution — two years is insufficient to establish a pattern. The dividend was initiated only after profitability improved meaningfully in FY24-25.
Expert Commentary – Cyber Media Research & Services Limited Dividend
CMRSL's decision to maintain the ₹2 per share dividend for FY26 signals management's confidence in sustaining profitability. With consolidated net profit surging 50% to ₹3.48 Crore and EPS rising to ₹11.89, the company has earnings headroom to support this payout. The 16.84% payout ratio is conservative, retaining over 83% of profits for business reinvestment. However, the weak operating cash flow of just ₹0.95 Crore against ₹3.20 Crore standalone net profit is a red flag — it indicates that reported profits are not fully translating into cash. The pending merger with Cyber Media (India) Limited adds uncertainty. Investors should weigh the attractive 2.83% yield against the micro-cap liquidity risk and cash flow quality concerns.
Cyber Media Research & Services Limited – Future Outlook
CMRSL's future hinges on the outcome of its proposed merger with Cyber Media (India) Limited, which could reshape the combined entity's revenue base, cost structure, and dividend capacity. The company's IT research and advisory segment benefits from India's expanding digital economy, but CMRSL remains constrained by its micro-cap scale (₹20.69 Crore market cap) and thin margins (4.6% OPM). Revenue growth of 21% in FY26 is encouraging, but needs to be sustained over multiple years to build investor confidence. If the merger completes successfully, the combined entity could achieve better operating leverage and potentially increase dividends. However, until cash flows align with reported profits, the dividend's sustainability remains a watch point. The current ₹2 per share payout appears maintainable given the 5.95x earnings coverage.
Cyber Media Research & Services Limited – Dividend Announcement Summary
The Board of Directors of Cyber Media Research & Services Limited, in their meeting held on May 6, 2026, recommended a final dividend of ₹2 per equity share (20% on face value of ₹10) for the financial year ended March 31, 2026. This recommendation is subject to approval by shareholders at the Annual General Meeting. The record date for determining dividend eligibility has been fixed as August 19, 2026. The intimation was filed with NSE and BSE on August 3, 2026, signed by Ms. Preeti Gupta, Company Secretary & Compliance Officer. The total dividend outflow is estimated at ₹0.59 Crore (₹58.60 Lakh), representing a payout ratio of 16.84% of consolidated net profit.
Cyber Media Research & Services Limited – Key Dates Timeline
Board Approval
May 6, 2026
Exchange Intimation
August 3, 2026
AGM Approval
Pending (Date to be announced)
Ex-Dividend Date
August 19, 2026
Record Date
August 19, 2026
Payment Date
Within 30 days of AGM
Cyber Media Research & Services Limited – Dividend Yield Analysis
Yield Calculations
- Dividend Per Share: ₹2.00
- Current Market Price: ₹70.65
- Current Dividend Yield: 2.83%
- Dividend % on Face Value: 20%
Yield Reality Check
The 2.83% yield appears attractive relative to the broader market average of ~1.2%. However, this yield is partly inflated by the stock's 22.36% price decline over the past year. CMRSL fell from its 52-week high of ₹86.45 to current levels, mechanically pushing the yield higher. The yield is genuine (backed by consistent ₹2 payouts), but investors should not mistake a falling stock price for improving shareholder returns. At the 52-week high, the same ₹2 dividend would yield only 2.31%.
Cyber Media Research & Services Limited – Financial Performance Analysis
5-Year Standalone Revenue & Profit Trend (₹ Crore)
| Metric | FY22 | FY23 | FY24 | FY25 | FY26 |
|---|---|---|---|---|---|
| Revenue | 34.18 | 41.34 | 55.73 | 48.64 | 61.15 |
| Operating Profit | 3.06 | 3.71 | 4.76 | 2.18 | 4.50 |
| Net Profit | 1.28 | 1.49 | 2.62 | 1.71 | 3.20 |
| EPS (₹) | 5.33 | 5.21 | 9.06 | 6.11 | 10.98 |
Operating Leverage: FY26 revenue grew 25.7% while operating profit surged 106% and net profit jumped 87%. This positive operating leverage indicates the business is scaling efficiently with fixed costs being absorbed across a larger revenue base. However, FY25 was a weak year (revenue declined 12.7%, profit dropped 34.7%), suggesting cyclicality in CMRSL's business. The 3-year revenue CAGR of 13.9% provides a more realistic growth picture.
Cyber Media Research & Services Limited – Cash Flow Analysis
Standalone Cash Flow Trend (₹ Crore)
| Cash Flow | FY22 | FY23 | FY24 | FY25 | FY26 |
|---|---|---|---|---|---|
| Operating CF | -3.13 | 8.30 | -1.47 | 3.20 | 0.95 |
| Investing CF | 1.64 | -9.83 | 1.17 | -0.01 | 0.03 |
| Financing CF | 1.42 | 2.90 | 0.42 | -3.79 | -2.18 |
| Net Cash Flow | -0.06 | 1.37 | 0.11 | -0.61 | -1.19 |
Cash Flow Quality Assessment
Critical Finding: CMRSL's FY26 operating cash flow of ₹0.95 Crore is significantly lower than standalone net profit of ₹3.20 Crore — only 29.7% of reported profit converted to cash. This is a major red flag. The divergence suggests that profits are locked in receivables or working capital rather than available as cash. Over five years, operating cash flow has been erratic — negative in FY22 and FY24. The dividend outflow of ₹0.59 Crore represents 62% of operating cash flow, leaving minimal cash for debt repayment or business investment. Free cash flow is effectively negative in FY26, meaning the dividend is not supported by free cash generation.
Cyber Media Research & Services Limited – Balance Sheet Strength
Assets (₹ Crore)
- Total Assets: ₹41.05 Cr
- Net Fixed Assets: ₹0.50 Cr
- Current Assets: ₹30.54 Cr
- Cash & Equivalents: ₹0.80 Cr
Liabilities (₹ Crore)
- Share Capital: ₹2.93 Cr
- Reserves: ₹14.07 Cr
- Total Borrowings: ₹4.41 Cr
- Current Liabilities: ₹19.40 Cr
- Net Debt: ₹3.61 Cr
Balance Sheet Assessment: CMRSL is an asset-light business with net fixed assets of just ₹0.50 Crore. The company holds ₹4.41 Crore in debt against cash of only ₹0.80 Crore, resulting in net debt of ₹3.61 Crore. The debt-to-equity ratio of 0.31 is manageable but not negligible for a micro-cap. Cash reserves of ₹0.80 Crore provide only 1.37x coverage of the dividend outflow. The current ratio of 1.57 indicates adequate short-term liquidity, though the large current liabilities of ₹19.40 Crore relative to the balance sheet size warrant monitoring.
Cyber Media Research & Services Limited – Dividend Sustainability Analysis
Sustainability Metrics
- Payout Ratio: 16.84% ✅ Conservative
- Earnings Coverage: 5.95x ✅ Strong
- Cash Coverage: 1.37x ⚠️ Thin
- FCF Coverage: Negative ❌ Concern
- Debt Trend: ₹4.41 Cr ⚠️ Present
- Earnings Trend: Growing ✅ Positive
Verdict
Overall Classification: Moderately Sustainable
While CMRSL's earnings comfortably cover the dividend (5.95x coverage), the cash flow picture tells a different story. Operating cash flow barely covers the dividend payout, and free cash flow is negative. The company is essentially paying dividends from its balance sheet cash reserves and receivable collections rather than from true free cash flow generation. The low payout ratio of 16.84% provides a buffer, but unless cash flow quality improves, the sustainability of even this modest dividend could come under pressure if earnings dip.
Cyber Media Research & Services Limited – Peer Comparison
| Company | MCap (₹ Cr) | P/E | Div Yield (%) | ROE (%) | ROCE (%) |
|---|---|---|---|---|---|
| CMRSL | 21 | 5.37 | 3.81 | 18.54 | 20.88 |
| Axiscades Tech | 9,801 | 269.72 | 0.00 | 10.53 | 15.80 |
| Walchand PF | 37 | 8.25 | 1.15 | 11.98 | 15.70 |
| CRISIL | 32,372 | 36.61 | 1.41 | 27.51 | 37.99 |
| Inventurus Knowledge | 30,470 | 39.89 | 0.00 | 32.27 | 32.73 |
Peer Analysis: CMRSL offers the highest dividend yield (3.81%) among peers and trades at the lowest P/E (5.37x). Its ROE of 18.54% is competitive against larger peers like Axiscades (10.53%) and Walchand (11.98%), though below CRISIL (27.51%). The valuation discount is primarily driven by CMRSL's micro-cap status, low liquidity, and limited institutional interest. Revenue growth of 21.05% is the second-highest in the peer set. Source: Value Research Online.
Cyber Media Research & Services Limited – Promoter Impact Analysis
Shareholding Pattern (Jun 2026)
- Promoters: 42.42%
- FII: 0.93%
- Public & Others: 56.65%
- Promoter Pledging: 0.00%
Promoter Dividend Income
- Total Dividend Outflow: ₹0.59 Crore
- Promoter Share (42.42%): ₹0.25 Crore (₹24.86 Lakh)
- Minority Share (57.58%): ₹0.34 Crore (₹33.74 Lakh)
Distribution Assessment: Promoters receive ₹24.86 Lakh from the dividend, which is a relatively small absolute amount. With 42.42% holding, the promoter-minority split is balanced. Zero promoter pledging is a positive signal. However, the near-zero FII holding (0.93%) indicates minimal institutional validation of the stock. The dividend primarily benefits the promoter group and a concentrated set of public shareholders, as micro-cap stocks typically have limited retail investor base.
Cyber Media Research & Services Limited – Dividend Taxation Analysis
Indian Dividend Tax Rules (FY 2025-26)
Under the current Indian tax regime, dividends are taxable in the hands of shareholders at their applicable income tax slab rate. The company deducts TDS at 10% if aggregate dividend exceeds ₹5,000 in a financial year. Non-PAN shareholders face 20% TDS. NRI shareholders are subject to 20% TDS plus applicable surcharge and cess.
Worked Example: 1,000 Shares | 30% Tax Slab
| Shares Held | 1,000 |
| Dividend Per Share | ₹2.00 |
| Gross Dividend | ₹2,000 |
| Income Tax @ 30% | ₹600 |
| Health & Education Cess @ 4% | ₹24 |
| Total Tax Liability | ₹624 |
| Net Dividend Received | ₹1,376 |
| Investment Value (1,000 × ₹70.65) | ₹70,650 |
| Effective Post-Tax Yield | 1.95% |
Note: At the 30% tax slab, the effective dividend yield drops from 2.83% pre-tax to 1.95% post-tax. For investors in the 20% slab, effective yield is approximately 2.24%. TDS of 10% applies only if total dividend from CMRSL exceeds ₹5,000 in the financial year (i.e., holding more than 2,500 shares).
Cyber Media Research & Services Limited – Key Risks
- 1. Micro-Cap Liquidity Risk: With a market cap of just ₹20.69 Crore and minimal trading volume, investors face significant liquidity risk. Exiting a large position could be extremely difficult without impacting the stock price.
- 2. Cash Flow Quality Concern: Operating cash flow (₹0.95 Cr) is only 29.7% of reported net profit (₹3.20 Cr), raising questions about the quality of reported earnings and the sustainability of cash distributions.
- 3. Revenue Cyclicality: FY25 revenue declined 12.7% before rebounding in FY26, indicating the IT research business is cyclical and dependent on discretionary corporate spending.
- 4. Merger Uncertainty: The proposed merger with Cyber Media (India) Limited is pending SEBI and stock exchange approvals. The outcome could significantly alter the company's structure, financials, and dividend policy.
- 5. Thin Operating Margins: Operating profit margin of approximately 4.6% leaves minimal buffer for cost increases or revenue shortfalls. A small revenue decline can disproportionately impact profitability.
- 6. Negligible Institutional Interest: FII holding of just 0.93% suggests limited institutional due diligence and confidence in the stock's governance and growth prospects.
- 7. Stock Price Erosion: The stock has declined 22.36% over the past year and 71.19% from its all-time high, indicating persistent value destruction that far exceeds the dividend income.
Cyber Media Research & Services Limited – What To Monitor
- 1. Merger Outcome: Track SEBI and stock exchange approval status for the CMRSL–Cyber Media (India) Limited merger. Post-merger financials and dividend policy could change materially.
- 2. Operating Cash Flow Improvement: Monitor whether the gap between net profit and OCF narrows in coming quarters. Sustained cash flow weakness could threaten future dividends.
- 3. Receivables Movement: Watch trade receivables as a percentage of revenue. Rising receivables relative to revenue would explain weak cash conversion and signal collection risk.
- 4. Revenue Growth Consistency: After the FY25 dip and FY26 recovery, sustained revenue growth above 15% would validate the business trajectory. Another decline would signal cyclical vulnerability.
- 5. Promoter Holding Changes: Any promoter selling in a micro-cap with 42.42% holding would be a significant negative signal. Monitor quarterly shareholding disclosures.
- 6. Margin Expansion: Operating margin needs to improve beyond 4.6% for the business to generate meaningful free cash flow. Track employee costs and other expenses as percentage of revenue.
- 7. Debt Trajectory: With ₹4.41 Crore in borrowings and negative free cash flow, any increase in debt while maintaining dividends would be a red flag.
Conclusion – Cyber Media Research & Services Limited Dividend FY 2025-26
Cyber Media Research & Services Limited's ₹2 per share final dividend for FY 2025-26 delivers a 2.83% yield at current market price, supported by strong earnings coverage of 5.95x and a conservative payout ratio of 16.84%. The company's FY26 performance was encouraging — revenue grew 21%, net profit surged 50%, and return ratios (ROE 20.43%, ROCE 22.74%) are competitive. However, critical concerns persist: operating cash flow covered only 29.7% of reported profits, free cash flow is negative, and the stock has lost 22.36% in value over the past year — wiping out several years of dividend income. The pending merger adds uncertainty. This is a micro-cap stock with limited liquidity and minimal institutional interest. The dividend is currently sustainable from an earnings perspective but is not supported by cash flows. Investors should evaluate whether the 2.83% pre-tax yield (approximately 1.95% post-tax for 30% slab holders) adequately compensates for the liquidity, capital erosion, and business risks associated with this micro-cap stock.
Frequently Asked Questions – Cyber Media Research & Services Limited Dividend
What dividend has Cyber Media Research & Services Limited announced for FY 2025-26?
What is the current dividend yield of CMRSL?
What is the record date for CMRSL dividend?
What is the ex-dividend date for CMRSL?
When will CMRSL dividend be paid to shareholders?
Who is eligible for CMRSL dividend?
How is CMRSL dividend taxed in India?
Is CMRSL dividend sustainable?
What is CMRSL's dividend history?
What should investors monitor regarding CMRSL dividend?
What is the dividend payout ratio of CMRSL?
How does CMRSL dividend yield compare with peers?
Disclaimer
This article is published by ShareBazaar Online for informational and educational purposes only. It does not constitute investment advice, a recommendation to buy, sell, or hold any security, or an offer to transact. All data has been sourced from publicly available filings, stock exchanges, and financial databases. While every effort has been made to ensure accuracy, ShareBazaar Online does not guarantee the completeness or timeliness of the information. Past dividend payments do not guarantee future dividends. Stock investments are subject to market risks. Readers should consult a SEBI-registered financial advisor before making any investment decisions. ShareBazaar Online and its team members may or may not hold positions in the securities discussed. All financial figures are in Indian Rupees (₹) unless otherwise stated.