
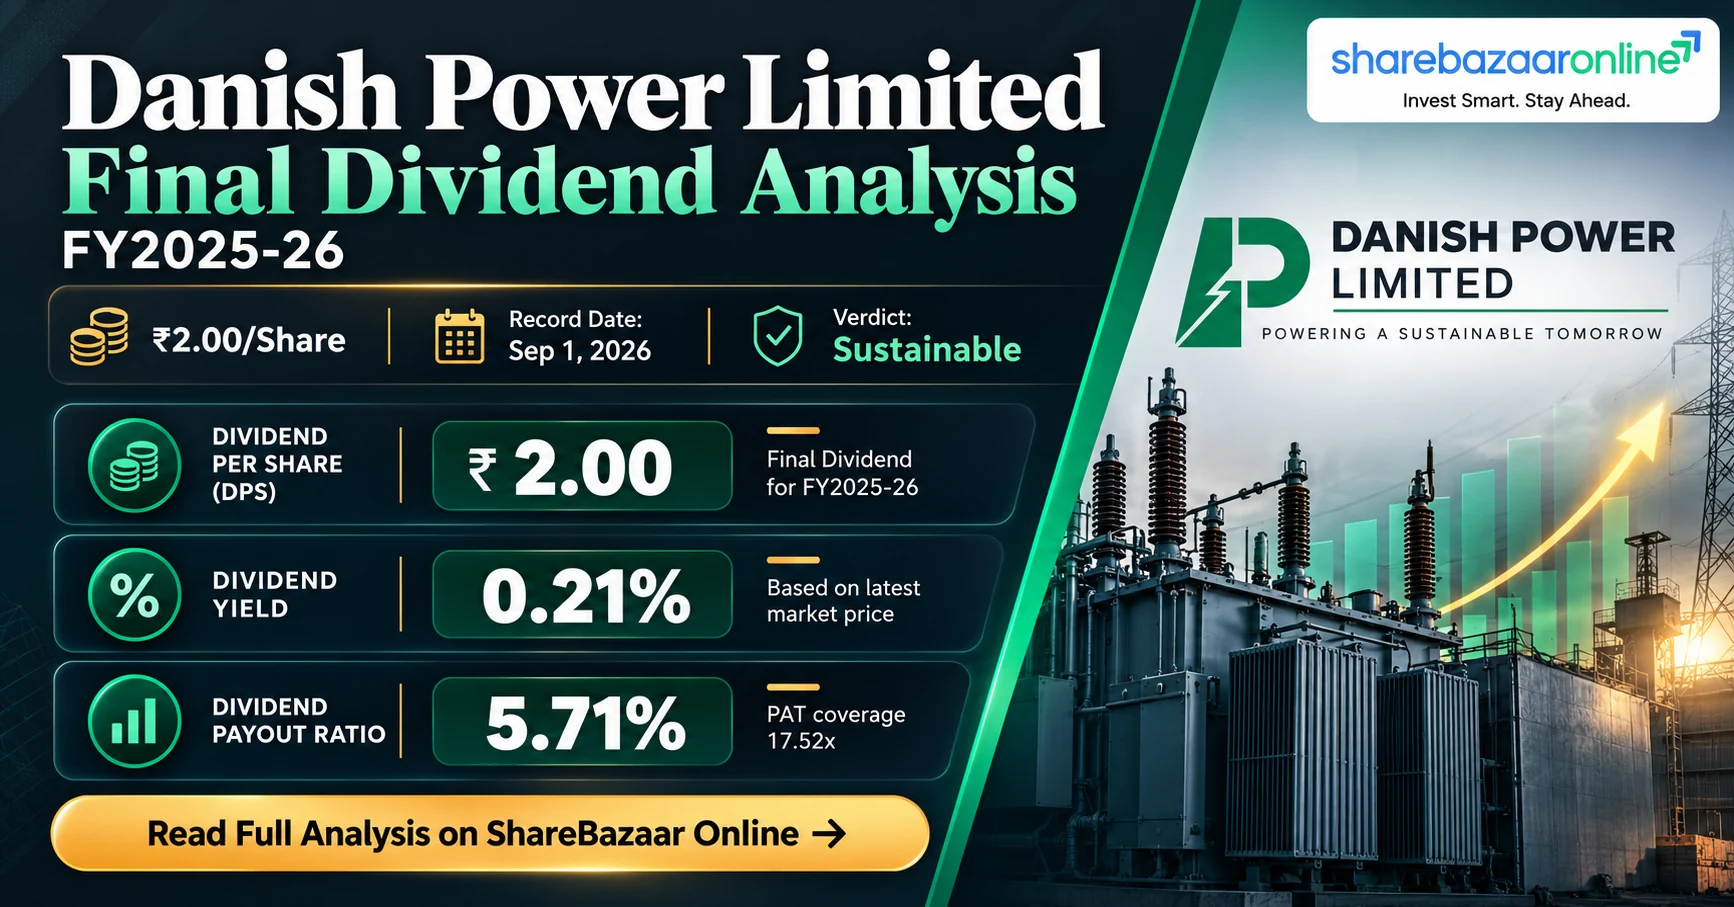
Dividend Snapshot – Danish Power Limited
Dividend Details
Company: Danish Power Limited
NSE Symbol: DANISH | BSE Code: 543974
ISIN: INE0YU901016
Dividend Type: Final Dividend (FY2025-26)
Dividend Per Share: ₹2.00 (20% on Face Value ₹10)
Record Date: September 1, 2026
Ex-Date: September 1, 2026
Payment Date: October 8, 2026
Yield & Valuation
CMP (Sep 30, 2026): ₹967.00
Market Yield: 0.21%
Announcement-Date Yield: 0.30% (CMP ₹665 on May 9, 2026)
Dividend Payout Ratio: 5.71%
Dividend Coverage: 17.52x
Total Dividend Outflow: ₹3.94 Crore
Face Value: ₹10
Face-Value Illusion Alert: The headline reads "20% dividend" — but that 20% is on a ₹10 face value. At the current market price of ₹967, the actual dividend yield is just 0.21%. Always evaluate dividends against market price, not face value.
Danish Power Limited – Company Overview
Danish Power Limited is a Vadodara-based manufacturer of power and distribution transformers, established in 2009. The company serves utilities, industrial clients and renewable energy projects across India. Listed on NSE and BSE in October 2024 via IPO, Danish Power has rapidly scaled operations with consolidated revenue reaching ₹521.45 Crore in FY2025-26 — a 22.2% year-on-year increase. The company operates in a capital-intensive sector benefiting from India's transmission and distribution infrastructure expansion. With a nearly debt-free balance sheet (D/E ~0.01) and ROE of 16.70%, Danish Power is positioned as a mid-cap growth play in the power equipment space. This is only the company's second dividend since listing.
Danish Power Limited Financial Analysis
Profitability (FY2025-26 Consolidated)
Revenue: ₹521.45 Crore (+22.2% YoY)
EBITDA: ₹99.72 Crore (+11.7% YoY)
EBITDA Margin: 19.13%
PAT: ₹68.98 Crore (+26.3% YoY)
PAT Margin: 13.23%
EPS: ₹35.03
Return Ratios & Efficiency
ROE: 16.70%
ROCE: 22.17%
Debt-to-Equity: ~0.01 (nearly debt-free)
4-Year Revenue CAGR: 36.9%
4-Year PAT CAGR: 87.4%
Market Cap: ~₹1,904 Crore
Operating Leverage
Revenue grew 22.2% while EBITDA grew only 11.7% — indicating margin compression at the operating level. However, PAT grew 26.3%, outpacing revenue, driven by lower finance costs and improved tax efficiency. EBITDA margin contracted from 20.9% (FY25) to 19.1% (FY26), likely due to rising raw material and employee costs. Investors should monitor whether operating margins stabilize as the company scales.
Expert Commentary on Danish Power Limited Dividend
Danish Power's ₹2.00 per share final dividend for FY2025-26 represents a deliberate capital allocation choice by a growth-stage company. With a payout ratio of just 5.71% and coverage of 17.52x, management is clearly prioritizing reinvestment over shareholder returns. This is appropriate for a company growing revenue at 36.9% CAGR and investing heavily in capacity expansion (₹68.35 Crore in investing outflows). The dividend increase from ₹1.50 (FY25) to ₹2.00 (FY26) — a 33% increase — signals confidence in earnings sustainability. However, the 0.21% yield makes this irrelevant for income investors. Danish Power is a growth stock that happens to pay a token dividend, not a dividend stock.
Danish Power Limited – Future Dividend Outlook
Given Danish Power's growth trajectory and low payout ratio, dividend increases are likely to remain incremental rather than transformative. With an 87.4% PAT CAGR over four years, earnings momentum is strong. If the company maintains its ~5-6% payout ratio and PAT continues growing at 20-25% annually, dividend per share could reach ₹2.50–₹3.00 by FY2027-28. However, the company's heavy capex requirements (negative FCF of ₹25.85 Crore in FY26) suggest management will continue prioritizing capacity building. Income-focused investors should not expect yield expansion unless the stock price corrects significantly or the company transitions to a mature-phase capital allocation framework.
Danish Power Limited Dividend Announcement Summary
On May 9, 2026, the Board of Directors of Danish Power Limited recommended a final dividend of ₹2.00 per equity share (20% on face value of ₹10) for the financial year 2025-26. This dividend was subject to approval at the Annual General Meeting. The total dividend outflow amounts to approximately ₹3.94 Crore on 1.969 Crore outstanding equity shares. This is the company's second dividend since its IPO listing in October 2024, representing a 33% increase over the ₹1.50 per share paid for FY2024-25. On the announcement date, the stock closed at ₹665 on NSE.
Danish Power Limited – Key Dates Timeline
May 9, 2026 — Announcement Date
Board recommended ₹2.00/share final dividend for FY2025-26. CMP: ₹665
September 1, 2026 — Record Date
Shareholders on record as of this date were eligible for the dividend
September 1, 2026 — Ex-Dividend Date
Shares traded ex-dividend from this date. Buyers from this date onward were not eligible
October 8, 2026 — Payment Date
Dividend to be credited to eligible shareholders' bank accounts
Danish Power Limited Dividend Yield Analysis
Yield Computation
Dividend Per Share: ₹2.00
Current Market Price: ₹967 (Sep 30, 2026)
Current Yield: (2.00 ÷ 967) × 100 = 0.21%
Announcement-Date CMP: ₹665 (May 9, 2026)
Announcement Yield: (2.00 ÷ 665) × 100 = 0.30%
Yield Reality Check
Danish Power's 0.21% yield is among the lowest in the power equipment sector. The headline "20% dividend" is calculated on a ₹10 face value — a metric that has no relevance to actual investor returns. The stock has appreciated ~45% since announcement (₹665 → ₹967), meaning capital gains have far outweighed dividend income. This is clearly a growth stock where dividend income is a negligible component of total shareholder returns. A savings bank account at 3-4% delivers 15-19x more income per rupee invested.
Danish Power Limited Dividend History
| Financial Year | Dividend Type | DPS (₹) | Dividend % | Record Date |
|---|---|---|---|---|
| FY2025-26 | Final | ₹2.00 | 20% | Sep 1, 2026 |
| FY2024-25 | Final | ₹1.50 | 15% | Sep 19, 2025 |
Assessment: Danish Power listed in October 2024 and has paid dividends in both completed financial years since listing. The 33% increase in DPS (₹1.50 → ₹2.00) is encouraging. However, with only two data points, no long-term consistency trend can be established. Classification: New Payer — Too Early to Classify.
Danish Power Limited Financial Performance Analysis
| Metric | FY2023-24 | FY2024-25 | FY2025-26 | YoY Growth |
|---|---|---|---|---|
| Revenue (₹ Cr) | 310.00 | 426.72 | 521.45 | +22.2% |
| EBITDA (₹ Cr) | 56.87 | 89.24 | 99.72 | +11.7% |
| PAT (₹ Cr) | 36.82 | 54.63 | 68.98 | +26.3% |
| EPS (₹) | 18.70 | 27.74 | 35.03 | +26.3% |
Danish Power demonstrates strong earnings growth with PAT compounding at 87.4% CAGR over four years. The gap between revenue growth (22.2%) and EBITDA growth (11.7%) indicates margin compression at the operating level, but PAT still outpaced revenue due to lower finance costs. Management must address operating cost inflation to sustain margin quality.
Danish Power Limited Cash Flow Analysis
Cash Flow Summary (FY2025-26)
Operating Cash Flow: ₹42.50 Crore
Investing Cash Flow: -₹68.35 Crore
Free Cash Flow: -₹25.85 Crore
OCF / PAT Ratio: 61.6%
OCF Coverage of Dividend: 10.8x
FCF Coverage of Dividend: Negative (Not Covered)
Cash Flow Quality Assessment
OCF of ₹42.50 Crore against PAT of ₹68.98 Crore yields a 61.6% conversion ratio — below the ideal 80%+ benchmark, suggesting some earnings are locked in receivables or inventory. FCF is negative at -₹25.85 Crore due to heavy capex/investment outflows of ₹68.35 Crore. This means the dividend is funded from existing cash reserves, not current-year free cash flow. For a growth company investing in capacity expansion, negative FCF is contextually acceptable — but it means dividend payments are reducing the company's investment war chest.
Danish Power Limited Balance Sheet Strength
Liquidity Position
Cash & Investments: ₹92 Crore
Total Debt: ~₹4 Crore (nearly nil)
Net Cash Position: ~₹88 Crore
Cash Coverage of Dividend: 23.4x
Balance Sheet Assessment
Danish Power has a fortress balance sheet with ₹92 Crore in cash against negligible debt (D/E ~0.01). The cash pile — largely from IPO proceeds — provides 23.4x coverage of the ₹3.94 Crore dividend outflow. The company could theoretically pay this dividend for over 23 years from cash alone, even with zero future earnings. This provides significant comfort on dividend sustainability, though the cash reserve also needs to fund ongoing capex.
Danish Power Limited Dividend Sustainability Scorecard
✓ Earnings Coverage
Payout ratio 5.71% | Coverage 17.52x — earnings comfortably cover the dividend with massive headroom
✓ OCF Coverage
OCF ₹42.50 Cr covers dividend ₹3.94 Cr by 10.8x — strong operational cash generation relative to dividend commitment
✗ FCF Coverage
FCF is negative (-₹25.85 Cr) — dividend not covered by free cash flow due to heavy capex of ₹68.35 Crore for capacity expansion
✓ Cash/Liquidity Coverage
Cash reserves ₹92 Cr provide 23.4x coverage — substantial liquidity buffer far exceeding dividend requirements
Verdict: SUSTAINABLE — Danish Power passes 3 of 4 sustainability tests. The negative FCF is attributable to growth capex, not business deterioration. With earnings coverage of 17.52x and cash reserves of ₹92 Crore, the ₹3.94 Crore dividend outflow is comfortably sustainable at the current payout level.
Danish Power Limited Peer Comparison
| Company | Yield (%) | Payout (%) | ROE (%) | ROCE (%) | D/E |
|---|---|---|---|---|---|
| Danish Power | 0.21 | 5.71 | 16.70 | 22.17 | 0.01 |
| Voltamp Transformers | 0.30 | 15.00 | 20.50 | 27.10 | 0.00 |
| Atlanta Electricals | 0.15 | 8.50 | 14.20 | 19.30 | 0.10 |
| Quality Power Electrical | 0.10 | 4.20 | 22.30 | 30.50 | 0.05 |
| T&R India (Transformers) | 0.25 | 10.00 | 18.00 | 24.00 | 0.02 |
Observation: Danish Power's yield of 0.21% is broadly in line with the power equipment sector, where growth companies typically yield below 0.5%. Its payout ratio of 5.71% is conservative but comparable to peers. Return ratios (ROE 16.70%, ROCE 22.17%) are competitive, and the near-zero debt profile is an advantage. Source: Company filings, Screener.in, NSE/BSE data (approximate as of Sep 2026).
Danish Power Limited Promoter Dividend Impact
Promoter Benefit Calculation
Promoter Holding: 73.62%
Total Dividend Outflow: ₹3.94 Crore
Promoter Dividend Income: 73.62% × ₹3.94 Cr = ₹2.90 Crore
Minority (Public) Share: ₹1.04 Crore
Capital Allocation Assessment
With promoter holding at 73.62%, nearly three-quarters of the dividend flows to the promoter group. The small outflow of ₹3.94 Crore means the promoter benefit is modest at ₹2.90 Crore. Given the company has ₹92 Crore in cash and negative FCF from capex, management could have alternatively used this ₹3.94 Crore for additional capacity investment or debt reduction. However, at just 5.71% of PAT, the dividend is immaterial to capital allocation strategy and serves primarily as a shareholder signaling mechanism.
Danish Power Limited Dividend Taxation Analysis
Indian Dividend Tax Rules
Dividends are taxable as "Income from Other Sources" at the investor's applicable income tax slab rate.
TDS: Companies deduct 10% TDS on dividends exceeding ₹5,000 per financial year per shareholder.
Surcharge & Cess: Applicable as per the investor's income bracket.
No exemption under Section 10(34) — abolished from April 2020.
Worked Example — Effective Yield
Shares Held: 1,000
Dividend Per Share: ₹2.00
Gross Dividend: 1,000 × ₹2.00 = ₹2,000
TDS (10%): ₹200 (since ₹2,000 < ₹5,000, TDS may not apply)
Tax at 30% Slab + 4% Cess: ₹2,000 × 31.2% = ₹624
Net Dividend After Tax: ₹2,000 - ₹624 = ₹1,376
Effective Yield (at CMP ₹967): ₹1,376 ÷ (1,000 × ₹967) = 0.14%
Tax Impact: At the highest tax slab, the already-low yield of 0.21% falls to an effective 0.14% — reinforcing that Danish Power's dividend is not a meaningful income component for high-tax-bracket investors.
Danish Power Limited – Key Risks
Raw Material Inflation: Copper and CRGO steel are primary inputs. Price volatility directly impacts margins — EBITDA margin already contracted from 20.9% to 19.1% in FY26.
Customer Concentration: As a mid-sized transformer manufacturer, Danish Power may have significant revenue dependency on a few large utility orders, creating lumpy revenue risk.
Negative Free Cash Flow: FCF was -₹25.85 Crore in FY26. While attributable to growth capex, prolonged negative FCF could strain the ₹92 Crore cash buffer if returns on investment are delayed.
Competitive Intensity: The transformer sector has well-capitalized incumbents (Voltamp, ABB, Siemens). Pricing pressure in tenders could compress margins further.
Execution Risk on Capex: Heavy capex spending needs to translate into revenue within 12-18 months. Delays in commissioning or order booking could hurt return ratios.
Valuation Premium: At ~28x trailing P/E, the stock prices in significant growth expectations. Any earnings disappointment could trigger sharp corrections, negating years of dividend income.
What To Monitor – Danish Power Limited
EBITDA Margin Trend: Watch whether the margin compression (20.9% → 19.1%) continues or reverses in upcoming quarters.
Order Book Growth: Track quarterly order inflow disclosures to assess revenue visibility and capacity utilization trajectory.
Cash Flow Conversion: OCF/PAT ratio at 61.6% needs improvement. Monitor receivable days and inventory management.
Capex Returns: Track whether the ₹68.35 Crore invested translates into proportional revenue growth in FY27.
Cash Burn Rate: With negative FCF and capex plans, monitor the depletion rate of the ₹92 Crore cash reserve.
Government T&D Capex: Sector tailwind from India's power transmission expansion. Any policy delays could impact the entire sector.
Danish Power Limited Dividend – Conclusion
Danish Power Limited's ₹2.00 per share final dividend for FY2025-26 is a token payout from a company firmly in growth mode. The 0.21% yield is negligible — the real story here is 87.4% PAT CAGR, 22.17% ROCE, and a nearly debt-free balance sheet. With earnings coverage of 17.52x and cash reserves of ₹92 Crore, the dividend is comfortably sustainable but inconsequential for income investors. The 33% DPS increase from FY25 signals management's willingness to share profits, but at a 5.71% payout ratio, the overwhelming majority of earnings are being reinvested. Investors should evaluate Danish Power as a growth opportunity in India's power infrastructure buildout, not as a dividend play. The dividend is a signaling mechanism, not a return driver.
Frequently Asked Questions – Danish Power Limited Dividend
What dividend has Danish Power Limited announced for FY2025-26?
What is the dividend yield of Danish Power Limited?
What was the record date for Danish Power Limited dividend?
What was the ex-dividend date for Danish Power?
When will Danish Power Limited pay the dividend?
Who was eligible for Danish Power Limited's FY26 dividend?
How is Danish Power Limited dividend taxed in India?
Is Danish Power Limited's dividend sustainable?
What is Danish Power Limited's dividend history?
What should investors monitor about Danish Power Limited going forward?
How does Danish Power's dividend yield compare to peers?
What is the promoter holding in Danish Power Limited?
Disclaimer
This article is published by ShareBazaar Online for informational and educational purposes only. It does not constitute investment advice, a recommendation, or a solicitation to buy, sell, or hold any security. All data has been sourced from company filings, stock exchange disclosures, and publicly available financial databases. While every effort has been made to ensure accuracy, ShareBazaar Online does not guarantee the completeness or timeliness of the information presented. Financial markets are subject to risks, and past performance is not indicative of future results. Investors are advised to consult a SEBI-registered financial advisor before making any investment decisions. Dividend yields, financial ratios, and peer comparisons are based on data available as of the date of publication and may change. ShareBazaar Online and its authors do not hold any position in Danish Power Limited at the time of writing. Keyword metrics referenced in this article are flagged as Not Independently Verified (NIV) where tool-generated data was unavailable.