
Dividend Snapshot – Marathon Nextgen Realty Limited
Face-Value Illusion Alert
The headline reads 20% dividend — but that 20% is on a ₹5 face value, translating to just ₹1.00 per share. At the current market price of ~₹401, the real dividend yield is only 0.25%. A savings account pays more. Investors must always compute yield on market price, not face value.
Dividend Per Share
₹1.00
20% on FV ₹5
Dividend Yield
0.25%
At CMP ₹401
Dividend Type
Final
FY 2025-26
Record Date
18 Sep 2026
Passed
Ex-Date
18 Sep 2026
Passed
Dividend Outflow
₹6.74 Cr
67,420,600 shares
Marathon Nextgen Realty Limited – Company Overview
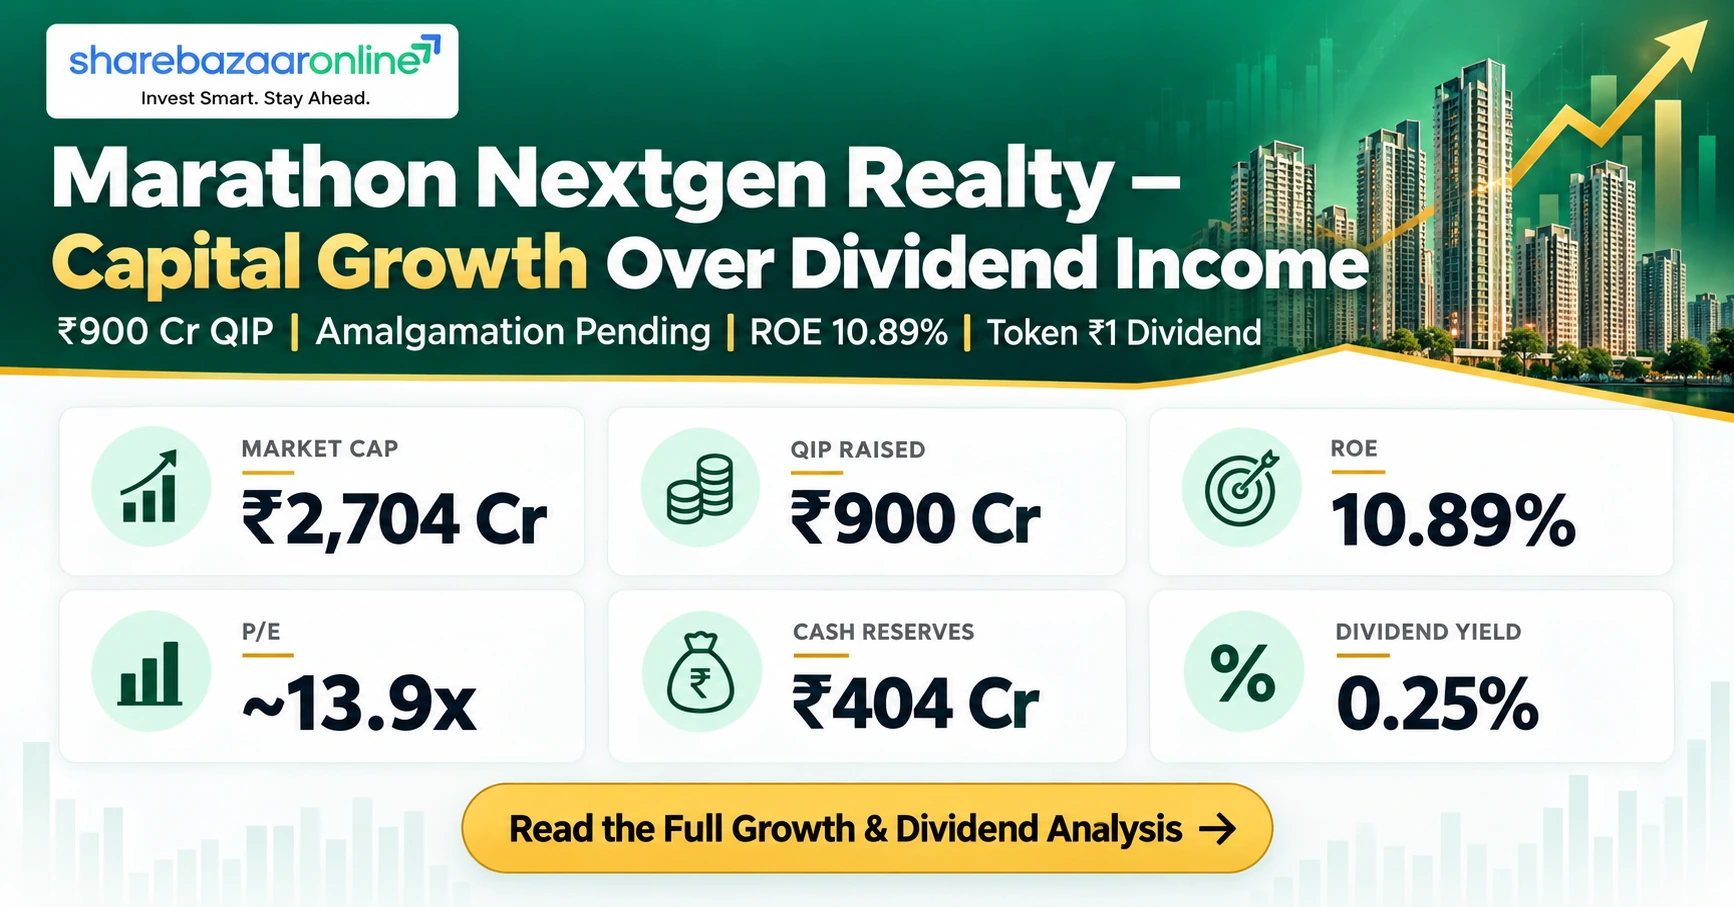
Marathon Nextgen Realty Limited (NSE: MARATHON | BSE: 503101 | ISIN: INE182D01020) is a Mumbai-based real estate holding and development company. Operating primarily through subsidiaries, the company focuses on commercial and residential real estate in the Mumbai Metropolitan Region. Its portfolio includes the landmark Marathon Futurex commercial tower in Lower Parel. The company has a market capitalisation of approximately ₹2,704 Crore at the current price of ₹401. A notable development during FY2025-26 is the board-approved Composite Scheme of Amalgamation involving subsidiary Marathon Realty Private Limited (MRPL) and others, submitted to the NCLT for approval. The company also completed a Qualified Institutional Placement (QIP) of ₹899.99 Crore during the year, significantly strengthening its capital base. Face value is ₹5 per share with paid-up capital of ₹33.71 Crore.
Market Cap
₹2,704 Cr
P/E Ratio
~13.9x
ROE
10.89%
ROCE
12.60%
Marathon Nextgen Realty Limited – Financial Analysis
Consolidated (FY2025-26)
| Total Revenue | ₹486.01 Cr |
| Revenue Growth | -14.5% |
| Net Profit (PAT) | ₹206.36 Cr |
| PAT Growth | +8.3% |
| EPS | ₹32.56 |
| Operating Cash Flow | -₹54.16 Cr |
Standalone (FY2025-26)
| Total Revenue | ₹337.45 Cr |
| Revenue Growth | -26.9% |
| Net Profit (PAT) | ₹189.44 Cr |
| Other Income Share | 47.6% |
| EPS | ₹29.91 |
| Operating Cash Flow | ₹9.25 Cr |
Earnings Quality Warning
Standalone other income (₹160.67 Cr) constitutes 47.6% of total income — nearly half of earnings come from non-operational sources. Consolidated revenue declined 14.5% while PAT grew 8.3%, indicating profit growth was not driven by core business expansion.
Marathon Nextgen Realty Limited – Dividend History (10 Years)
| Financial Year | DPS (₹) | Type | Ex-Date |
|---|---|---|---|
| FY 2025-26 | ₹1.00 | Final | 18-Sep-2026 |
| FY 2024-25 | ₹1.00 | Final | 19-Sep-2025 |
| FY 2023-24 | ₹1.00 | Final | 18-Sep-2024 |
| FY 2022-23 | ₹1.00 | Final | 18-Sep-2023 |
| FY 2021-22 | ₹0.50 | Final | 22-Sep-2022 |
| FY 2020-21 | Nil | — | — |
| FY 2019-20 | Nil | — | — |
| FY 2018-19 | ₹0.50 | Final | 17-Sep-2019 |
| FY 2017-18 | ₹2.00 | Final | 10-Sep-2018 |
| FY 2016-17 | ₹0.50* | Final | 08-Sep-2017 |
| FY 2015-16 | ₹0.50* | Final | 15-Sep-2016 |
* Adjusted for 2:1 stock split (April 2018). Source: BSE filings, Screener.in
Classification: Irregular Payer. Marathon Nextgen skipped dividends entirely in FY20 and FY21 (Covid years), and the quantum has varied between ₹0.50 and ₹2.00 over the decade. The current ₹1.00 level has been maintained for four consecutive years (FY23–FY26), showing recent stabilisation but not a long enough track record for consistent payer status.
Expert Commentary – Marathon Nextgen Realty Limited Dividend
Marathon Nextgen's ₹1.00 dividend is a token capital return, not a meaningful income event. At ₹6.74 Crore outflow against ₹404.62 Crore in consolidated liquid assets, the company is distributing less than 1.7% of its available cash. The real story here is capital allocation: the board raised ₹900 Crore through QIP, approved an amalgamation scheme, and is clearly prioritising business restructuring over shareholder distributions. For income-seeking investors, a 0.25% yield is economically irrelevant — even a liquid fund delivers 15–20x more. However, for growth investors, the low payout signals management's conviction that retained capital generates superior returns through real estate development. The negative consolidated operating cash flow (-₹54.16 Crore) deserves scrutiny: reported profits of ₹206.36 Crore did not convert into operating cash, raising questions about receivables quality and revenue recognition timing in the real estate cycle.
Marathon Nextgen Realty Limited – Future Outlook
The proposed amalgamation of subsidiary Marathon Realty Private Limited (MRPL) and others into Marathon Nextgen is the defining event ahead. If NCLT approves the scheme, Marathon Nextgen's consolidated structure will simplify significantly, potentially unlocking value through direct ownership of MRPL's assets and revenue streams. The company has already entered a revenue-sharing arrangement with MRPL (pending amalgamation completion), indicating management is preparing for this transition. The ₹900 Crore QIP war chest provides capital for expansion in the Mumbai real estate market. Dividend growth is unlikely in the near term — the board has maintained ₹1.00 for four years and shows no inclination to increase it while deploying capital into business restructuring. Investors should view Marathon Nextgen as a capital appreciation play, not a dividend income stock.
Marathon Nextgen Realty Limited – Dividend Announcement Summary
The Board of Directors of Marathon Nextgen Realty Limited, at its meeting held on 27 May 2026, recommended a Final Dividend of ₹1.00 per equity share (20% on face value ₹5) for the financial year ended 31 March 2026. This dividend is subject to approval at the Annual General Meeting. The board also approved audited standalone and consolidated financial results for FY2025-26, along with appointing cost auditors (A.G. Tiwari & Associates) and internal auditors (Pipalia Singhal & Associates). The dividend recommendation was part of a broader meeting that also addressed the ongoing Composite Scheme of Amalgamation and subsidiary appointments. On the announcement date, Marathon Nextgen's share price closed at ₹488.05 on NSE, implying an announcement-date yield of just 0.20%.
Marathon Nextgen Realty Limited – Key Dates Timeline
27 May 2026 — Announcement Date
Board recommended ₹1.00 final dividend. CMP: ₹488.05
18 Sep 2026 — Ex-Date (Passed)
Shares purchased on or after this date were not eligible for dividend
18 Sep 2026 — Record Date (Passed)
Shareholders on record as of this date were eligible
Payment Date — Within 30 days of AGM
Exact date not disclosed by company. Expected Oct–Nov 2026.
Marathon Nextgen Realty Limited – Dividend Yield Analysis
Yield Metrics
| Dividend Per Share | ₹1.00 |
| Current CMP | ₹401 |
| Current Yield | 0.25% |
| Announcement CMP | ₹488.05 |
| Announcement Yield | 0.20% |
Yield Reality Check
Marathon Nextgen's 0.25% yield is among the lowest in Indian real estate. The yield is low because the share price (~₹401) is high relative to the token ₹1.00 dividend — not because of share price erosion. This stock had risen from ~₹300 to ₹488 during FY26 before correcting, so the low yield reflects capital appreciation outpacing dividend growth. For context, a bank savings account offers 3–4%, and even large-cap realty peers like Brigade Enterprises yield 0.3–0.5%. Marathon Nextgen is clearly a growth-oriented allocation, not an income play.
Marathon Nextgen Realty Limited – Dividend History Analysis
Over the past decade, Marathon Nextgen has paid dividends in 8 out of 11 years, skipping FY20 and FY21 during Covid. The dividend quantum has fluctuated: ₹0.50 (adjusted) in FY16–FY17, ₹2.00 in FY18, ₹0.50 in FY19, nil in FY20–FY21, ₹0.50 in FY22, and ₹1.00 from FY23 onwards. A 2:1 stock split in April 2018 halved the per-share dividend comparison. The current ₹1.00 per share level has been flat for four consecutive years, showing the board treats dividends as a token payout rather than a growing capital return. Total dividends paid in the last decade amount to roughly ₹7.50 per share (adjusted), while the stock price has appreciated from ~₹80 (split-adjusted) to ₹401 — a 5x return. Capital gains, not dividends, have driven shareholder returns.
Marathon Nextgen Realty Limited – Financial Performance Analysis
Operating Leverage & Revenue Quality
Consolidated revenue fell 14.5% to ₹486.01 Crore while PAT grew 8.3% to ₹206.36 Crore — a clear divergence. On standalone basis, the picture is starker: operational revenue declined 26.9%, but other income of ₹160.67 Crore (comprising interest, dividends from subsidiaries, and rental income) constituted 47.6% of total standalone income. This means nearly half of standalone earnings came from non-core activities. EBITDA margins improved despite revenue decline, suggesting cost control rather than business growth drove profitability. Investors should distinguish between paper profits driven by subsidiary dividends and inter-company transactions versus cash-generating operational performance. The pending amalgamation will eliminate inter-company income flows, making future standalone results more reflective of actual business performance.
Marathon Nextgen Realty Limited – Cash Flow Analysis
RED FLAG: Negative Consolidated Operating Cash Flow
Consolidated OCF was -₹54.16 Crore despite PAT of ₹206.36 Crore. Reported profits did not convert into cash from operations. This is a critical disconnect that requires investigation.
Standalone Cash Flow
| Operating Cash Flow | ₹9.25 Cr |
| OCF / PAT Ratio | 4.9% |
| Free Cash Flow Coverage | 1.15x |
| Assessment | Weak |
Consolidated Cash Flow
| Operating Cash Flow | -₹54.16 Cr |
| OCF / PAT Ratio | Negative |
| FCF Coverage | Negative |
| Assessment | Red Flag |
Analysis: In real estate, negative OCF is not unusual during heavy project development phases — working capital gets locked in inventory (land, under-construction projects) and trade receivables. However, persistent negative consolidated OCF while reporting positive PAT suggests that revenue recognition is running ahead of cash collection. The dividend is funded from existing cash reserves, not current cash flows. Standalone FCF barely covers the dividend at 1.15x — a razor-thin margin.
Marathon Nextgen Realty Limited – Balance Sheet Strength
Standalone
| Cash & Liquid Assets | ₹331.76 Cr |
| Net Cash | ₹330.59 Cr |
| Liquidity Coverage | 49.2x |
Consolidated
| Cash & Liquid Assets | ₹404.62 Cr |
| Debt/Equity | 0.04 |
| Liquidity Coverage | 60x |
Marathon Nextgen's balance sheet is a fortress. With ₹404.62 Crore in liquid assets covering the ₹6.74 Crore dividend 60 times over, there is zero risk of dividend non-payment. The company is virtually debt-free (D/E 0.04 consolidated). The ₹900 Crore QIP in FY26 bolstered equity substantially. However, ample liquidity also raises a capital allocation question: is management deploying this cash productively, or is it sitting idle? With ROE at 10.89% and ROCE at 12.60%, returns on capital are adequate but not exceptional for a real estate company sitting on a cash pile of this magnitude.
Marathon Nextgen Realty Limited – Dividend Sustainability Analysis
Four-Test Sustainability Scorecard
| Test | Result | Verdict |
|---|---|---|
| Earnings Coverage (EPS ÷ DPS) | 32.56x | Pass |
| OCF Coverage (Consolidated) | Negative | Fail |
| FCF Coverage (Standalone) | 1.15x | Marginal |
| Liquidity Coverage | 60x | Pass |
Classification: Moderately Sustainable
Earnings coverage is excellent (32.56x) and the cash reserve is massive (60x coverage). However, the dividend is not funded from current cash flows — consolidated OCF is negative. The ₹1.00 dividend survives only because the outflow is trivially small (₹6.74 Crore) relative to the company's cash pile. If Marathon Nextgen's business cash flows don't improve and the cash pile depletes through capital expenditure or acquisitions, even this token dividend could face pressure.
Marathon Nextgen Realty Limited – Peer Comparison
| Company | Yield | Payout | ROE | D/E |
|---|---|---|---|---|
| Marathon Nextgen | 0.25% | 3.3% | 10.9% | 0.04 |
| Brigade Enterprises | 0.3–0.5% | 5–8% | 12–15% | 0.6–0.8 |
| Sobha Limited | 0.2–0.4% | 8–12% | 5–8% | 0.5–0.7 |
| Anant Raj | 0.1–0.2% | 2–5% | 6–9% | 0.3–0.5 |
| Max Estates | Nil | 0% | 3–5% | 0.1–0.3 |
Source: Value Research, Screener.in. Ranges reflect trailing 12-month estimates.
Marathon Nextgen's yield and payout ratio are among the lowest in the mid-cap realty peer group. However, its balance sheet is the strongest — virtually debt-free with the lowest D/E ratio. This positions Marathon Nextgen as a conservative, cash-rich compounder rather than an income-generating realty stock. Brigade Enterprises offers higher yield with reasonable leverage, making it a better choice for dividend-focused realty investors.
Marathon Nextgen Realty Limited – Promoter Impact Analysis
Shareholding Pattern
| Promoter Holding | 56.42% |
| FII Holding | ~4.7% |
| DII Holding | ~14.7% |
| Mutual Fund Holding | ~9.94% |
| Promoter Pledging | 0% |
Promoter Dividend Income
| Promoter Shares | ~38,04,106 |
| Promoter Dividend | ₹3.80 Crore |
| % of Total Outflow | 56.42% |
With 56.42% holding and zero pledging, the promoter group receives ₹3.80 Crore of the total ₹6.74 Crore dividend. The promoter family (Marathon Group) controls the company through direct and indirect holdings. The low dividend is unlikely to be a significant income source for promoters either — their wealth creation has been through capital appreciation and subsidiary operations. The ongoing amalgamation scheme will consolidate the group's real estate assets under Marathon Nextgen, which may alter the dividend calculus post-completion.
Marathon Nextgen Realty Limited – Dividend Taxation Analysis
Indian Dividend Tax Rules (FY2025-26)
Dividends are taxable in the hands of the investor at their applicable income tax slab rate. Companies deduct TDS at 10% if total dividend income from that company exceeds ₹5,000 in a financial year. For Marathon Nextgen, an investor would need more than 5,000 shares to trigger TDS. NRI shareholders face TDS at 20% (plus surcharge and cess) under Section 195, subject to DTAA benefits.
Worked Example: 1,000 Shares | 30% Tax Slab
| Shares Held | 1,000 |
| Dividend Per Share | ₹1.00 |
| Gross Dividend | ₹1,000 |
| Tax at 30% + 4% Cess | ₹312 |
| Net Dividend (Post-Tax) | ₹688 |
| Effective Yield (Post-Tax) | 0.17% |
At a 30% tax slab, the effective post-tax yield drops to just 0.17% — roughly one-fifth of a percentage point. For high-income investors, Marathon Nextgen's dividend is virtually meaningless as an income component after taxation.
Marathon Nextgen Realty Limited – Key Risks
Negative Consolidated Operating Cash Flow
-₹54.16 Crore OCF despite ₹206 Crore PAT signals cash conversion issues. Persistent negative OCF will erode the cash reserve that currently backstops the dividend.
Revenue Concentration in Mumbai
Geographical concentration in the Mumbai Metropolitan Region exposes the company to local regulatory changes (RERA, stamp duty revisions), property market cycles, and infrastructure delays.
Amalgamation Execution Risk
The Composite Scheme of Amalgamation requires NCLT approval and involves complex inter-company asset transfers. Delays or unfavourable terms could disrupt the restructuring timeline.
Other Income Dependency
47.6% of standalone income comes from non-operational sources. Post-amalgamation elimination of inter-company income could expose weaker underlying operational performance.
Real Estate Sector Cyclicality
Rising interest rates, regulatory tightening, and slowing demand could compress margins and delay project launches, directly impacting revenue and cash generation.
QIP Dilution Impact
The ₹900 Crore QIP increased equity base significantly. If this capital is not deployed at returns exceeding cost of equity, EPS and ROE will dilute further.
Marathon Nextgen Realty Limited – What To Monitor
NCLT Amalgamation Approval Timeline
Track NCLT hearing dates for the Composite Scheme. Approval triggers significant changes in financial reporting, asset ownership, and potentially dividend policy.
Consolidated OCF Trajectory
Watch quarterly cash flow statements. Sustained negative OCF across FY27 would indicate structural cash conversion problems, not just cyclical project timing.
QIP Capital Deployment
Monitor how the ₹900 Crore QIP proceeds are deployed — land acquisitions, new project launches, or cash sitting idle. Deployment pace signals management's growth confidence.
New Project Launches & Pre-Sales
Real estate revenue is lumpy. Watch for new launch announcements, pre-sales velocity, and collection efficiency to gauge future revenue visibility.
Receivables & Inventory Movement
Rising receivables and inventory as a percentage of revenue would explain negative OCF and signal potential write-down risk. Compare quarterly balance sheet trends.
Mumbai Real Estate Market Conditions
Track RERA registrations, stamp duty collections, and property registration data for MMR region. Macro demand directly impacts Marathon Nextgen's project absorption rates.
Marathon Nextgen Realty Limited Dividend – Conclusion
Marathon Nextgen Realty's ₹1.00 final dividend for FY2025-26 is a token payout that delivers a real yield of just 0.25% — dropping to 0.17% post-tax for high-slab investors. The company is clearly in capital deployment mode: a ₹900 Crore QIP, a pending amalgamation, and a growing real estate pipeline signal that retained earnings and fresh capital are being channelled into business growth, not shareholder distributions. The fortress balance sheet (60x dividend coverage, near-zero debt) ensures the dividend is safe, but the negative consolidated OCF (-₹54.16 Crore) is a genuine concern that warrants monitoring. Income investors should look elsewhere — this stock does not generate meaningful dividend income. Growth investors should evaluate Marathon Nextgen on capital appreciation potential, project pipeline quality, and amalgamation execution rather than on its negligible dividend.
Frequently Asked Questions – Marathon Nextgen Realty Limited Dividend
What dividend has Marathon Nextgen Realty announced for FY2025-26?
What is Marathon Nextgen Realty's current dividend yield?
What was the record date for Marathon Nextgen Realty's dividend?
What was the ex-date for Marathon Nextgen Realty's dividend?
When will Marathon Nextgen Realty pay the dividend?
Who was eligible for Marathon Nextgen Realty's FY26 dividend?
How is Marathon Nextgen Realty's dividend taxed in India?
Is Marathon Nextgen Realty's dividend sustainable?
What is Marathon Nextgen Realty's 10-year dividend history?
What should investors monitor about Marathon Nextgen Realty going forward?
Why is the headline "20% dividend" misleading for Marathon Nextgen?
What is the Marathon Nextgen Realty amalgamation scheme?
Disclaimer
This article is published by ShareBazaar Online for informational and educational purposes only. It does not constitute financial advice, investment recommendation, or solicitation to buy, sell, or hold any securities. All data has been sourced from publicly available company filings (BSE/NSE), annual reports, and third-party financial databases. While every effort has been made to ensure accuracy, ShareBazaar Online does not guarantee completeness or timeliness of the information. Investors should conduct their own due diligence or consult a SEBI-registered financial advisor before making investment decisions. Past dividend performance does not guarantee future payouts. ShareBazaar Online and its authors do not hold any position in Marathon Nextgen Realty Limited shares as of the date of publication. Market data referenced includes CMP as of early October 2026 and may have changed by the time of reading. Keyword metrics referenced in this article are Not Independently Verified (NIV) due to API limitations at the time of research.