
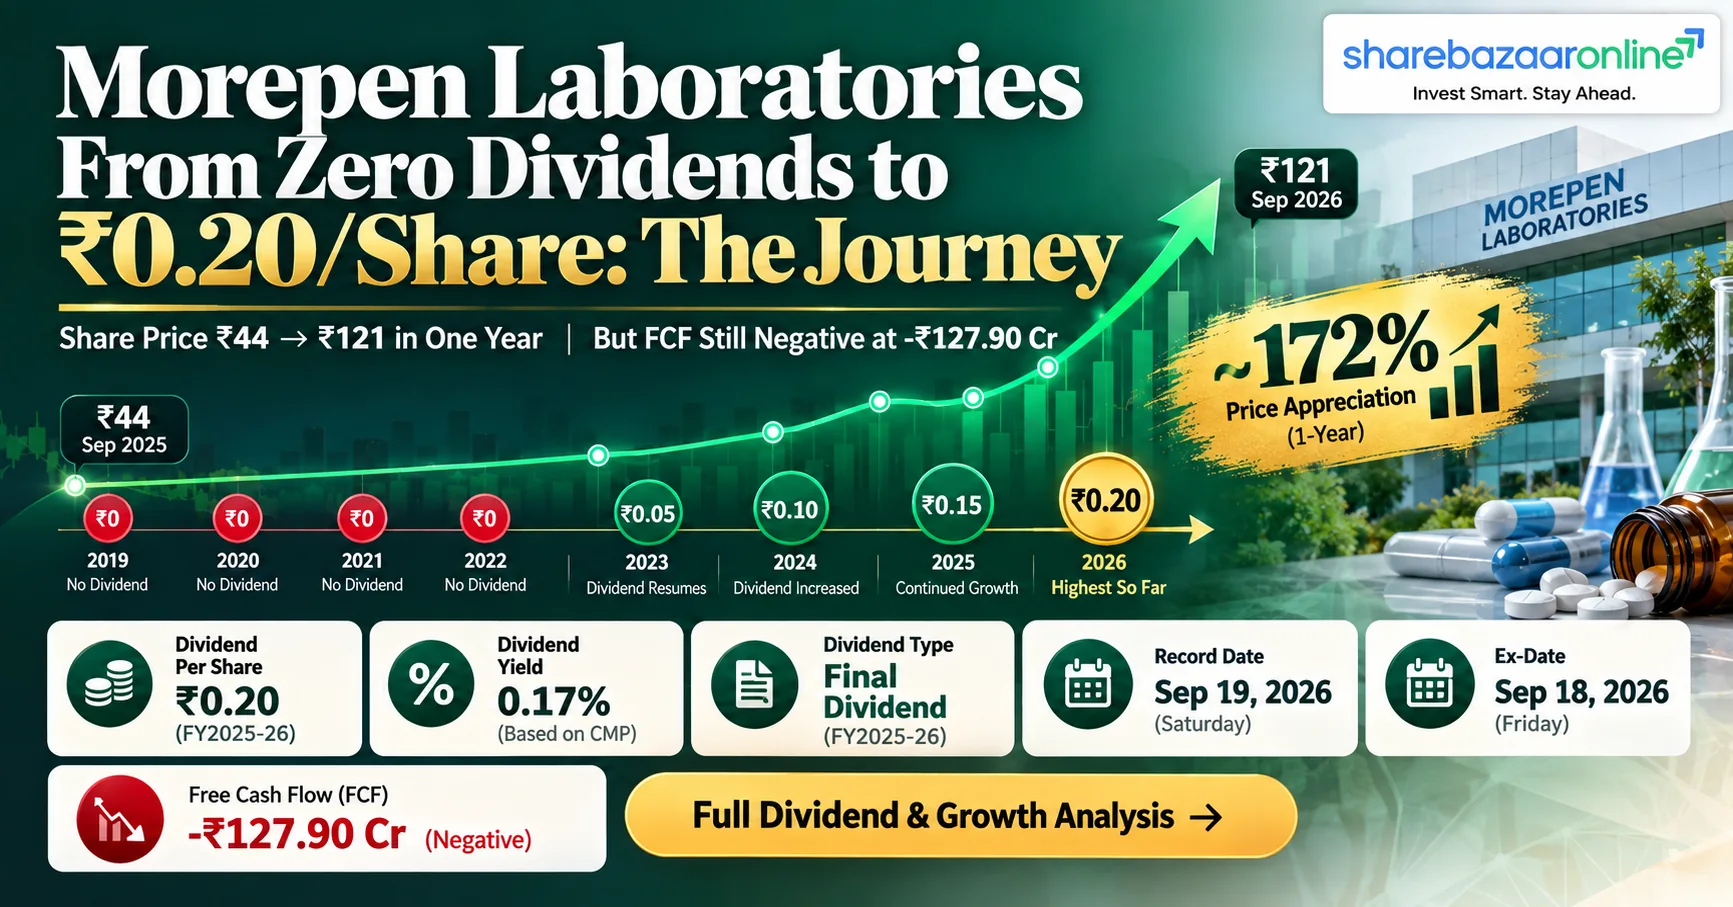
Dividend Snapshot – Morepen Laboratories Limited
Dividend Per Share
₹0.20
10% on Face Value of ₹2
Dividend Yield (Current CMP)
0.17%
At CMP of ₹121
Dividend Type
Final Dividend
FY2025-26 | Subject to AGM (Held 26 Sep 2026)
Total Dividend Outflow
₹10.96 Crore
Payout Ratio: 11.55% of Consolidated PAT
⚠ Face Value Illusion: The 10% dividend sounds impressive but translates to just ₹0.20 per share on a ₹2 face value. At the current market price of ₹121, the real dividend yield is only 0.17% — significantly below typical savings account returns. This is Morepen’s second-ever dividend, following an identical ₹0.20 payout in FY25.
Morepen Laboratories Limited – Company Overview
Morepen Laboratories Limited (NSE: MOREPENLAB | BSE: 500288 | ISIN: INE083A01026) is a Gurugram-headquartered pharmaceutical company engaged in API manufacturing, formulations, home diagnostics, and medical devices. Founded in 1984, the company operates manufacturing facilities in Baddi (Himachal Pradesh) and has expanded into CDMO (Contract Development and Manufacturing Organisation) services. Its consumer brands include Dr. Morepen (glucometers, BP monitors, thermometers) and Burnol. The company is currently hiving off its Medical Devices business to subsidiary Morepen Medipath Limited via a Business Transfer Agreement at a slump sale consideration of ₹197.10 Crore. With a market capitalisation of approximately ₹6,604 Crore and promoter holding of 28.63%, Morepen has 54.79 Crore equity shares outstanding on a face value of ₹2 each.
Morepen Laboratories Limited Financial Analysis
Consolidated P&L Highlights (FY26)
- Revenue: ₹1,805.69 Cr (↓0.3% YoY)
- PAT (after minority): ₹94.88 Cr (↓19.6% YoY)
- EPS: ₹1.73 (FY25: ₹2.20)
- EPS ex-exceptional: ₹1.32
- Exceptional gain: ₹25.83 Cr (subsidiary exit)
Key Ratios
- ROE: 7.90%
- ROCE: 8.29%
- EBITDA: ₹146.94 Cr
- Interest Coverage: 7.31x
- Debt-to-Equity: 0.16x
⚠ Earnings Quality Alert: FY26 consolidated PAT of ₹94.88 Cr includes an exceptional gain of ₹25.83 Cr from loss of control of Dr. Morepen Limited. Excluding this one-time item, core PAT would be approximately ₹69 Cr and EPS just ₹1.32 — a 40% decline from FY25’s ₹2.20 EPS.
Morepen Laboratories Limited Dividend History
| Financial Year | DPS (₹) | Dividend % | Type |
|---|---|---|---|
| FY2025-26 | 0.20 | 10% | Final |
| FY2024-25 | 0.20 | 10% | Final |
| FY2023-24 | Nil | – | – |
| FY2022-23 | Nil | – | – |
| FY2021-22 | Nil | – | – |
| FY2020-21 | Nil | – | – |
| FY2019-20 | Nil | – | – |
| FY2018-19 | Nil | – | – |
| FY2017-18 | Nil | – | – |
| FY2016-17 | Nil | – | – |
Classification: New Dividend Initiator. Morepen Laboratories paid no dividends for approximately 40 years since incorporation in 1984. The company initiated dividends only in FY25 with ₹0.20 per share. FY26 marks only the second consecutive dividend at an identical ₹0.20 level. This is too early to classify as a consistent or growing dividend payer.
Expert Commentary – Morepen Laboratories Limited Dividend
Morepen’s decision to maintain the ₹0.20 dividend despite a 19.6% decline in consolidated PAT and deeply negative free cash flow signals management’s intent to establish a dividend track record. However, the dividend is largely symbolic — at ₹10.96 Crore, it represents just 11.55% of consolidated PAT. The real story is the aggressive capex programme: ₹160.54 Crore invested in PPE and intangibles against only ₹32.64 Crore operating cash flow. This expansion is being financed through a 145% surge in borrowings (₹79.39 Cr to ₹194.69 Cr). The company is simultaneously executing a medical devices business hive-off to Morepen Medipath at ₹197.10 Crore, a subsidiary exit (Dr. Morepen), and a CDMO capacity expansion — a complex multi-front transformation that demands careful monitoring.
Morepen Laboratories Limited Future Outlook
Morepen’s future dividend trajectory hinges on whether its heavy capex translates into revenue and margin expansion. The CDMO pivot positions it in a high-growth pharmaceutical outsourcing segment, but returns are typically delayed by 2–3 years post capacity commissioning. Near-term earnings face headwinds from elevated depreciation on new assets, higher finance costs from the borrowing surge, and potential one-time costs related to the medical devices business transfer. The Q1 FY27 PAT recovery (+425% QoQ per market reports) provides some reassurance, though base effects contributed significantly. Dividend growth beyond ₹0.20 appears unlikely until FCF turns positive, which requires operating cash flow to materially outpace capex — a development unlikely before FY28 at the earliest.
Morepen Laboratories Limited Dividend Announcement Summary
The Board of Directors of Morepen Laboratories Limited, at their meeting held on 26th May, 2026 (3:00 PM – 5:15 PM), recommended a final dividend of ₹0.20 per equity share (10% on face value of ₹2 each) for the financial year ended 31st March, 2026. The dividend was subject to approval by members at the Annual General Meeting, which was held on 26th September, 2026. Per Note 3 of the filing, the Board has the right to decrease but not increase the recommended amount. No dividend is payable on 50,62,872 shares surrendered and cancelled by NCLT order (pending formal cancellation by stock exchanges).
Morepen Laboratories Limited Key Dates Timeline
Announcement Date
26 May 2026
Board Meeting | CMP: ~₹44.50 (Est.)
Ex-Dividend Date
18 September 2026
Inferred (T+1 settlement from Record Date)
Record Date
19 September 2026
As disclosed by company
Payment Date
Not Disclosed by Company
Typically within 30 days of AGM
Eligibility Note: The record date of 19 September 2026 has already passed. Shareholders who held shares as of 19 September 2026 (i.e., purchased on or before the ex-date of 18 September 2026) were eligible for this dividend. The AGM was held on 26 September 2026.
Morepen Laboratories Limited Dividend Yield Analysis
Yield at Announcement (26 May 2026)
0.45%
DPS ₹0.20 ÷ CMP ~₹44.50
CMP estimated — stock fell 5%+ next day on weak Q4 results
Yield at Current CMP (Sep 2026)
0.17%
DPS ₹0.20 ÷ CMP ₹121
Stock rallied ~172% from announcement to current price
Yield Reality Check: The 0.17% yield is among the lowest in the pharma sector. The stock’s sharp rally from ₹44.50 to ₹121 has compressed the yield dramatically. Investors buying at current levels for dividend income would receive negligible returns — a ₹1 lakh investment yields just ₹170 annually. The stock’s appeal is clearly growth-driven (CDMO expansion, Q1 FY27 recovery), not income-driven.
Morepen Laboratories Limited Dividend History Analysis
Morepen Laboratories has an extremely limited dividend history. The company was incorporated in 1984 and paid no dividends for approximately four decades. The first-ever dividend of ₹0.20 per share was declared for FY2024-25, followed by an identical ₹0.20 for FY2025-26. While back-to-back dividends are encouraging, two data points do not establish a pattern. The flat ₹0.20 level despite 172% stock price appreciation suggests the company prioritises capital reinvestment over shareholder distributions — consistent with its heavy capex phase. The cash flow statement confirms dividend paid of ₹10.86 Crore in FY26 (representing the FY25 dividend), proving actual cash disbursement. No special or interim dividends have ever been declared.
Morepen Laboratories Limited Financial Performance Analysis
Revenue Trend (Consolidated)
- FY26: ₹1,805.69 Cr (↓0.3%)
- FY25: ₹1,811.58 Cr
- FY24: ₹1,528.25 Cr
- FY23: ₹1,577.04 Cr
- FY22: ₹1,504.77 Cr
Source: SE Filing & Screener.in
PAT Trend (Consolidated, After Minority)
- FY26: ₹94.88 Cr (↓19.6%)
- FY25: ₹118.02 Cr
- FY24: ₹75.91 Cr
- FY23: ₹108.16 Cr
- FY22: ₹104.82 Cr
Source: SE Filing & Screener.in
Operating Leverage Failure: Revenue was flat (↓0.3%) but PAT declined 19.6%. The culprit: Employee Benefits Expenses surged ₹232.74 Cr to ₹232.74 Cr (+8.9%), Selling & Distribution Expenses rose to ₹98.98 Cr, and Finance Costs jumped to ₹16.41 Cr from ₹8.34 Cr (+96.8%) reflecting the borrowing surge. Margin compression is evident despite top-line stability.
Morepen Laboratories Limited Cash Flow Analysis
Operating Cash Flow
₹32.64 Cr
FY25: ₹32.06 Cr | Flat YoY
OCF vs PAT: ₹32.64 Cr vs ₹94.88 Cr (only 34% cash conversion)
Free Cash Flow
₹–127.90 Cr
FY25: ₹–182.18 Cr | Improved but still deeply negative
Total Capex: ₹160.54 Cr (PPE ₹85.52 Cr + Intangibles ₹75.02 Cr)
Cash Flow Red Flag: Reported PAT of ₹94.88 Cr translated to only ₹32.64 Cr in operating cash flow — a 34% cash conversion ratio. The gap is explained by trade receivables increasing by ₹50.12 Cr and loans/other current assets absorbing ₹92.63 Cr. This weak cash conversion, combined with ₹160.54 Cr capex, means the dividend of ₹10.96 Cr is effectively being funded through fresh borrowings — not operating earnings.
Morepen Laboratories Limited Balance Sheet Strength
Debt Position
- Total Borrowings: ₹194.69 Cr (FY25: ₹79.39 Cr)
- Borrowing Growth: +145%
- Net Debt: ₹102.99 Cr
- Debt-to-Equity: 0.16x
- Net Debt/EBITDA: 0.70x
Liquidity Position
- Cash & Equivalents: ₹31.19 Cr
- Bank Balances (Other): ₹37.64 Cr
- Current Investments: ₹22.87 Cr
- Total Liquid Assets: ₹91.70 Cr
- NC Investments: ₹101.29 Cr
Borrowing Surge Warning: Borrowings nearly tripled from ₹79.39 Cr to ₹194.69 Cr in a single year, primarily driven by non-current borrowings (₹25.76 Cr to ₹133.60 Cr). While the debt-to-equity ratio remains low at 0.16x, the rate of increase is significant. Finance costs doubled from ₹8.34 Cr to ₹16.41 Cr. The goodwill write-off of ₹74.47 Cr (Dr. Morepen exit) also reduced total assets.
Morepen Laboratories Limited Dividend Sustainability Analysis
✔ Earnings Coverage — PASS
EPS of ₹1.73 covers DPS of ₹0.20 by 8.65x. Even ex-exceptional EPS of ₹1.32 covers DPS by 6.6x. Payout ratio is a modest 11.55%.
✔ OCF Coverage — PASS
Operating cash flow of ₹32.64 Cr covers dividend outflow of ₹10.96 Cr by 2.98x. However, OCF itself is weak relative to reported PAT.
✘ FCF Coverage — FAIL
Free cash flow is deeply negative at ₹–127.90 Cr due to aggressive capex of ₹160.54 Cr. Dividend is being funded through borrowings, not free cash.
✔ Liquidity Coverage — PASS
Total liquid assets of ₹91.70 Cr cover dividend outflow of ₹10.96 Cr by 8.37x. Adequate cushion exists for dividend payment.
Verdict: MODERATELY SUSTAINABLE
The ₹0.20 dividend is small enough to be easily funded from current earnings and liquidity (3 of 4 tests pass). However, the deeply negative FCF, 145% borrowing surge, and declining PAT trajectory raise concerns about whether the company should be paying dividends at all during this heavy investment phase. The dividend appears to be a signalling exercise rather than a genuine surplus distribution.
Morepen Laboratories Limited Peer Comparison
| Company | Div Yield | Payout % | ROE | ROCE | D/E |
|---|---|---|---|---|---|
| Morepen Labs | 0.17% | 11.55% | 7.90% | 8.29% | 0.16x |
| Divis Labs | ~0.7% | ~40% | ~16% | ~20% | ~0.01x |
| Laurus Labs | ~0.5% | ~20% | ~10% | ~12% | ~0.30x |
| Solara Active | ~0.3% | ~15% | ~5% | ~8% | ~0.50x |
| Granules India | ~0.4% | ~10% | ~18% | ~22% | ~0.20x |
Peer data approximate. Source: Screener.in. Morepen data from audited filing.
Morepen’s 0.17% yield is among the lowest in the API/pharma peer group. Its ROE of 7.90% and ROCE of 8.29% are below peer averages, reflecting the ongoing capex cycle’s drag on returns. The low debt-to-equity (0.16x) is a positive but is deteriorating rapidly. Among peers, Divi’s Labs offers significantly superior dividend yield, profitability, and debt metrics.
Morepen Laboratories Limited Promoter Impact Analysis
Promoter Shareholding
28.63%
As per latest shareholding pattern
Promoter Dividend Income
₹3.14 Crore
28.63% of ₹10.96 Cr total outflow
With a 28.63% stake, promoters receive ₹3.14 Crore from the ₹10.96 Crore dividend outflow. The remaining ₹7.82 Crore goes to public and institutional shareholders. The relatively modest promoter holding (below the 50%+ typical of family-run pharma companies) means promoters have limited direct financial incentive from dividends. The dividend at ₹0.20/share appears to be driven more by signalling intent to establish a track record rather than channelling cash to promoters. FII holding stands at approximately 1.31% and DII holding at approximately 2.73%, with retail dominating the non-promoter base.
Morepen Laboratories Limited Taxation Analysis
Under current Indian tax law, dividends are taxable in the hands of shareholders at their applicable income tax slab rate. TDS at 10% is deducted on dividend exceeding ₹5,000 in a financial year from a single company. For NRIs, TDS is deducted at 20% (plus applicable surcharge and cess).
Worked Example: 1,000 Shares | 30% Tax Slab
| Gross Dividend | ₹200 (1,000 × ₹0.20) |
| TDS @10% (if total >₹5,000) | ₹0 (below threshold) |
| Tax @30% + 4% Cess | ₹62.40 |
| Net Dividend After Tax | ₹137.60 |
| Effective Yield (at CMP ₹121) | 0.11% |
At the 30% tax slab, the already minimal 0.17% pre-tax yield compresses to an effective yield of just 0.11%.
Morepen Laboratories Limited Key Risks
- 1. Negative Free Cash Flow: FCF of ₹–127.90 Cr means the company cannot fund dividends, capex, and operations from internal accruals. The capex cycle (₹160.54 Cr in FY26) is being financed through debt, creating future repayment obligations.
- 2. Borrowing Surge: Total borrowings tripled from ₹79.39 Cr to ₹194.69 Cr in one year. If CDMO capacity ramp-up is delayed or yields lower-than-expected returns, this debt could become burdensome.
- 3. Earnings Quality Deterioration: FY26 PAT includes a ₹25.83 Cr exceptional gain. Core earnings (ex-exceptional) declined approximately 40% YoY. Operating cash flow was only 34% of reported PAT, indicating poor earnings quality.
- 4. Business Restructuring Execution Risk: Simultaneous Medical Devices hive-off (BTA with Morepen Medipath at ₹197.10 Cr), Dr. Morepen subsidiary exit, and CDMO expansion create execution complexity. Delays or cost overruns could impair near-term performance.
- 5. Receivables and Working Capital Stress: Trade receivables of ₹333.14 Cr (67 days of sales) grew despite flat revenue, absorbing ₹50.12 Cr of cash. If collection efficiency worsens further, working capital needs could consume any remaining operating cash flow.
- 6. Customer and Revenue Concentration: API manufacturing and CDMO services face concentration risk if a few clients account for a large revenue share. Loss of key contracts could significantly impact results.
- 7. Regulatory and Compliance Risk: Pharma manufacturing is subject to USFDA, WHO-GMP, and other regulatory inspections. Any adverse regulatory action at manufacturing facilities could disrupt operations and revenue.
Morepen Laboratories Limited – What To Monitor
- 1. FCF Inflection Point: Track quarterly OCF vs capex trajectory. FCF turning positive would be the single strongest signal that dividend growth can follow.
- 2. CDMO Revenue Ramp: Monitor new CDMO contract announcements, reactor utilisation rates, and revenue contribution from CDMO segment in quarterly results.
- 3. Debt Trajectory: Watch whether borrowings stabilise or continue rising. A borrowing-to-equity ratio crossing 0.30x would warrant heightened concern.
- 4. Receivables Quality: Track debtor days and provisioning for doubtful debts. A further increase in receivables without corresponding revenue growth is a red flag.
- 5. Medical Devices Transfer Completion: Monitor completion of the BTA with Morepen Medipath and receipt of the ₹197.10 Cr consideration, which could materially improve the cash position.
- 6. Margin Recovery: Track EBITDA margin trends — currently compressed by rising employee costs, distribution expenses, and finance costs.
- 7. Q2-Q4 FY27 Earnings Consistency: The Q1 FY27 recovery (+425% QoQ) needs to sustain over subsequent quarters to confirm it is not a one-off base effect.
Morepen Laboratories Limited Dividend – Conclusion
Morepen Laboratories’ ₹0.20 final dividend for FY2025-26 is a symbolic gesture rather than a meaningful income distribution. At a yield of just 0.17%, income-focused investors will find little value here. The company is in the midst of an ambitious transformation — pivoting to CDMO, hiving off its medical devices business, and exiting non-core subsidiaries — all financed by a 145% surge in borrowings. Core earnings (excluding a ₹25.83 Cr exceptional gain) declined approximately 40%, and free cash flow remains deeply negative at ₹–127.90 Crore. The dividend’s sustainability at ₹0.20 is intact given the modest outflow of ₹10.96 Crore, but growth in dividends is improbable until the capex cycle matures. This is a stock to evaluate for its CDMO growth potential, not for dividend income.
Frequently Asked Questions About Morepen Laboratories Limited Dividend
What dividend has Morepen Laboratories announced for FY2025-26?
What is the dividend yield of Morepen Laboratories?
What is the record date for Morepen Laboratories dividend?
What is the ex-dividend date for Morepen Laboratories?
When will Morepen Laboratories pay the dividend?
Who is eligible for Morepen Laboratories FY26 dividend?
How is Morepen Laboratories dividend taxed?
Is Morepen Laboratories dividend sustainable?
What is Morepen Laboratories dividend history?
What should investors monitor after Morepen Laboratories dividend?
Why is Morepen Laboratories paying a dividend despite negative free cash flow?
What is the impact of the Medical Devices hive-off on Morepen Laboratories dividend?
Disclaimer: This article is published by ShareBazaar Online for informational and educational purposes only. ShareBazaar Online is not a SEBI-registered investment advisor, research analyst, or portfolio manager. The content presented does not constitute investment advice, a buy/sell/hold recommendation, or a solicitation to trade in any security. All financial data has been sourced from the company’s SE Intimation filed on 26th May, 2026 (audited consolidated financial results) and publicly available sources including Screener.in and stock exchange websites. While every effort has been made to ensure accuracy, readers should independently verify all figures before making investment decisions. Past dividend performance is not indicative of future payouts. Investors should consult a qualified financial advisor before acting on any information in this article. ShareBazaar Online and its authors may or may not hold positions in the securities discussed.