
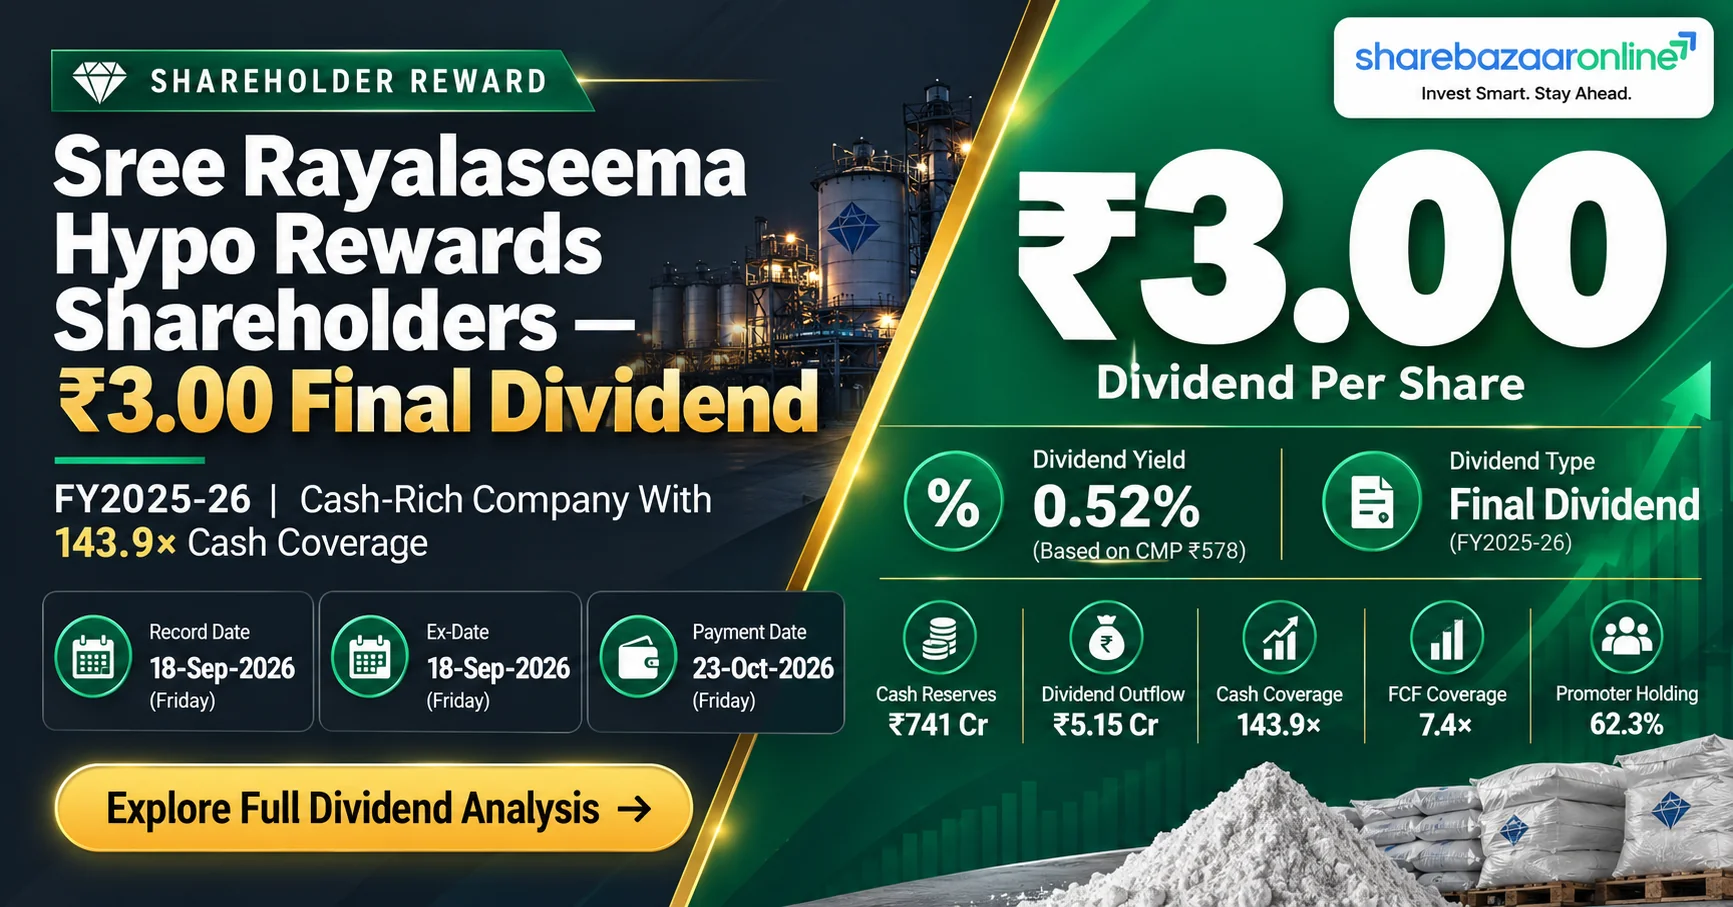
Dividend Snapshot – Sree Rayalaseema Hi-Strength Hypo Limited
Company Information
| Company | Sree Rayalaseema Hi-Strength Hypo Limited |
| NSE Symbol | SRHHYPOLTD |
| BSE Code | 532842 |
| ISIN | INE917H01012 |
| Face Value | ₹10 |
| Sector | Commodity Chemicals |
Dividend Details
| Dividend Type | Final Dividend |
| Dividend Per Share | ₹3.00 |
| Dividend % | 30% on Face Value |
| Financial Year | FY2025-26 |
| Dividend Yield (CMP) | ~0.52% |
| Total Outflow | ₹5.15 Crore |
Market Data
CMP (Sep 28, 2026)
₹579
Market Cap
₹994 Cr
P/E Ratio
10.1x
Book Value
₹566
Sree Rayalaseema Hi-Strength Hypo Limited – Company Overview
Sree Rayalaseema Hi-Strength Hypo Limited, part of the TGV Group, is India's only manufacturer of Calcium Hypochlorite and among very few globally. Incorporated in March 2005 and headquartered in Kurnool, Andhra Pradesh, the company produces industrial chemicals including sulphuric acid, chlorosulphonic acid, stable bleaching powder, sodium hydride, sodium methoxide, and water treatment chemicals.
The company operates through two segments: Chemicals (primary, over 90% of revenue) and Wind Energy – Power Generation. It also engages in coal trading. Sree Rayalaseema exports to multiple countries, with international revenue of ₹255.43 Crore in FY26 (38.3% of total revenue). Domestic revenue stood at ₹411.53 Crore. The company holds ISO 9001, 14001, and OHSAS 18001 certifications.
The company has a subsidiary – TGV Metals and Chemicals Private Limited – and holds a 22.31% stake in M V Salts & Chemicals Private Limited. Chairperson and Managing Director is Smt. T.G. Shilpa Bharath. The statutory auditor is S.T. Mohite & Co., who issued an unmodified (clean) opinion on both standalone and consolidated results.
Sree Rayalaseema Hi-Strength Hypo Limited – Financial Analysis
Consolidated P&L (FY26)
| Revenue from Operations | ₹667 Cr |
| Other Income | ₹54.79 Cr |
| Total Revenue | ₹721.75 Cr |
| EBITDA | ~₹95.49 Cr |
| PBT (before exceptional) | ₹134.35 Cr |
| Exceptional Items | –₹13.50 Cr |
| PAT (continuing ops) | ₹90.19 Cr |
| EPS (Basic) | ₹53.25 |
| OPM | ~13% |
Key Ratios (Consolidated)
| ROE | 10.5% |
| ROCE | 14.0% |
| Dividend Payout Ratio | 5.71% |
| Dividend Coverage | 17.75x |
| Debt-to-Equity | ~0.01 (almost debt-free) |
| P/E Ratio | 10.1x |
| P/B Ratio | ~1.0x |
| Revenue Growth (YoY) | +4.6% |
⚠ Exceptional Items Note
FY26 includes exceptional losses of ₹13.50 Crore — comprising ₹8.75 Crore loss on gold investment and ₹4.75 Crore derecognition of investment in debentures. Additionally, employee benefit expenses include ₹6.86 Crore from retrospective application of new labour code for gratuity obligations. These are non-recurring and should be adjusted when evaluating core earnings power.
Sree Rayalaseema Hi-Strength Hypo Limited – Dividend History
| Financial Year | DPS (₹) | EPS (₹) | Payout % | PAT (₹ Cr) | Type |
|---|---|---|---|---|---|
| FY2025-26 | 3.00 | 53.25 | 5.6% | 90.15 | Final |
| FY2024-25 | 3.00 | 52.47 | 5.7% | 87.47 | Final |
| FY2023-24 | 3.00 | 46.06 | 6.5% | 79.00 | Final |
| FY2022-23 | 3.50 | 89.86 | 3.9% | 154.00 | Final |
| FY2021-22 | 3.50 | 59.88 | 5.8% | 103.00 | Final |
| FY2020-21 | 3.00 | 35.29 | 8.5% | 61.00 | Final |
| FY2019-20 | 2.50 | 22.09 | 11.3% | 38.00 | Final |
| FY2016-17 | 1.50 | 5.64 | 26.6% | 9.00 | Final |
| FY2015-16 | 1.50 | 17.02 | 8.8% | 25.00 | Final |
Source: Company filings, Screener.in. Consolidated figures. DPS for FY23 and FY22 estimated from payout ratios.
Sree Rayalaseema Hi-Strength Hypo has maintained an unbroken dividend track record over the past decade, growing DPS from ₹1.50 in FY16 to ₹3.00 in FY26 — a CAGR of approximately 7%. The FY26 dividend of ₹3.00 is flat compared to FY25. The company reduced the dividend from ₹3.50 in FY23 to ₹3.00 in FY24, reflecting lower earnings. The payout ratio has consistently remained below 10%, indicating the company retains the vast majority of profits for growth and reserves. Classification: Consistent Payer with moderate growth.
Expert Commentary on Sree Rayalaseema Hi-Strength Hypo Dividend
The FY26 final dividend of ₹3.00 per share signals stability rather than growth. At a payout ratio of just 5.71%, Sree Rayalaseema retains ₹85 Crore of its ₹90 Crore profit for internal use. This is not a traditional dividend stock — it is primarily a capital appreciation play with a token dividend as a signal of financial health.
The real story lies in the company's ₹434 Crore cash pile (standalone) against a market cap of ₹994 Crore. Cash and investments together total approximately ₹741 Crore — representing nearly 75% of the market cap. The stock trades at just 1x book value and 10x earnings, suggesting either the market sees risks ahead or the company is deeply undervalued.
The ₹13.50 Crore exceptional loss (gold investment write-off and debenture derecognition) deserves scrutiny. Management deploying surplus cash into gold and debentures that subsequently lost value raises questions about capital allocation discipline. Shareholders should monitor whether these non-core investment losses become a recurring pattern.
Sree Rayalaseema Hi-Strength Hypo Limited – Future Outlook
Revenue growth turned positive in FY26 at +4.6% YoY after two years of decline (5-year revenue CAGR: -6%). The Q1 FY27 revenue of ₹211 Crore (up 17% YoY) suggests the recovery is accelerating. The chemicals segment benefits from steady demand for water treatment chemicals, bleaching powder, and calcium hypochlorite across domestic and export markets.
However, operating margins compressed to ~8% in Q4 FY26 from 15% in Q1 FY26, driven by higher material costs and other expenses. The company's ability to pass on input cost increases and maintain OPM above 12-13% will be critical for sustaining current earnings levels.
Given the conservative payout policy (sub-6%), dividends are likely to remain in the ₹3.00-3.50 range unless the company announces a special dividend or significantly changes its capital allocation framework. With ₹741 Crore in cash and investments sitting idle against a ₹994 Crore market cap, there is considerable scope for either increased dividends, buybacks, or expansion capex.
Sree Rayalaseema Hi-Strength Hypo Dividend Announcement Summary
The Board of Directors of Sree Rayalaseema Hi-Strength Hypo Limited, at their meeting held on May 30, 2026, recommended a final dividend of ₹3.00 per equity share (30% on face value of ₹10) for FY2025-26 ended March 31, 2026. The dividend was subject to shareholder approval at the Annual General Meeting.
The 21st AGM was held on September 26, 2026, where shareholders approved the dividend. The Board also approved standalone and consolidated audited financial results for Q4 and full year FY26, reappointed Nirmal Kumar Reddy & Co. as Internal Auditor, and Santosh & Associates as Cost Auditor for FY2026-27.
The total dividend outflow is approximately ₹5.15 Crore distributed among 1,71,64,800 equity shares. This represents 5.71% of consolidated PAT of ₹90.15 Crore. The announcement was signed by V. Surekha, Sr. GM & Company Secretary.
Sree Rayalaseema Hi-Strength Hypo Dividend – Key Dates Timeline
Announcement Date
30 May 2026
Board Meeting
Record Date
18 Sep 2026
Eligibility cutoff
Ex-Dividend Date
18 Sep 2026
T+1 settlement
Payment Date
On/before 23 Oct 2026
Credit to bank
Sree Rayalaseema Hi-Strength Hypo Dividend Yield Analysis
Yield Calculation
| DPS | ₹3.00 |
| CMP (Sep 28, 2026) | ₹579 |
| Announcement CMP (~May 30) | ~₹505 |
| Current Dividend Yield | 0.52% |
| Announcement Yield | 0.59% |
Yield Reality Check
The dividend yield of 0.52% is below the industry average of 0.7% for commodity chemicals (Source: SimplyWall.St). It is also below the market top quartile threshold of 1.3%.
The low yield is not due to a falling share price — the stock has risen 36.4% in 6 months. The yield is low because the company pays very little relative to its earnings (payout ratio: 5.71%). At ₹53.25 EPS with a ₹3 dividend, the company retains 94.4% of profits.
This is a low-yield stock by design, not by distress. Income-focused investors will find the yield insufficient.
Sree Rayalaseema Hi-Strength Hypo – Financial Performance Analysis
Operating Leverage Analysis (Consolidated)
| Metric | FY25 | FY26 | Change |
|---|---|---|---|
| Revenue | ₹638 Cr | ₹667 Cr | +4.6% |
| Operating Profit | ₹92 Cr | ₹88 Cr | –4.3% |
| OPM | 14% | 13% | –1pp |
| PAT | ₹87 Cr | ₹90 Cr | +3.4% |
Key finding: Revenue grew 4.6% but operating profit declined 4.3%, indicating margin compression. Material costs rose 18.5% YoY to ₹331.82 Cr, growing faster than revenue. Employee costs surged 18.9% to ₹40.90 Cr (partly due to ₹6.86 Cr retrospective gratuity charge). PAT still grew 3.4% due to higher other income (₹54.79 Cr vs ₹39.47 Cr) offsetting weaker operational performance.
Sree Rayalaseema Hi-Strength Hypo – Cash Flow Analysis
Consolidated Cash Flows (₹ Crore)
| Component | FY24 | FY25 | FY26 |
|---|---|---|---|
| Operating Cash Flow (OCF) | ₹140 Cr | ₹65 Cr | ₹39 Cr |
| Free Cash Flow (FCF) | ₹120 Cr | ₹63 Cr | ₹38 Cr |
| PAT | ₹79 Cr | ₹87 Cr | ₹90 Cr |
| OCF/PAT Ratio | 177% | 75% | 43% |
⚠ Cash Flow Quality Deterioration
FY26 OCF of ₹39 Crore against PAT of ₹90 Crore represents a concerning OCF/PAT ratio of just 43%. This means less than half of reported profits converted to cash. The primary drags were: increase in other non-current assets (₹12.03 Cr), increase in other current assets (₹19.60 Cr), and inventory build-up (₹10.40 Cr). While the profit on paper looks healthy, the cash generation has weakened significantly from FY24 levels (177%). This is a critical monitoring point.
Sree Rayalaseema Hi-Strength Hypo – Balance Sheet Strength
Consolidated Balance Sheet (Mar 2026)
| Total Assets | ₹1,115 Cr |
| Total Equity | ₹984 Cr |
| Total Borrowings | ₹0.39 Cr |
| Cash & Equivalents | ₹434.16 Cr |
| Investments | ₹306.81 Cr |
| Cash + Investments | ₹740.97 Cr |
| Net Cash Position | ₹433.77 Cr (Net Cash) |
Balance Sheet Assessment
The balance sheet is exceptionally strong. With just ₹0.39 Crore in borrowings against ₹434 Crore in cash, the company is effectively debt-free. Cash and investments of ₹741 Crore represent 75% of market cap — an unusual position for a manufacturing company.
Cash coverage of dividend is 143.9x. Even if profits dropped to zero, the company could pay the current dividend for over 140 years from existing cash alone.
However, the large cash hoard also raises questions about capital allocation efficiency. Returns on this cash (interest and investment income) have been modest relative to the corpus size.
Sree Rayalaseema Hi-Strength Hypo – Dividend Sustainability Analysis
Payout Ratio
5.71%
Very Low
EPS Coverage
17.75x
Excellent
FCF Coverage
7.4x
Strong
Cash Coverage
143.9x
Fortress
Funded through: Current earnings. The dividend of ₹5.15 Crore is comfortably covered by PAT of ₹90.15 Crore, FCF of ₹38 Crore, and a massive cash reserve. There is no evidence of the dividend being funded through borrowings or asset sales.
Debt position: Borrowings are declining (₹16 Cr in FY25 → ₹0.39 Cr in FY26). The company is not increasing debt to pay dividends.
Earnings trend: PAT grew 3.4% YoY. Revenue is recovering after two years of decline. Earnings remain positive and stable.
Sustainability Classification: SUSTAINABLE ✓
Sree Rayalaseema Hi-Strength Hypo – Peer Comparison
| Metric | SRHHYPOLTD | Industry Avg | Assessment |
|---|---|---|---|
| Dividend Yield | 0.52% | 0.7% | Below average |
| P/E Ratio | 10.1x | 26.35x | Significantly cheaper |
| P/B Ratio | ~1.0x | 2.04x | 49% discount to peers |
| ROCE | 14.0% | ~15-18% | Slightly below |
| Debt/Equity | ~0.01 | 0.3-0.5 | Debt-free |
| Payout Ratio | 5.7% | 15-25% | Very conservative |
Source: Screener.in, Value Research Online (as of Sep 2026). Industry: Commodity Chemicals.
Sree Rayalaseema trades at a 57% discount to peer median P/E and a 49% discount on P/B. While this looks cheap, the discount partly reflects its small-cap nature (₹994 Cr market cap), low liquidity, and declining 5-year revenue CAGR of -6%. The dividend yield is below industry average due to the ultra-conservative payout policy, not a valuation issue. Among chemical manufacturers, the company's balance sheet strength and debt-free status are genuine competitive advantages.
Sree Rayalaseema Hi-Strength Hypo – Promoter Impact Analysis
Shareholding Pattern (Jun 2026)
| Promoter Holding | 61.84% |
| Promoter Pledge | 0.00% (NIL) |
| FII Holding | 0.06% |
| DII Holding | 0.05% |
| Public Holding | 38.06% |
Promoter Dividend Income
| Promoter Shares | 10,61,560 shares (61.84%) |
| Promoter Dividend Income | ₹31.85 Lakhs (₹0.32 Cr) |
| Minority Dividend Income | ₹19.65 Lakhs (₹0.20 Cr) |
| Promoter's Share of PAT | ₹55.75 Cr (retained) |
Promoters receive ₹3.18 Crore in dividends but benefit from ₹55.75 Crore in retained earnings that increase book value. The promoter family benefits far more from capital appreciation than dividend payouts.
Sree Rayalaseema Hi-Strength Hypo Dividend – Taxation Analysis
Indian Dividend Tax Rules
Dividends are taxable in the hands of shareholders at their applicable income tax slab rate. Companies deduct TDS at 10% if dividend income exceeds ₹5,000 in a financial year. NRI shareholders face 20% TDS plus applicable surcharge and cess.
Worked Example: 1,000 Shares, 30% Tax Slab
| Shares Held | 1,000 |
| DPS | ₹3.00 |
| Gross Dividend | ₹3,000 |
| TDS (10%) | ₹300 (deducted if total >₹5,000) |
| Tax at 30% Slab + 4% Cess | ₹936 |
| Net Dividend After Tax | ₹2,064 |
| Effective Post-Tax Yield (CMP ₹579) | 0.36% |
TDS paid can be adjusted against total tax liability at the time of ITR filing. Effective yield after maximum tax is only 0.36%, making this unattractive for income-seeking investors in the highest tax bracket.
Sree Rayalaseema Hi-Strength Hypo Dividend – Key Risks
- 1Revenue Cyclicality: 5-year revenue CAGR is -6%. The chemicals business is highly cyclical, and revenue dropped from ₹1,650 Crore (FY23) to ₹667 Crore (FY26) — a 60% decline in three years. Future revenue recovery is not guaranteed.
- 2Cash Flow Quality Weakness: FY26 OCF/PAT ratio dropped to 43% from 177% in FY24. If cash flow quality continues deteriorating, even the small dividend could come under pressure despite strong paper profits.
- 3Non-Core Investment Losses: ₹13.50 Crore in exceptional losses from gold and debenture investments indicates treasury management risk. The company holds ₹307 Crore in investments — further mark-to-market losses are possible.
- 4Margin Compression: Q4 FY26 OPM fell to ~8% from 15% in Q1. Raw material cost inflation, higher employee costs (new labour code), and other expenses are squeezing margins. This may impact future earnings.
- 5Export Concentration Risk: International revenue declined from ₹285.94 Cr (FY25) to ₹255.43 Cr (FY26), a 10.7% drop. Global trade disruptions (the Maersk shipping litigation is an example) and currency volatility can materially impact the export business.
- 6Low Liquidity: With negligible FII (0.06%) and DII (0.05%) ownership and small-cap status, the stock has low trading liquidity, making it vulnerable to sharp price moves and difficult to exit during market stress.
- 7Capital Allocation Concern: ₹741 Crore in cash and investments (75% of market cap) sitting idle suggests sub-optimal capital deployment. The company could be earning better returns through expansion, buybacks, or higher dividends rather than accumulating treasury assets.
Sree Rayalaseema Hi-Strength Hypo – What To Monitor
- 1OCF/PAT Recovery: The 43% OCF/PAT ratio in FY26 is a critical red flag. Monitor whether FY27 quarterly cash flows show improvement back towards 80-100% conversion.
- 2Operating Margin Trajectory: Track quarterly OPM — if it consistently stays below 12%, the revenue recovery is not translating to profitability improvement.
- 3Revenue Recovery Momentum: Q1 FY27 showed ₹211 Cr revenue (+17% YoY). Watch if this trajectory sustains across Q2-Q4, especially export revenue which declined in FY26.
- 4Investment Portfolio Performance: The ₹307 Crore investment portfolio generated ₹13.50 Crore in exceptional losses in FY26. Track whether management reduces non-core investments or whether further mark-to-market losses emerge.
- 5Capital Allocation Announcements: Any announcement of capacity expansion, buyback, special dividend, or strategic acquisition from the ₹741 Crore cash pile would be a significant catalyst.
- 6Promoter Holding Stability: Promoters hold a stable 61.84% with zero pledge. Any change in promoter holding direction would be significant for the investment thesis.
- 7Maersk Litigation Outcome: The UK commercial court proceedings initiated by Maersk Shipping Line could have financial implications. Monitor corporate announcements for updates.
Sree Rayalaseema Hi-Strength Hypo Dividend – Conclusion
Sree Rayalaseema Hi-Strength Hypo Limited's ₹3.00 final dividend for FY26 is a sustainable but modest payout from a financially strong company. At a 5.71% payout ratio, 17.75x earnings coverage, and ₹741 Crore cash pile, the dividend is among the safest on the market — but the yield of 0.52% is too low for income investors.
Positives: Debt-free balance sheet, consistent dividend track record (10+ years), massive cash reserves, stock trading below book value (P/B ~1.0x), revenue recovery in progress, and unmodified audit opinion.
Negatives: Deteriorating cash flow quality (OCF/PAT at 43%), margin compression in Q4, exceptional investment losses (₹13.50 Cr), 5-year revenue CAGR of -6%, ultra-low dividend yield, negligible institutional interest, and sub-optimal capital allocation with excess cash earning modest returns.
The investment case hinges on whether you believe the company will eventually deploy its ₹741 Crore cash hoard productively — through expansion, acquisitions, buybacks, or substantially higher dividends — or continue letting it accumulate at low returns. At 10x earnings with a fortress balance sheet, the margin of safety exists, but catalysts for re-rating remain uncertain.
Frequently Asked Questions About Sree Rayalaseema Hi-Strength Hypo Dividend
What dividend has Sree Rayalaseema Hi-Strength Hypo announced for FY2025-26?
What is the dividend yield of SRHHYPOLTD at the current share price?
What is the record date for Sree Rayalaseema Hi-Strength Hypo FY26 dividend?
What is the ex-dividend date for SRHHYPOLTD FY26 dividend?
When will the Sree Rayalaseema dividend be paid?
Who is eligible for Sree Rayalaseema Hi-Strength Hypo FY26 dividend?
How is the SRHHYPOLTD dividend taxed in India?
Is the Sree Rayalaseema Hi-Strength Hypo dividend sustainable?
What is the dividend history of Sree Rayalaseema Hi-Strength Hypo?
What should investors monitor about SRHHYPOLTD going forward?
What is the face value of Sree Rayalaseema Hi-Strength Hypo shares?
Why is Sree Rayalaseema Hi-Strength Hypo's dividend yield so low despite strong profits?
Disclaimer
This article is published by ShareBazaar Online for educational and informational purposes only. It does not constitute investment advice, a recommendation to buy, sell, or hold any securities, or an offer of any financial product. All data has been sourced from company filings, stock exchanges, Screener.in, Value Research Online, SimplyWall.St, and other publicly available sources. While every effort has been made to ensure accuracy, ShareBazaar Online does not guarantee the completeness or timeliness of the information. Past performance is not indicative of future results. Investors should consult a qualified financial advisor before making any investment decisions. Dividend payments are subject to board approval, regulatory compliance, and shareholder authorization. Tax implications vary by individual circumstances. ShareBazaar Online, its authors, and affiliates may or may not hold positions in the securities discussed.