
Apeejay Surrendra Park Hotels Dividend 2026: ₹0.75 Final Dividend, 0.72% Real Yield and a Debt-Funded Expansion Year
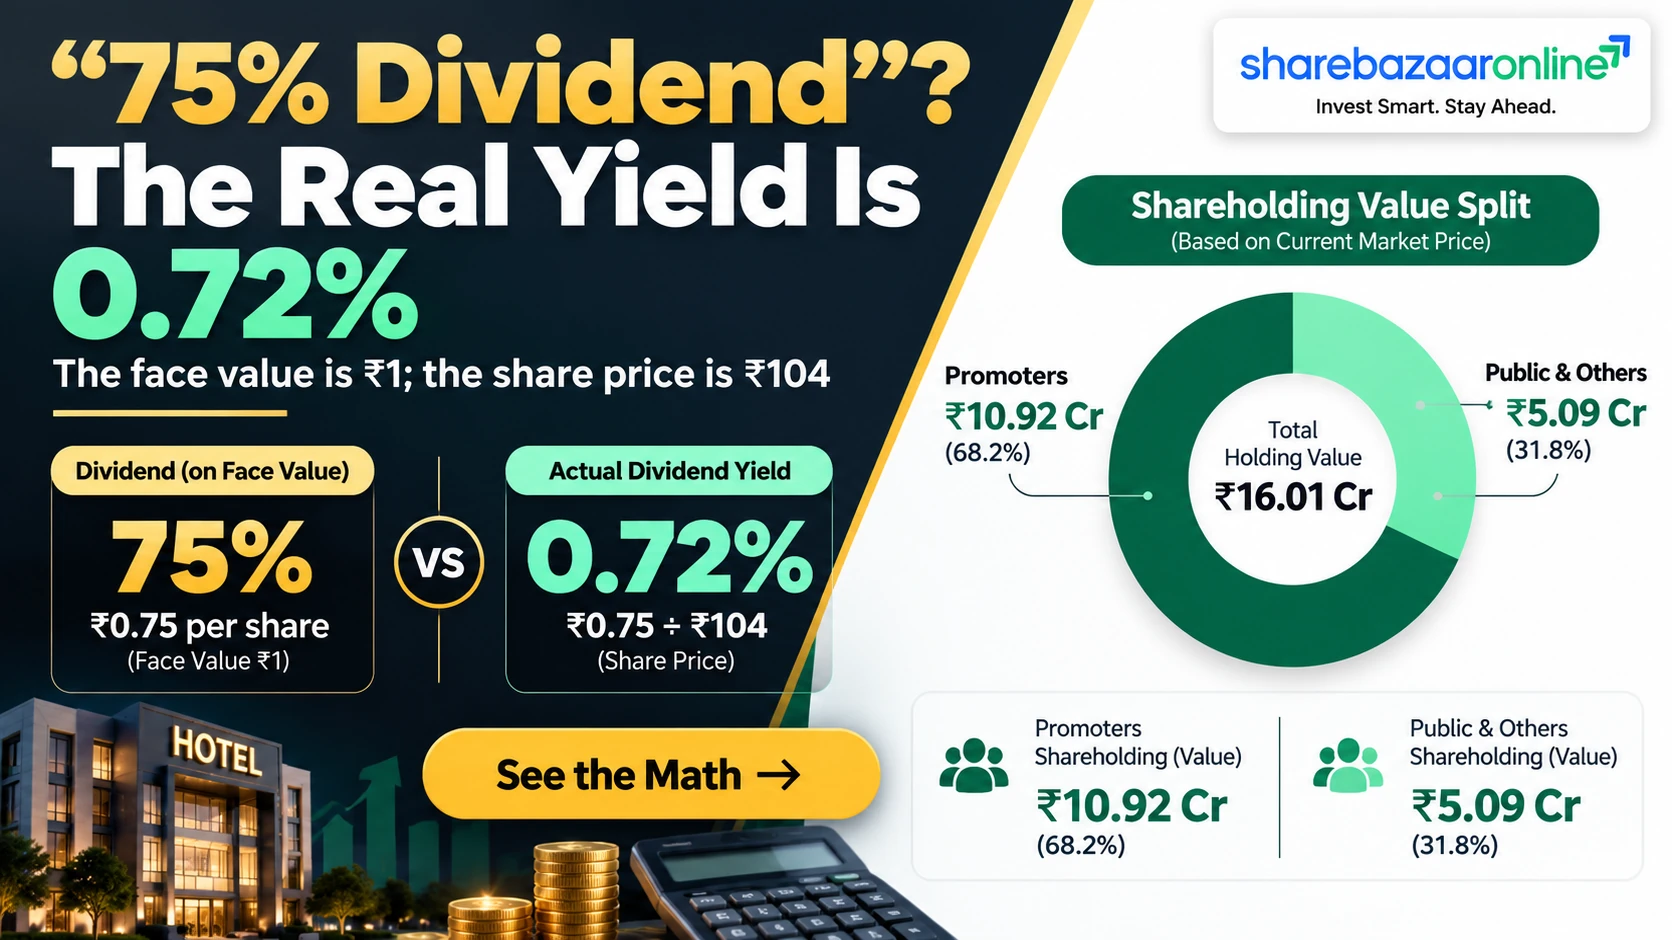
Apeejay Surrendra Park Hotels Limited (NSE: PARKHOTELS, BSE: 544111) declared a final dividend of ₹0.75 per share for FY2025-26, headlined as a 75% dividend. That 75% is calculated on the ₹1 face value. At the current price of ₹104, the real Park Hotels dividend yield is only 0.72%. This analysis checks whether the payout is backed by cash, and finds that it came in a year when consolidated profit fell 21.4% and gross borrowings rose 3.5 times.
Apeejay Surrendra Park Hotels Limited – Company Overview
Business Profile
Apeejay Surrendra Park Hotels Limited was incorporated in 1987 and has its head office on Park Street, Kolkata. It runs upscale and upper-midscale hotels under five brands: THE Park, THE Park Collection, Zone by The Park, Zone Connect and Stop by Zone. It also owns Flurys, the retail patisserie and cafe chain. The company reported 42 hotels across 32 cities in its Q4 FY26 update (Source: Groww).
Listing Snapshot
- ISIN: INE988S01028
- Listed: February 2024 at an IPO price of ₹155
- Face value: ₹1; shares: 21.34 crore
- Market cap: ₹2,210 crore (Screener, 28-09-2026)
- Promoter holding: 68.21% (June 2026)
Apeejay Surrendra Park Hotels Limited Financial Analysis: Multi-Year Trend
| Consolidated (₹ Cr) | FY23 | FY24 | FY25 | FY26 |
|---|---|---|---|---|
| Revenue | 510 | 579 | 631 | 707 |
| Net Profit | 48 | 69 | 84 | 66 |
| EPS (₹) | 2.75 | 3.22 | 3.92 | 3.08 |
| Borrowings | 617 | 100 | 168* | 373* |
Source: Screener.in. *Screener borrowings include lease liabilities. Excluding leases, the filing shows gross debt of ₹73.20 Cr (FY25) and ₹257.29 Cr (FY26).
Revenue has grown every year since FY23, at a 3-year CAGR of about 11%. Profit grew until FY25 and then fell to ₹65.72 crore in FY26. The IPO money cut debt sharply in FY24. In FY26, borrowing went back up to pay for hotel acquisitions.
Apeejay Surrendra Park Hotels Limited Dividend History Table
| Financial Year | Type | DPS (₹) | % of FV | Outflow (₹ Cr) | Payout (Cons.) |
|---|---|---|---|---|---|
| FY2025-26 | Final | 0.75 | 75% | 16.01 | 24.36% |
| FY2024-25 | Final | 0.50 | 50% | 10.67 | 12.76% |
| FY2017-18 to FY2023-24 | None | Nil | – | – | 0% |
Sources: company filing (FY26), cash flow statement "dividend paid" ₹10.67 Cr (FY25 dividend), Screener.in payout history. There have been no bonus issues or splits since listing, so no Ind AS 33 restatement is needed.
Expert Commentary on the Apeejay Surrendra Park Hotels Limited Dividend
The Headline vs the Reality
A 50% dividend increase in a year when profit fell 21.4% looks generous. The main reason is that FY25 profit included a ₹8.75 crore one-time insurance claim for loss of profit. That makes FY25 look stronger than the underlying business was. Excluding the claim, profit before tax and exceptional items fell 14.3%, not 19.3%.
The Cash Question
Operating cash flow of ₹181.51 crore was 2.76 times reported profit, so cash generation is strong. But capex of ₹286.95 crore, which includes the Juhu, Mumbai hotel, pushed free cash flow to −₹105.44 crore. Because cash is fungible, part of this dividend was in effect paid alongside new borrowing.
Apeejay Surrendra Park Hotels Limited Future Outlook
The company is in an asset-heavy expansion phase. In FY26 it acquired the Juhu, Mumbai hotel company for ₹224.76 crore and a Kerala hotel for ₹20.50 crore. It has also signed an agreement for Malabar House, Kochi, which was pending conditions precedent as of March 2026. At a September 2026 investor meet, management spoke of reaching 87 hotels by FY30 (Source: Groww). That is company guidance and has not been verified.
The dividend outlook depends on whether these new hotels start earning quickly enough to repay the new debt. Q1 FY27 net profit was about ₹11 crore, compared with ₹13 crore a year earlier (Screener.in). Near-term earnings momentum remains soft.
Dividend Snapshot – Apeejay Surrendra Park Hotels Limited
- Dividend type: Final Dividend, FY2025-26
- Dividend per share: ₹0.75 (75% of ₹1 face value)
- Total outflow: ₹16.01 crore (filing)
- Record date: 19-09-2026
- Yield at CMP ₹104: 0.72%
- Yield at announcement (₹123.33): 0.61%
- Consolidated payout ratio: 24.36%
- EPS cover: 4.11x
The 75% headline is 104 times the actual market yield. This happens because the percentage is measured against a ₹1 face value, not the ₹104 share price. For every ₹1,000 invested at the current price, the dividend comes to about ₹7.21 before tax.
Apeejay Surrendra Park Hotels Limited Dividend Announcement Summary
The Board met on 26 May 2026 (6:45 PM to 11:00 PM, after market hours). It approved the audited Q4 and FY26 results and recommended a final dividend of Re. 0.75 per fully paid-up equity share of face value Re. 1. The filing states the total dividend at ₹16.01 crore. Our check, 21.34 crore shares × ₹0.75, gives ₹16.005 crore, which matches.
The dividend needed shareholder approval at the 38th AGM, held on 26 September 2026. The company said it would credit the dividend within 30 days of the AGM. S.R. Batliboi & Co. LLP, the statutory auditor, gave an unmodified opinion on both the standalone and consolidated results.
Apeejay Surrendra Park Hotels Limited Dividend Record Date and Key Dates Timeline
| Board Announcement | 26-05-2026 |
| Ex-Dividend Date | 18-09-2026 (Friday)* |
| Record Date | 19-09-2026 (Saturday) |
| 38th AGM | 26-09-2026 |
| Payment (latest date) | On or before 26-10-2026 |
*The record date fell on a Saturday. Under India's T+1 settlement, the ex-date is the last trading day before it, which was Friday 18 September. Market aggregators also show 18 September. This date is inferred and should be checked against the NSE corporate-action circular. Investors who held shares at the close of 17 September 2026 were eligible. The payment date is the 30-day deadline after the AGM, not a date the company has announced.
Apeejay Surrendra Park Hotels Limited Dividend Yield Analysis
Four Ways to Read the Yield
- On face value (₹1): 75%, which is misleading
- At announcement close (₹123.33): 0.61%
- At current price (₹104): 0.72%
- At IPO price (₹155): 0.48%
Yield Reality Check
The yield rose from 0.61% to 0.72% mainly because the share price fell 15.7% after the announcement, not because of a stronger payout. The stock trades 32.9% below its IPO price. Readers should treat the higher yield as partly a sign of a weaker share price, not only of shareholder reward.
Apeejay Surrendra Park Hotels Limited Dividend History Analysis
Apeejay Surrendra Park Hotels Limited has only a two-year dividend record: ₹0.50 for FY25 and ₹0.75 for FY26. Before listing it paid no dividend from FY18 to FY24. Those years included losses in FY18, FY21 and FY22, and heavy debt before the IPO.
The 50% increase in DPS is real. The payout ratio also roughly doubled, from 12.76% to 24.36%, because the dividend rose while profit fell. There have been no special dividends, cuts or interim payouts.
Classification: Irregular Payer (early-stage). Two consecutive payouts point to a new policy of paying dividends, but that is not yet a track record.
Apeejay Surrendra Park Hotels Limited Dividend vs Profit Growth: FY26 Performance
| Line Item (₹ Cr) | FY25 | FY26 | Change |
|---|---|---|---|
| Revenue from operations | 631.45 | 707.28 | +12.01% |
| Operating EBITDA (ex other income) | 208.42 | 218.02 | +4.61% |
| Other expenses | 202.58 | 239.30 | +18.13% |
| Finance costs | 20.44 | 29.89 | +46.23% |
| Depreciation | 61.77 | 74.38 | +20.41% |
| Net profit | 83.60 | 65.72 | −21.39% |
This is negative operating leverage: revenue grew, but costs grew faster. Operating EBITDA margin fell from 33.0% to 30.8%. Other income fell from ₹21.90 crore to ₹5.72 crore. The effective tax rate stayed high at 43.2%. Net profit margin fell from 13.2% to 9.3%.
Apeejay Surrendra Park Hotels Limited Cash Flow Analysis
Operating Cash Is Strong
OCF was ₹181.51 crore, which is 2.76x PAT and 81% of EBITDA. Part of the gap comes from non-cash items: depreciation of ₹74.38 crore and a deferred tax charge of ₹27.17 crore. Trade receivables grew 7.64%, slower than revenue at 12.01%, so collections look healthy.
Free Cash Flow Is Negative
Capex of ₹286.95 crore was 1.58x OCF, leaving FCF at −₹105.44 crore. Net new borrowing was ₹178.45 crore (₹259.52 Cr raised minus ₹81.07 Cr repaid). The dividend is funded by current earnings and operating cash, but the company is also borrowing to cover the shortfall after capex.
Apeejay Surrendra Park Hotels Limited Balance Sheet Strength
Debt Build-Up
- Gross debt (ex-lease): ₹73.20 Cr → ₹257.29 Cr
- Net debt: −₹3.78 Cr (net cash) → ₹155.89 Cr
- Lease liabilities: ₹115.60 Cr
- Debt-to-equity: 0.19x
- Net debt/EBITDA: 0.70x
Liquidity and Equity
- Cash + bank + liquid MFs: ₹101.40 Cr
- Equity (parent): ₹1,342.32 Cr
- Interest cover (EBIT/finance cost): 4.87x
- ROE: 5.0%; ROCE: 9.84% (computed)
Leverage is still low in absolute terms. The concern is the direction: the company moved from net cash to net debt within one year. This year's dividend equals about 6.2% of gross debt.
Apeejay Surrendra Park Hotels Limited Dividend Sustainability Analysis
| Test | Result | Verdict |
|---|---|---|
| Earnings cover (EPS/DPS) | 4.11x | Pass |
| OCF cover | 11.34x | Pass |
| FCF cover | −6.59x | Fail |
| Cash & investments cover | 6.34x | Pass |
Verdict: Moderately Sustainable. At ₹16.01 crore, the dividend is small compared with operating cash flow, so paying it is not a strain. The weak point is expansion: debt grew 3.5x while the dividend was increased 50%. If new hotels are slow to earn, the company may choose to protect debt repayment and cash rather than raise the dividend again.
Apeejay Surrendra Park Hotels Limited vs Hotel Peers: Dividend Comparison
| Company | Yield | FY26 Payout | ROE | ROCE |
|---|---|---|---|---|
| Apeejay Surrendra Park Hotels | 0.72% | 24% | 5.1% | 9.4% |
| EIH Ltd | 0.51% | 15% | 14.5% | 20.7% |
| Indian Hotels Co | 0.46% | 22% | 14.2% | 17.1% |
| Chalet Hotels | 0.23% | 7% | 19.0% | 17.0% |
| Lemon Tree Hotels | 0.00% | 0% | 19.2% | 14.1% |
Source: Screener.in, prices as of 25–28 September 2026. Peer ratios are consolidated, as reported by Screener.
Apeejay Surrendra Park Hotels has the highest yield and the highest payout ratio in this group, but the lowest ROE and ROCE. In other words, it pays out a larger share of lower returns. Its larger peers are more profitable and pay out a smaller share of earnings.
Apeejay Surrendra Park Hotels Limited Promoter Impact Analysis
Who Receives the ₹16.01 Crore
- Promoters (68.21%): ₹10.92 Cr
- Public / retail (18.91%): ₹3.03 Cr
- DIIs (8.81%): ₹1.41 Cr
- FIIs (4.07%): ₹0.65 Cr
Based on the June 2026 shareholding pattern (Screener.in).
Distribution Impact
About two-thirds of the payout goes to the Apeejay Surrendra promoter group. Minority holders receive only ₹0.75 per share against a price of ₹104. DII ownership fell from 16.42% to 8.81% between March 2024 and June 2026, while retail ownership rose to 18.91%. Because promoters own such a large stake, it is in their interest to keep paying a regular dividend.
Apeejay Surrendra Park Hotels Limited Dividend Taxation Analysis
Rules
Dividends are taxed at your income-tax slab rate under "Income from Other Sources". For resident shareholders, the company deducts 10% TDS under Section 194 if dividends from it exceed ₹10,000 in a financial year. For NRIs, TDS is 20% plus surcharge and cess, or the lower DTAA rate if eligible.
Worked Example (30% slab)
- 1,000 shares × ₹10 hypothetical DPS = ₹10,000 gross
- Tax @30% = ₹3,000; cess @4% = ₹120
- Net dividend = ₹6,880
- Actual Park Hotels case: 1,000 shares × ₹0.75 = ₹750 gross, ₹516 net
- Effective post-tax yield at ₹104: 0.50% (vs 0.72% pre-tax)
Key Risks for Apeejay Surrendra Park Hotels Limited Shareholders
- Margin compression: operating EBITDA margin fell 2.2 percentage points as other expenses grew 18.1%.
- Rising leverage: gross debt rose 3.5x and finance costs rose 46.2%.
- Negative FCF: the ₹245.26 crore of FY26 acquisitions has to start earning before the debt can be reduced.
- Tax exposure: a ₹41.1 crore income-tax demand for AY 2024-25, which the company is appealing (Source: Groww), on top of a 43% effective tax rate.
- Leadership change: CFO Atul Khosla resigned; Manish Bhagat took over from 21-09-2026 (Source: Groww).
- Earnings momentum: Q1 FY27 PAT was lower than a year earlier.
What To Monitor at Apeejay Surrendra Park Hotels Limited
- Q2 FY27 results: the trading window closed on 1 October 2026. Check whether operating EBITDA margin returns towards 33%.
- Juhu hotel launch: when it starts commercial operations and how fast it ramps up. The purchase of the remaining 10% is tied to one year after launch.
- Net debt trend: whether it stays below 1x EBITDA.
- Malabar House deal: whether the conditions precedent are met and what cash it requires.
- Tax appeal: the outcome of the ₹41.1 crore demand.
- Dividend payment: confirmation that the dividend was credited by 26-10-2026.
Apeejay Surrendra Park Hotels Limited Dividend: Conclusion
Positives
- DPS up 50%; second payout in a row
- OCF covers the dividend 11.3x
- Highest yield among the listed hotel peers covered here
Negatives
- PAT down 21.4%; ROE only 5%
- FCF of −₹105 crore; moved from net cash to net debt
- Real yield of 0.72%, not the 75% headline
Apeejay Surrendra Park Hotels Limited has raised its dividend while it spends heavily on expansion. The dividend is affordable from operating cash. Whether it can grow further depends on the newly acquired hotels starting to earn.
Frequently Asked Questions About the Apeejay Surrendra Park Hotels Limited Dividend
What dividend has Apeejay Surrendra Park Hotels announced for FY2025-26?
What is the Park Hotels dividend yield?
What was the record date for the Park Hotels dividend?
What was the ex-dividend date?
When will the dividend be paid?
Who was eligible for the dividend?
How is the Park Hotels dividend taxed?
Is the Apeejay Surrendra Park Hotels dividend sustainable?
What is the Park Hotels dividend history?
Why did the dividend rise when profit fell?
How much do promoters receive from this dividend?
What should investors monitor next?
Disclaimer – Apeejay Surrendra Park Hotels Limited Dividend Analysis
This article is for educational and informational purposes only. It is not investment advice or a recommendation to buy, sell or hold any security. ShareBazaar Online is not a SEBI-registered investment adviser or research analyst. Figures come from the company's audited results filed on 26 May 2026 and from third-party sources cited in the text; market data may have changed since publication. Dates marked as inferred should be checked against official exchange circulars. Please consult a SEBI-registered adviser before making investment decisions.