
Gujarat Alkalies and Chemicals Limited – Company Overview
Gujarat Alkalies and Chemicals Limited (GACL) was set up in 1973 at Vadodara and is promoted by the Government of Gujarat. It is one of India's largest caustic soda producers. Capacity has grown from 37,425 TPA at inception to 852,400 TPA across four complexes, two at Vadodara and two at Dahej.
GACL sells more than 35 products, including caustic soda, liquid chlorine, hydrochloric acid, chloromethanes, hydrogen peroxide and phosphoric acid. Its customers are in textiles, paper, alumina, detergents, pharma and water treatment. The company reports a single "Chemicals" segment. Its consolidated results include a 60% joint venture, GACL-NALCO Alkalies & Chemicals Pvt Ltd (GNAL), and 26% associates.
NSE Symbol / BSE Code
GUJALKALI / 530001
ISIN / Face Value
INE186A01019 / ₹10
Gujarat Alkalies and Chemicals Limited Financial Analysis (Consolidated)
| Metric (₹ Cr) | FY22 | FY23 | FY24 | FY25 | FY26 |
|---|---|---|---|---|---|
| Revenue | 3,759 | 4,516 | 3,807 | 4,073 | 4,358 |
| Operating Margin | 26% | 21% | 0.8% | 7% | 9% |
| Net Profit | 560 | 410 | -237 | -65 | -2.41 |
| EPS (₹) | 76.22 | 55.78 | -32.25 | -8.87 | -0.33 |
Source: Screener.in consolidated data; FY26 from company filing dated 29 May 2026.
After FY23 the chlor-alkali down-cycle took operating margin from 21% to 0.8%, and GACL has booked consolidated losses for three straight years. FY26 came close to breakeven, with a net loss of ₹2.41 Cr. The June 2026 quarter was the first clear turn: consolidated PAT was ₹54.98 Cr on sales of ₹1,244.91 Cr, against a loss of ₹13.78 Cr a year earlier.
Gujarat Alkalies and Chemicals Limited Dividend History Table
| Financial Year | DPS (₹) | % of FV | Cons. EPS (₹) | Payout | Outflow (₹ Cr) |
|---|---|---|---|---|---|
| FY26 | 17.70 | 177% | -0.33 | Loss year | 129.98 |
| FY25 | 15.80 | 158% | -8.87 | Loss year | 116.03 |
| FY24 | 13.85 | 138.5% | -32.25 | Loss year | 101.71 |
| FY23 | 23.55 | 235.5% | 55.78 | 42.2% | 172.94 |
| FY22 | 10.00 | 100% | 76.22 | 13.1% | 73.44 |
| FY21 | 8.00 | 80% | 22.57 | 35.4% | 58.75 |
| FY20 | 8.00 | 80% | 45.22 | 17.7% | 58.75 |
| FY19 | 8.00 | 80% | 93.98 | 8.5% | 58.75 |
| FY18 | 6.50 | 65% | 72.78 | 8.9% | 47.73 |
| FY17 | 5.00 | 50% | 41.85 | 11.9% | 36.72 |
| FY16 | 4.50 | 45% | 29.90 | 15.1% | 33.05 |
Source: exchange dividend records (via TipRanks) and Screener.in EPS. Outflow computed on 7,34,36,928 shares. Equity capital has stayed at ₹73.44 Cr throughout, so no bonus or split restatement is needed.
Expert Commentary on the Gujarat Alkalies and Chemicals Limited Dividend
The company's own press note is candid. Managing Director Avantika Singh said the ₹17.70 dividend is "payable partly from current year profit and partly from free reserves." The numbers show how much is reserves. The outflow is ₹129.98 Cr against standalone PAT of ₹20.84 Cr, so about ₹109.14 Cr, roughly 84% of the payout, comes from past retained earnings.
Capital allocation lens: The same cash could have cut borrowings of ₹567.63 Cr by about 23%, or funded the newly approved ₹67 Cr hydrogen peroxide plant almost 1.9 times. No buyback was considered. Raising the dividend by 12.0% during a loss year reads as a board signal of confidence in the FY27 recovery. The dividend is not supported by FY26 earnings.
Gujarat Alkalies and Chemicals Limited Future Outlook
For FY27, management plans to commission an HCl synthesis unit, a chlorotoluene downstream plant, a caustic soda flaking plant, cell-element replacements and 138.60 MW of renewable energy projects. The board also approved a 5,000 TPA high-purity hydrogen peroxide plant (₹67 Cr) aimed at semiconductor and solar customers.
Renewable power rose to 35.7% of the energy mix from 29.7%. More capacity is due from a 75.9 MW Clean Max hybrid project and a 62.7 MW Aditya Birla supply expected in H2 FY27. If Q1 FY27 EPS of ₹7.49 were simply annualised, it would give ₹29.96, or 1.69x the dividend. That is an arithmetic illustration, not a forecast.
Dividend Snapshot – Gujarat Alkalies and Chemicals Limited
Dividend Per Share
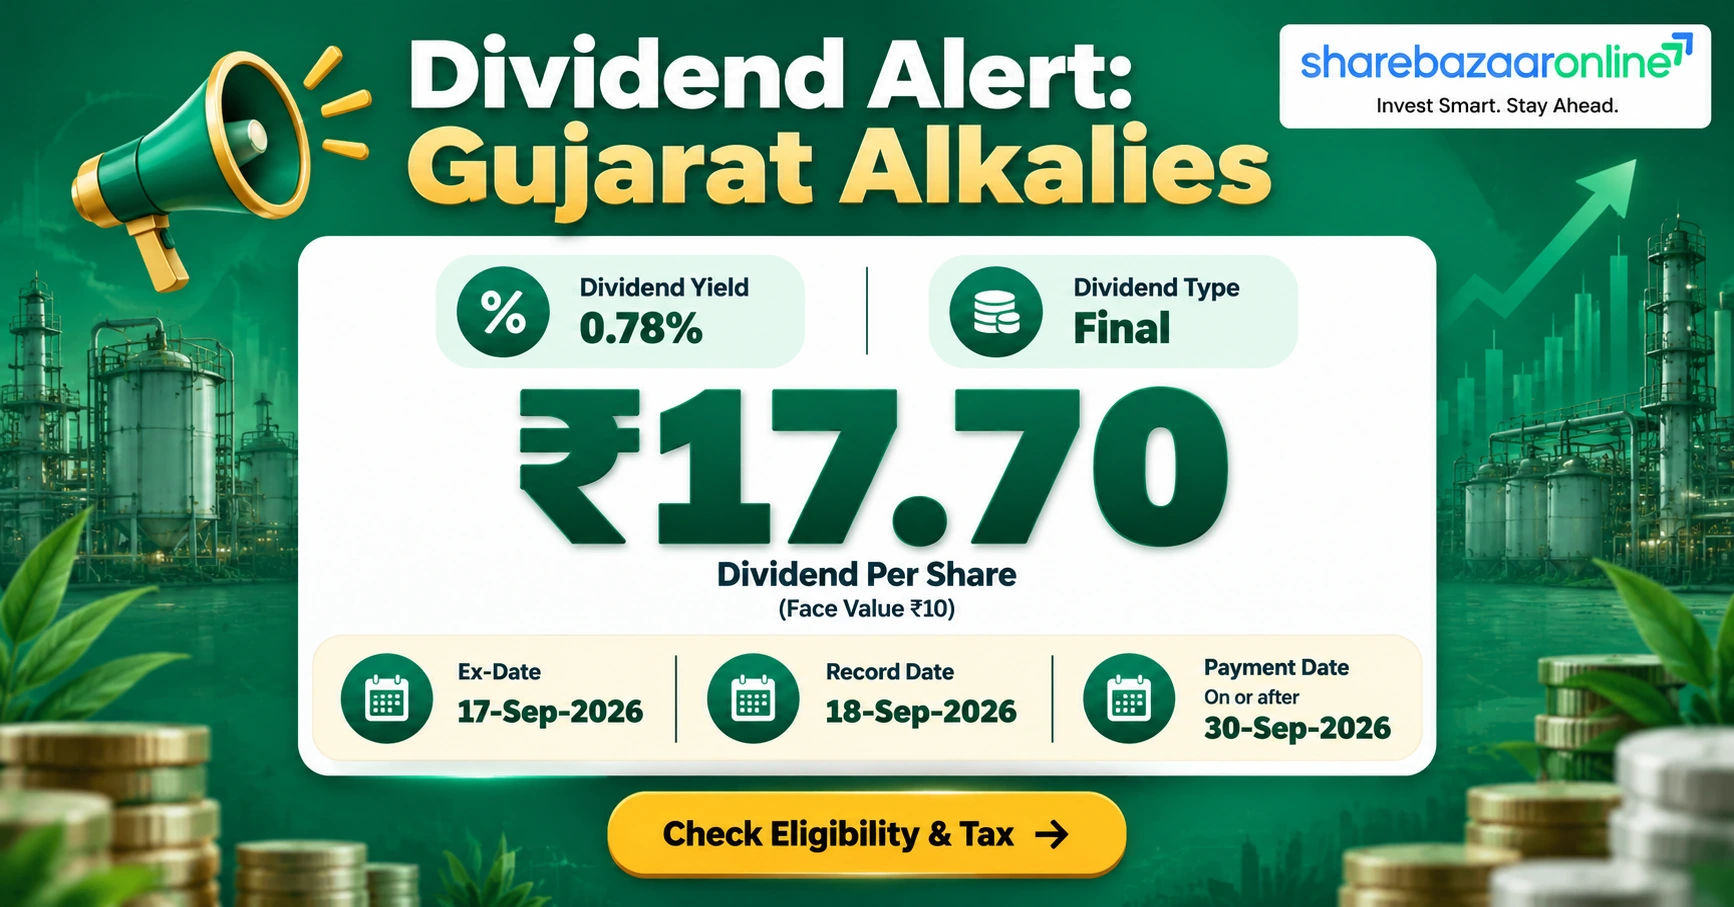
₹17.70 (177%)
Dividend Type
Final – FY 2025-26
Yield at CMP ₹631 (25 Sep 2026)
2.81%
Total Dividend Outflow
₹129.98 Cr
The face-value illusion: "177% dividend" sounds like a windfall. That percentage is measured on the ₹10 face value, a price nobody pays for the stock. At the market price of ₹631, the actual return from the Gujarat Alkalies dividend 2026 is 2.81%, about 63 times smaller than the headline figure. The payout is also 6.24x the company's standalone FY26 profit. The record date was 18 September 2026, and payment is due on or after 30 September 2026.
Gujarat Alkalies and Chemicals Limited Dividend Announcement Summary
On 29 May 2026, the board approved audited FY26 results and recommended a final dividend of ₹17.70 per share (177% of the ₹10 face value) on 7,34,36,928 equity shares. That works out to ₹12,998.34 lakh (₹129.98 Cr). The dividend needed shareholder approval, and the 53rd AGM on 25 September 2026 approved it. Under the board's announcement, it is payable within 30 days of declaration.
At the same meeting the board approved the ₹67 Cr high-purity hydrogen peroxide plant at Dahej, re-membraning of cell elements at Vadodara, and a two-year digitisation programme that includes a migration to SAP S/4HANA. The auditors issued an unmodified opinion.
Gujarat Alkalies and Chemicals Limited Dividend Record Date and Key Dates
| Event | Date |
|---|---|
| Board meeting and dividend recommendation | 29 May 2026 |
| Record date (and e-voting cut-off) | 18 September 2026 |
| Ex-dividend date | 18 September 2026* |
| Remote e-voting window | 22–24 September 2026 |
| 53rd AGM (dividend approved) | 25 September 2026 |
| Dividend payment | On or after 30 September 2026; no later than 25 October 2026 |
*Under India's T+1 settlement, ex-date and record date fall on the same day. Market data providers list 18-09-2026 as the ex-date. Confirm against the NSE/BSE corporate action circular. The payment timing comes from AGM notice coverage; the 25 October 2026 limit is the 30-day deadline from the AGM.
Gujarat Alkalies and Chemicals Limited Dividend Yield
| Reference Price | Price (₹) | Yield |
|---|---|---|
| Current market price (25 Sep 2026) | 631.00 | 2.81% |
| Announcement-day NSE close (29 May 2026) | 679.55 | 2.60% |
| 52-week high | 815.00 | 2.17% |
| 52-week low | 409.00 | 4.33% |
| Face value (headline figure) | 10.00 | 177% |
Prices: Screener.in (CMP, 52-week range), Trendlyne (29 May 2026 NSE close).
Yield reality check: The yield has not risen because the share price fell; the stock is up 12.7% over one year. It rose because the per-share dividend increased 12.0% while profits did not. GACL's 2.81% compares with an average of 0.96% for the three listed peers below.
Gujarat Alkalies and Chemicals Limited Dividend History Analysis
Classification
Consistent Payer (amount cyclical)
DPS CAGR (10-yr / 5-yr / 3-yr)
14.7% / 17.2% / -9.1%
GACL has paid a dividend every year for 11 years with no suspension. There was one cut: FY24's ₹13.85 was 41% below FY23's peak of ₹23.55. In profitable years the payout stayed modest at 8.5%–42%. The pattern changed after FY23. Over FY24–FY26 the company paid ₹347.7 Cr in dividends while posting a cumulative consolidated net loss of about ₹304 Cr. It has kept raising the payout from reserves through the down-cycle, so the dividend now depends on balance-sheet strength rather than current earnings.
Gujarat Alkalies and Chemicals Limited Dividend vs Profit Growth
| Standalone (₹ Cr) | FY26 | FY25 | Change |
|---|---|---|---|
| Revenue from operations | 4,358.08 | 4,072.91 | +7.0% |
| EBITDA excl. other income | 405.21 | 360.42 | +12.4% |
| Employee cost | 370.47 | 284.13 | +30.4% |
| Power & fuel | 1,355.32 | 1,219.08 | +11.2% |
| PBT excl. other income | -72.65 | -82.42 | Loss narrows |
| Net profit | 20.84 | 15.82 | +31.7% |
There is some operating leverage: EBITDA grew faster than revenue as raw-material costs fell 4.5%. Two costs offset it. Employee expense jumped 30.4%, which includes a gratuity and leave provision of ₹39.90 Cr versus ₹7.26 Cr, and power now takes 31.1% of revenue. The key finding is that other income of ₹116.62 Cr is 2.65x PBT. Without it, the core business made a pre-tax loss. Management's ₹522 Cr EBITDA figure also includes other income.
Gujarat Alkalies and Chemicals Limited Cash Flow Analysis
Operating Cash Flow / PAT
₹406.44 Cr / ₹20.84 Cr
Free Cash Flow (OCF – capex)
₹147.94 Cr (FY25: ₹55.74 Cr)
Here, cash tells a better story than profit. Operating cash flow was 19.5x PAT, mostly because ₹414.47 Cr of depreciation is a non-cash charge. Working capital went the other way: receivables rose 54.8% against 7.0% revenue growth, debtor days moved from 23.6 to 34.1, and ₹139.85 Cr was tied up in customer dues.
After capex of ₹258.50 Cr, free cash flow covers the dividend 1.14x. After ₹42.21 Cr of interest paid, coverage falls to 0.81x. Funding verdict: the dividend is paid from depreciation-driven operating cash plus existing cash reserves, not from current earnings. As an integrity check, dividend paid in FY26 (₹116.33 Cr) matches the computed FY25 outflow (₹116.03 Cr).
Gujarat Alkalies and Chemicals Limited Balance Sheet Strength
Borrowings / Liquid Cash
₹567.63 Cr / ₹188.92 Cr
Net Debt / Debt-to-Equity
₹378.71 Cr / 0.10x
Leverage is low, but debt edged up ₹16.06 Cr in the same year a larger dividend was declared. Net debt still fell from ₹398.69 Cr because cash rose. Interest cover (EBIT to finance cost) is thin at 1.69x.
The real cushion is ₹1,304.81 Cr of long-term equity investments, down ₹348.73 Cr during the year. That fair-value fall drove an OCI loss of ₹360.28 Cr and cut standalone net worth by ₹455.48 Cr. Book value is ₹706.9 per share on a consolidated basis, so the stock trades at 0.89x book. The GNAL joint venture (₹414 Cr invested) lost ₹38.69 Cr in FY26 and has accumulated losses of ₹633.08 Cr. No impairment was booked, based on an external valuation.
Gujarat Alkalies and Chemicals Limited Dividend Sustainability
| Test | Result | Verdict |
|---|---|---|
| Earnings coverage (EPS ÷ DPS) | 0.16x standalone; negative consolidated | Fail |
| OCF coverage | 3.13x | Pass |
| FCF coverage (after interest) | 1.14x (0.81x) | Marginal |
| Liquid cash coverage | 1.45x (11.5x incl. investments) | Pass |
Verdict: Moderately Sustainable, with conditions. Gujarat Alkalies can afford ₹129.98 Cr from cash flow and reserves for another year or two. It cannot keep paying about 6x its earnings indefinitely while also funding the FY27 capex pipeline. If Q1 FY27 profitability holds, the dividend would be covered by earnings again. If caustic soda prices weaken, the payout is exposed.
Gujarat Alkalies and Chemicals Limited vs Peers – Dividend Comparison
| Company | Yield | FY26 Payout | ROE | ROCE | Borrowings (₹ Cr) |
|---|---|---|---|---|---|
| Gujarat Alkalies | 2.81% | Loss year | -0.05% | 1.42% | 575 |
| Tata Chemicals | 1.71% | Loss year | 1.27% | 3.42% | 8,001 |
| DCM Shriram | 1.17% | 21% | 11.5% | 11.5% | 2,923 |
| Chemplast Sanmar | 0.00% | Nil | -6.80% | 0.34% | 1,952 |
Source: Screener.in consolidated data, 25–28 Sep 2026. Borrowings as of 31 Mar 2026.
GACL offers the highest yield in its chlor-alkali peer group and carries the least debt. It also ranks near the bottom on returns: ROE and ROCE are well below DCM Shriram, the only peer paying a dividend clearly covered by earnings (about 21% payout). The yield comes from dividend policy rather than profitability.
Gujarat Alkalies and Chemicals Limited Promoter Dividend Impact
Promoter Group (47.28%)
₹61.46 Cr
Minority Shareholders (52.72%)
₹68.53 Cr
The promoters are Government of Gujarat entities, so about ₹61.46 Cr of the payout goes to the state. Promoter holding rose from 46.28% to 47.28% in the March 2026 quarter. Retail and other public holders (46.44%) receive about ₹60.36 Cr, FIIs (3.26%) ₹4.24 Cr and DIIs (3.02%) ₹3.93 Cr. Distribution is strictly pro-rata with no differential benefit. Still, a loss-year payout drawn mostly from reserves moves cash from the company to the state exchequer, even as the company raises capex.
Shareholding as of June 2026 (Screener.in).
Gujarat Alkalies and Chemicals Limited Dividend Taxation
This dividend is paid in October 2026, so it falls in Tax Year 2026-27 under the Income-tax Act, 2025. It is added to your income and taxed at your slab rate. No interest deduction is allowed against dividend income from this year. The company deducts 10% TDS under Section 393(1) (formerly Section 194) if its dividends to you exceed ₹10,000 in the year, which means holding more than 565 shares at ₹17.70. Form 121 replaces Forms 15G/15H.
| Worked Example (30% slab + 4% cess) | ₹10 / share | ₹17.70 / share |
|---|---|---|
| Gross dividend (1,000 shares) | 10,000 | 17,700 |
| Tax + cess | 3,120 | 5,522.40 |
| Net dividend | 6,880 | 12,177.60 |
| TDS deducted upfront | Nil | 1,770 |
| Post-tax yield at ₹631 | 1.09% | 1.93% |
Key Risks for Gujarat Alkalies and Chemicals Limited Dividend Investors
- Reserve-funded payout: 84% of the FY26 dividend comes from reserves. Repeating that shrinks net worth.
- Commodity cycle: Caustic soda and chlorine prices drove margins down from 21% to 0.8% within a year once before.
- Power costs: Power is 31.1% of revenue, so tariff or coal shocks hit margins directly.
- JV exposure: GNAL has ₹633.08 Cr of accumulated losses against ₹414 Cr invested, and the no-impairment call rests on an external valuation.
- Investment volatility: The ₹1,304.81 Cr equity portfolio lost ₹348.73 Cr in value during FY26.
- Working capital: Receivables grew 54.8%, nearly eight times revenue growth.
- Thin interest cover: EBIT covers finance cost only 1.69x.
What to Monitor – Gujarat Alkalies and Chemicals Limited Dividend Outlook
- Q2 FY27 results: Whether the 18% OPM of Q1 FY27 holds. The trading window closes from 1 October 2026 ahead of results.
- Core profitability: PBT excluding other income needs to turn positive from -₹72.65 Cr.
- Project commissioning: HCl synthesis, chlorotoluene downstream, the flaking plant and 138.60 MW of renewables, all guided for FY27.
- Renewable share: Progress beyond 35.7%, including start of the Aditya Birla 62.7 MW supply.
- Debtor days: A move back toward the FY25 level of about 24 days from 34.1.
- GNAL: Losses at the joint venture and any change in its impairment assessment.
- FY27 dividend decision: Whether the payout returns to being covered by earnings.
Conclusion – Gujarat Alkalies and Chemicals Limited Dividend 2026
Positives
11 years of uninterrupted payments, a 2.81% yield (highest among peers), low debt at 0.10x, FCF of ₹147.94 Cr, and a clear profit recovery in Q1 FY27.
Negatives
Payout is 6.24x standalone profit, the core business made a pre-tax loss, net worth fell ₹455.48 Cr, and FCF after interest does not fully cover the dividend.
The Gujarat Alkalies and Chemicals Limited final dividend of ₹17.70 rewards shareholders for staying through a hard cycle, but it is funded by the balance sheet rather than by FY26 earnings. Whether the payout can continue depends on the recovery seen in Q1 FY27 lasting. Investors should weigh these facts against their own goals and risk tolerance.
Frequently Asked Questions About Gujarat Alkalies and Chemicals Limited Dividend
What dividend has Gujarat Alkalies and Chemicals announced for FY26?
What is the Gujarat Alkalies dividend yield?
What is the record date for the Gujarat Alkalies dividend 2026?
What was the ex-dividend date for GACL?
When will Gujarat Alkalies pay the dividend?
Who was eligible for the GACL final dividend?
How is the Gujarat Alkalies dividend taxed?
Is the Gujarat Alkalies dividend sustainable?
What is the Gujarat Alkalies dividend history?
Why is GACL paying a higher dividend despite losses?
How much dividend does the Gujarat government receive from GACL?
What should investors monitor after this dividend?
How does GACL's dividend compare with Tata Chemicals and DCM Shriram?
Disclaimer – Gujarat Alkalies and Chemicals Limited Dividend Analysis
This article is for informational and educational purposes only and is not investment, tax or legal advice. ShareBazaar Online is not a SEBI-registered investment adviser or research analyst. Nothing here is a recommendation to buy, sell or hold any security. Figures come from the company's 29 May 2026 exchange filing and cited third-party sources, and may change. Market prices and yields are as of the dates stated. Investors should verify corporate action dates on NSE/BSE and consult a qualified adviser before investing. Equity investments are subject to market risk.