
TGV SRAAC Limited Company Overview
TGV SRAAC Limited, formerly Sree Rayalaseema Alkalies and Allied Chemicals, is the flagship company of the Kurnool-based TGV Group. It makes chlor-alkali products (caustic soda, caustic potash, liquid chlorine), chloromethanes, castor oil derivatives and fatty acids, and sells mostly to industrial buyers in pharma, soaps, textiles and chemicals.
Listing Details
- NSE: TGVSL | BSE: 507753
- ISIN: INE284B01028
- Face Value: ₹10 per share
- Market Cap: about ₹1,336 Cr (25 Sep 2026)
Recent Developments
Chloromethane and caustic potash capacity additions took effect from April 2026. Solar capacity rose to 65.40 MWp in September 2026. The 26 September 2026 AGM also approved adding land development and infrastructure to the company's objects clause.
TGV SRAAC Limited Financial Analysis at a Glance
FY26 Scorecard
- Revenue from operations: ₹1,966.79 Cr (+11.5%)
- Net profit: ₹131.89 Cr (+43.2%)
- EPS: ₹12.31 (vs ₹8.60)
- Operating margin: 18% (vs 13%)
- ROE: 10.5% | ROCE: 13.0%
What the Numbers Say
FY26 was a clear recovery year, but it is still well below the FY23 peak. That year's profit of ₹362 Cr was nearly three times FY26 profit. Over three years, profit has fallen at -28.6% a year, which shows how closely TGV SRAAC's earnings follow caustic soda price cycles. Q1 FY27 profit rose 17.2% to ₹45.42 Cr.
TGV SRAAC Limited Dividend History Table
| Financial Year | Type | DPS | EPS | Payout Ratio |
|---|---|---|---|---|
| FY 2025-26 | Final | ₹1.00 | ₹12.31 | 8.1% |
| FY 2024-25 | Final | ₹1.00 | ₹8.60 | 11.6% |
| FY 2023-24 | Final | ₹1.00 | ₹5.67 | 17.6% |
| FY 2022-23 | Final | ₹1.00 | ₹33.77 | 3.0% |
| FY 2014-15 to FY 2021-22 | None | Nil | ₹1.90 to ₹12.53 | 0% |
Source: company filings; Screener.in payout data. Payout ratio = DPS ÷ EPS. The dividend has stayed at ₹1 per share for four years, even though EPS moved between ₹5.67 and ₹33.77. That gap is why the payout ratio has swung so widely from year to year.
TGV SRAAC Limited Dividend: Expert Commentary
The ShareBazaar Online research desk notes three findings that standard dividend alerts leave out.
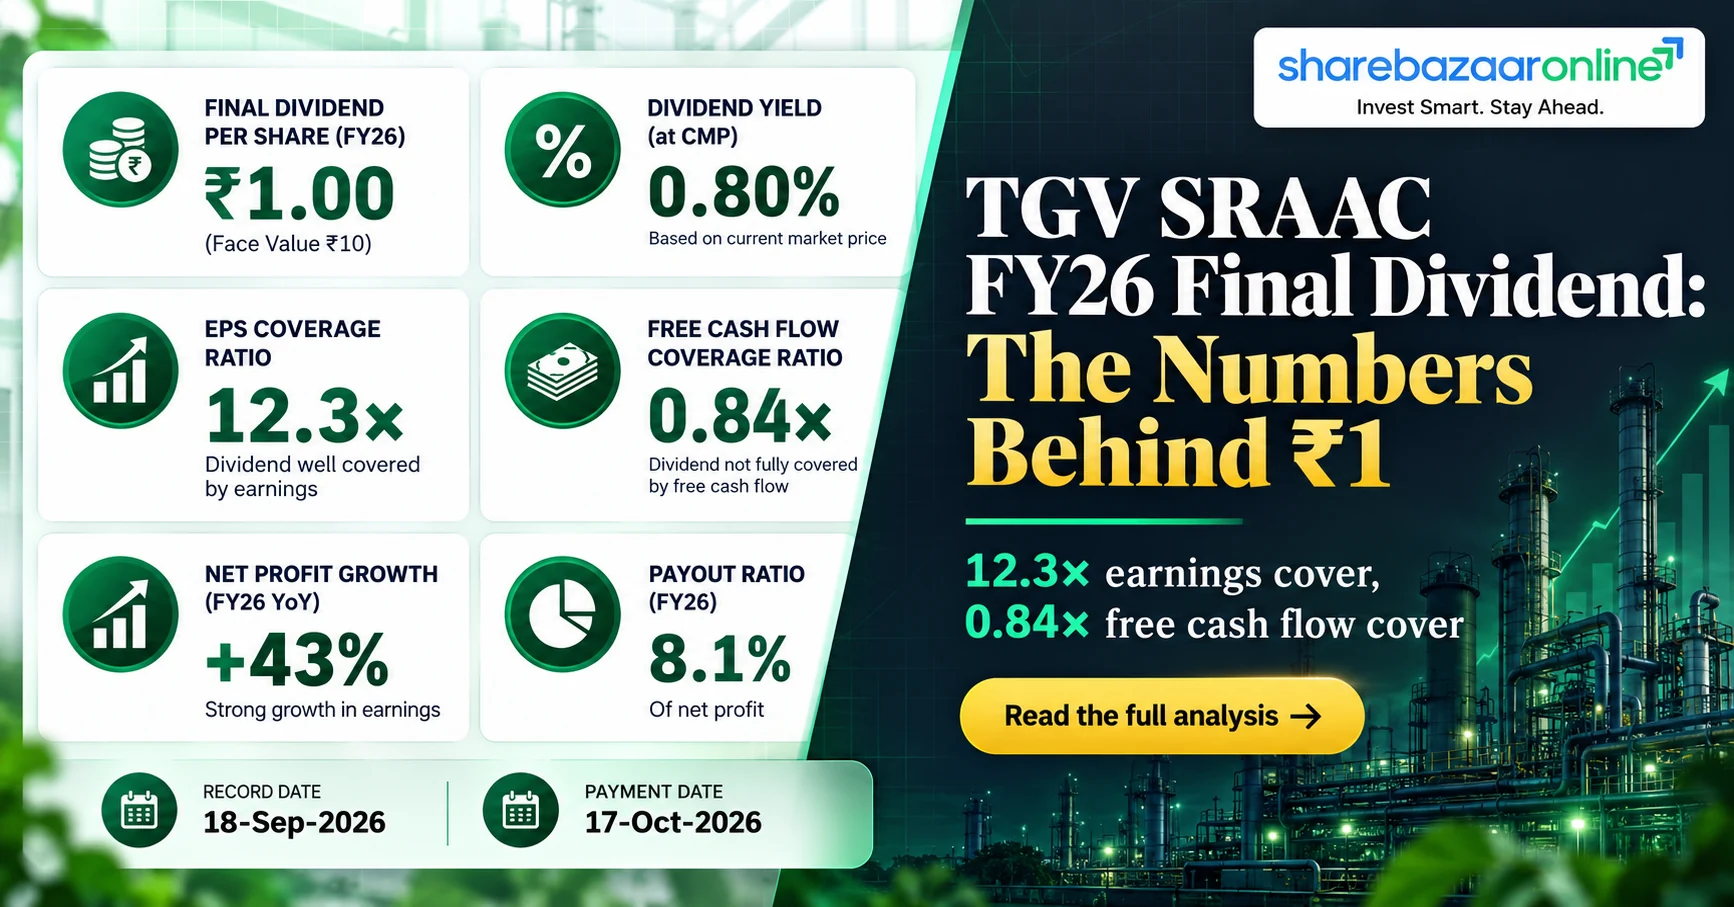
- A frozen payout. Profit rose 43%, but the dividend stayed at ₹1 for a fourth straight year, so the payout ratio fell to just 8.1%.
- Free cash flow did not cover it. FY26 free cash flow was only ₹9 Cr against a dividend bill of about ₹10.71 Cr. Capex of about ₹329 Cr absorbed almost all operating cash.
- Depreciation dampened the profit jump. Depreciation rose 86% to ₹164 Cr as new capacity was capitalised, so PAT growth (43%) trailed EBITDA growth (54%).
TGV SRAAC Limited Future Outlook
Supportive Factors
New chloromethane and potash capacity began contributing from April 2026. Q1 FY27 sales reached a record ₹543 Cr with an 18% operating margin. Captive solar power (65.40 MWp) can lower power costs, which make up a large share of chlor-alkali production costs.
Open Questions
CWIP jumped to ₹220 Cr at March 2026, which points to more capex ahead. The new land development and infrastructure objects clause could send capital outside the core chemicals business. How big any such move turns out to be will shape future dividend capacity.
Dividend Snapshot – TGV SRAAC Limited
- Dividend Type: Final Dividend, FY 2025-26
- Dividend Per Share: ₹1.00 (10% of face value)
- Record Date: 18 September 2026
- Payment Date: On or before 17 October 2026
- Dividend Yield: 0.80% at ₹125 (25 Sep 2026 close)
- Total Outflow: about ₹10.71 Cr
- Payout Ratio: 8.1% of FY26 profit
- Promoter Share: about ₹6.89 Cr
The "10% dividend" headline is calculated on the ₹10 face value. Measured against the market price, the real return is 0.80%, one-twelfth of what the headline suggests.
TGV SRAAC Limited Dividend Announcement Summary
At its meeting on 21 May 2026, the TGV SRAAC Limited board approved audited FY26 results and recommended a final dividend of ₹1 per equity share (10%), subject to shareholder approval. On 10 August 2026, the board fixed 18 September 2026 as the record date and scheduled the 44th AGM for 26 September 2026 by video conference.
The company said the dividend will be paid on or before 17 October 2026. The AGM went ahead on 26 September and its outcome was filed with BSE. The company has not published a separate dividend policy commentary for FY26. Management reasoning for keeping the payout flat is Not Disclosed by Company.
TGV SRAAC Limited Dividend Record Date and Key Dates Timeline
| Event | Date | Note |
|---|---|---|
| Board recommends dividend | 21 May 2026 | With FY26 audited results |
| Record date fixed | 10 Aug 2026 | Board meeting with Q1 FY27 results |
| Ex-dividend date | 18 Sep 2026 | Inferred under T+1 settlement |
| Record date | 18 Sep 2026 | Friday |
| 44th AGM | 26 Sep 2026 | Dividend approval by members |
| Payment | By 17 Oct 2026 | "On or before," per company |
Under India's T+1 settlement cycle, the ex-date normally falls on the record date. The exchange corporate-action listing is the final authority. The record date has passed, so shareholders who were on the register as of 18 September 2026 were eligible.
TGV SRAAC Limited Dividend Yield Analysis
Three Ways to Read the Yield
- On face value (₹10): 10.00%, the headline number
- At ₹109.80, first session after announcement (22 May 2026): 0.91%
- At ₹125, latest close (25 Sep 2026): 0.80%
Yield Reality Check
The yield has shrunk because the share price rose 13.8% after the announcement, including a 14.15% jump on 25 September. The dividend itself did not change. A 0.80% yield is low compared with bank deposit rates. For TGV SRAAC shareholders, the dividend is a small part of total return.
TGV SRAAC Limited Dividend History Analysis
TGV SRAAC Limited paid no dividends from FY15 through FY22. It began paying in FY23 and has paid exactly ₹1 per share every year since. It has made no cuts, no special dividends and no increases.
The flat amount stands out because earnings swung sharply over the same period. EPS fell from ₹33.77 in FY23 to ₹5.67 in FY24 and then recovered to ₹12.31. As a result, the payout ratio moved between 3% and 17.6%. The company seems to treat the dividend as a fixed token rather than a share of profit.
Classification: Consistent Payer (flat, token-level). The record is only four years old, so it cannot yet show how the dividend holds up through a full earnings cycle.
TGV SRAAC Limited Dividend vs Profit Growth: Financial Performance
| Metric (₹ Cr) | FY25 | FY26 | Change |
|---|---|---|---|
| Revenue | 1,763 | 1,967 | +11.5% |
| EBITDA | 230 | 355 | +54.3% |
| Depreciation | 88 | 164 | +86.4% |
| Net Profit | 92 | 132 | +43.2% |
Operating leverage helped: an 11.5% rise in revenue produced 54.3% EBITDA growth as margins widened from 13% to 18%. Depreciation then took a large share of that gain. The 5-year revenue CAGR is 14.1%, but the 3-year figure is -5.7% because FY23 was a peak year. Q4 FY26 profit rose 29% year on year to ₹27.99 Cr, so the momentum continued into the new financial year.
TGV SRAAC Limited Cash Flow Analysis
Cash vs Profit
FY26 operating cash flow was ₹338 Cr, or 2.56 times net profit, and 108% of operating profit. That is strong cash conversion: reported profit is backed by cash, helped by large non-cash depreciation.
Where the Cash Went
About ₹329 Cr went into capex, leaving free cash flow of only ₹9 Cr. That covers the dividend just 0.84 times. The dividend was effectively paid out of operating cash before growth spending, not out of surplus.
Receivables warning: estimated receivables rose about 17.9% while sales grew 11.5%, and debtor days went from 52 to 55. The gap is small but worth watching.
TGV SRAAC Limited Balance Sheet Strength
- Net worth: ₹1,297 Cr (March 2026)
- Borrowings: ₹357 Cr, flat year on year
- Debt to equity: 0.28 times
- Investments: ₹35 Cr
- Book value per share: about ₹121
Leverage is moderate, and debt did not rise in the year the dividend was paid. Borrowings are about 10 times investments, so the company is a net borrower. The standalone cash balance is Not Disclosed by Company in the summary data we reviewed. Investments alone cover the dividend 3.3 times. Interest cost fell 3.3% to ₹29 Cr.
TGV SRAAC Limited Dividend Sustainability
| Test | Result | Verdict |
|---|---|---|
| Earnings coverage (EPS ÷ DPS) | 12.3 times | Strong |
| Operating cash flow coverage | 31.5 times | Strong |
| Free cash flow coverage | 0.84 times | Weak |
| Liquidity (investments ÷ outflow) | 3.3 times | Adequate |
Verdict: Sustainable. At about ₹10.71 Cr, the dividend is less than 1% of the company's net worth. Even in FY24's trough year, EPS covered it 5.7 times. The weak free cash flow test reflects heavy capex rather than stress. The more realistic risk is that the dividend stays flat, not that it gets cut.
TGV SRAAC Limited Peer Comparison
| Company | Yield | FY26 Payout | ROE | ROCE | P/E |
|---|---|---|---|---|---|
| TGV SRAAC | 0.80% | 8% | 10.5% | 13.0% | 9.6 |
| Gujarat Alkalies | 2.81% | Loss year | -0.05% | 1.4% | 69.8 |
| Andhra Sugars | 1.06% | 19% | 6.9% | 9.3% | 10.7 |
| DCW | 0.63% | Low | 4.7% | 9.9% | 20.0 |
Source: Screener.in, prices as of 21 to 28 Sep 2026. Andhra Sugars and DCW are standalone figures.
TGV SRAAC has the best ROE and ROCE in this group but the lowest payout ratio. Gujarat Alkalies has the highest yield even though it made a loss in FY26, which is a clear example of yield that is not backed by earnings.
TGV SRAAC Limited Promoter Impact Analysis
Who Gets the ₹10.71 Cr
- Promoters (64.27%): ₹6.89 Cr
- Public (35.54%): ₹3.81 Cr
- FIIs (0.12%): about ₹0.01 Cr
- DIIs (0.07%): about ₹0.01 Cr
Reading the Pattern
Promoter holding has risen steadily from 54.79% (FY17) to 64.27%. Over FY15 to FY21, equity capital also grew 35%, from ₹79 Cr to ₹107 Cr, which is consistent with allotments to the promoter group. A low payout means more of the profit stays inside a promoter-controlled company. Public holders number about 50,267, down from 63,333 in September 2024.
TGV SRAAC Limited Dividend Taxation Analysis
Dividends are taxed at the shareholder's income-tax slab rate. This dividend is paid in FY 2026-27, so TDS falls under Section 393(1) of the Income-tax Act, 2025 (formerly Section 194). The rate is 10% if dividends from one company exceed ₹10,000 in a year, or 20% without a valid PAN. Form 121 replaces Forms 15G and 15H. Non-residents face 20% TDS plus surcharge and cess, or a lower treaty rate.
Worked Example (30% slab)
- 1,000 shares at ₹10 per share: gross ₹10,000
- Tax at 31.2% including cess: ₹3,120
- Net dividend: ₹6,880
- Effective yield at ₹125: 8.00% gross, 5.50% net
Actual TGV SRAAC Payout
At the real ₹1 per share, 1,000 shares receive ₹1,000. After tax that is ₹688, a net yield of just 0.55%. No TDS applies unless a holder owns more than 10,000 shares.
Key Risks for TGV SRAAC Limited Shareholders
- Commodity cycle: caustic soda prices drive earnings. Profit fell 83% from FY23 to FY24.
- Diversification risk: the new land development and infrastructure objects could draw capital into unrelated activities.
- Capex intensity: ₹220 Cr of CWIP and thin free cash flow limit room for a higher payout.
- Power cost: electrolysis uses a lot of electricity, so tariff changes directly affect margins.
- Thin institutional ownership: combined FII and DII holding is under 0.2%, which limits liquidity and outside scrutiny.
- Working capital: receivables are growing faster than sales.
What To Monitor at TGV SRAAC Limited
- Q2 FY27 margins: whether operating margin holds near 18%.
- Utilisation of new capacity: contribution from the April 2026 chloromethane and potash additions.
- CWIP capitalisation: how fast the ₹220 Cr flows into assets and depreciation.
- Land and infrastructure plans: any disclosed spending under the new objects clause.
- Free cash flow recovery: whether free cash flow once again covers the dividend as capex eases.
- Dividend policy: whether the payout finally grows beyond the flat ₹1.
- Payment credit: confirmation that the dividend is credited by 17 October 2026.
TGV SRAAC Limited Dividend Outlook: Conclusion
Positives
- Profit up 43%, and OCF 2.56 times PAT
- Earnings cover the dividend 12.3 times
- Highest ROE and ROCE in the peer group
- Four straight years of dividends
Negatives
- Real yield of only 0.80%
- Payout ratio down to 8.1%
- Free cash flow of ₹9 Cr is below the dividend
- New non-core objects clause
The TGV SRAAC Limited dividend for FY26 is safe but small. The company is keeping about 92% of its profit for capex. Whether that retained cash produces higher returns is the question for shareholders to weigh against the 0.80% yield.
Frequently Asked Questions About TGV SRAAC Limited Dividend
What dividend has TGV SRAAC Limited announced for FY 2025-26?
What is the TGV SRAAC dividend yield?
What was the TGV SRAAC dividend record date?
What was the ex-dividend date for TGV SRAAC?
When will the TGV SRAAC dividend be paid?
Who was eligible for the TGV SRAAC dividend?
How is the TGV SRAAC dividend taxed?
Is the TGV SRAAC dividend sustainable?
What is the TGV SRAAC dividend history?
Why didn't TGV SRAAC raise its dividend when profit rose 43%?
How much do TGV SRAAC promoters receive from this dividend?
How does the TGV SRAAC dividend compare with peers?
What should TGV SRAAC investors monitor next?
Disclaimer – TGV SRAAC Limited Dividend Analysis
This article is for educational and informational purposes only and is not investment advice or a recommendation to buy, sell or hold any security. ShareBazaar Online is not a SEBI-registered investment adviser or research analyst. Figures come from company filings, BSE disclosures and Screener.in as of 28 September 2026, and computed ratios are the desk's own calculations. Share prices, dates and tax rules may change. Readers should check details against official exchange filings and consult a qualified financial or tax adviser before making decisions.