
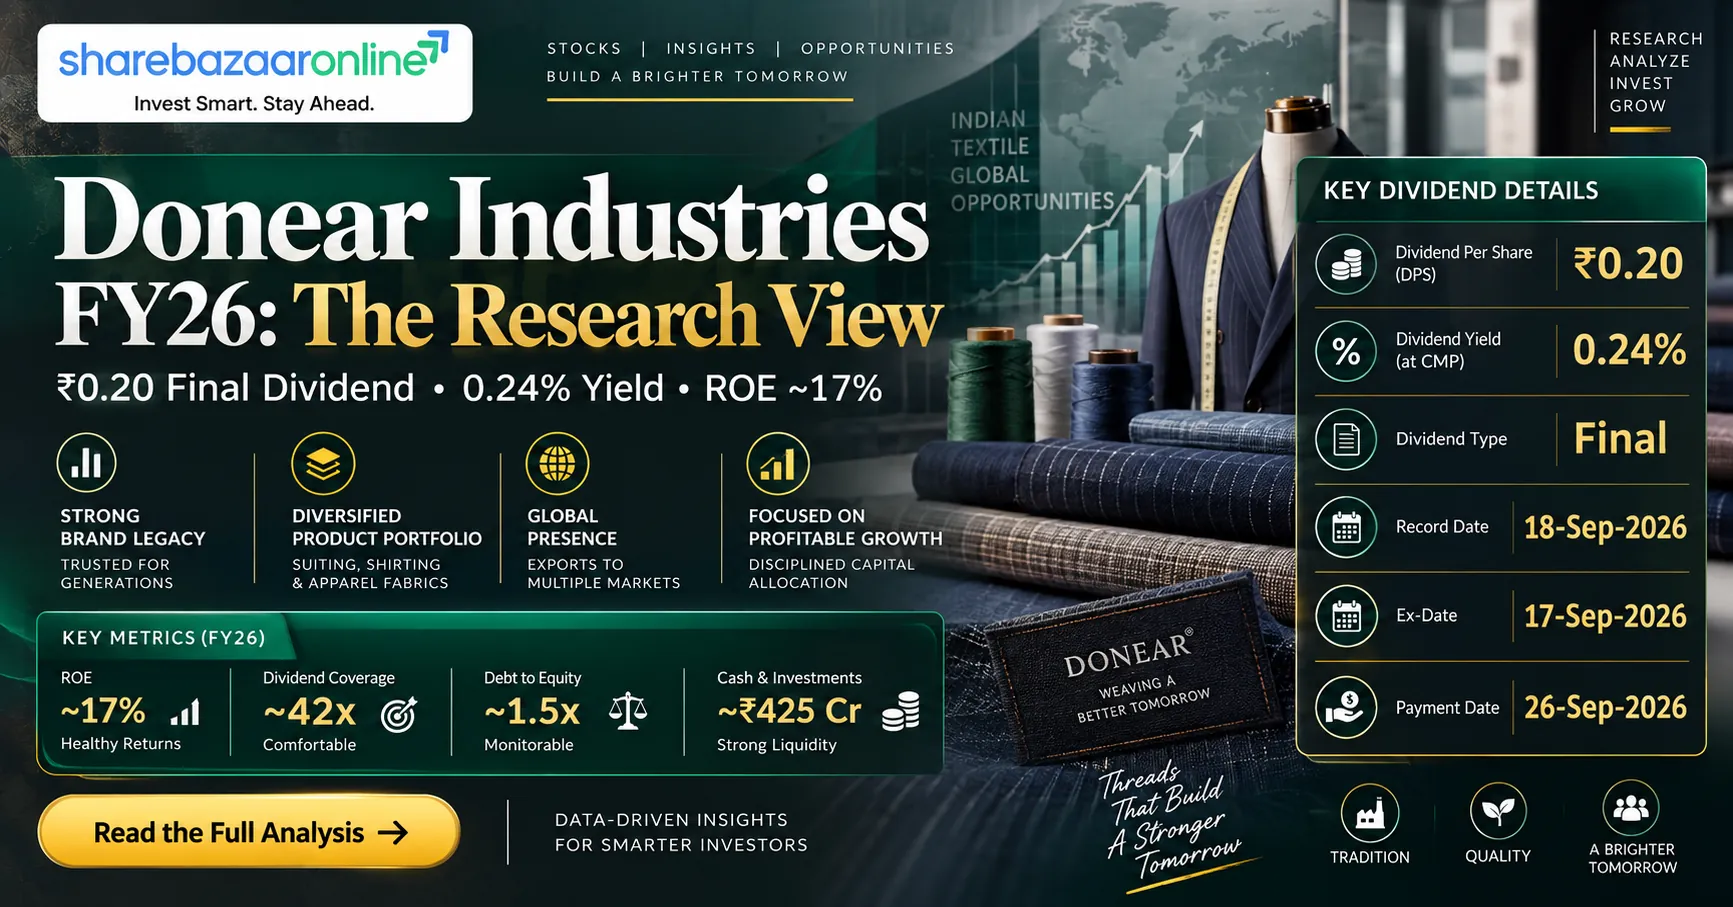
Donear Industries Limited Company Overview
Donear Industries Limited (NSE: DONEAR, BSE: 512519) is a Mumbai-based textile manufacturer incorporated in 1987, known for suiting, shirting and trouser fabrics under the Donear, Mayur and Donear NXG brands, plus garments under the D'cot label. On 30 May 2026, the Board recommended a Final Dividend of ₹0.20 per equity share (face value ₹2) for FY2025-26. This Donear Industries dividend analysis examines whether that payout is affordable, sustainable and meaningful for shareholders. The company operates two segments — Textiles and Rentals — and runs manufacturing units in Surat and Silvassa. For FY26, standalone revenue was nearly flat at ₹912.47 crore, while net profit rose sharply to ₹43.43 crore, aided by cost control rather than sales growth.
Donear Industries Limited Financial Analysis
Profit Up, Revenue Flat
FY26 was a profit-led year for Donear Industries. Consolidated revenue slipped 0.13% to ₹912.47 crore, yet consolidated PAT jumped roughly 36% to ₹43.46 crore from ₹31.87 crore. Growth came from lower total expenses (₹862.20 crore vs ₹876.35 crore), not from selling more fabric.
Returns vs Leverage
The business earns strong returns — ROE ~17% and ROCE ~13.7%, above the textile peer average of about 9%. The catch is a high debt-to-equity of ~1.5-1.66x, the steepest among listed peers, which shapes the entire dividend story below.
Donear Industries Limited Dividend History Table
| Financial Year | Dividend/Share | Dividend % | Type | Ex-Date (approx) |
|---|---|---|---|---|
| FY2025-26 | ₹0.20 | 10% | Final | ~17 Sep 2026 |
| FY2024-25 | ₹0.20 | 10% | Final | 19 Sep 2025 |
| FY2023-24 | ₹0.20 | 10% | Final | 20 Sep 2024 |
| FY2022-23 | ₹0.20 | 10% | Final | 18 Sep 2023 |
| FY2021-22 | ₹0.20 | 10% | Final | 13 Sep 2022 |
| FY2020-21 | ₹0.20 | 10% | Final | 13 Sep 2021 |
Source: NSE/BSE corporate actions, Tickertape, TipRanks. Per-share amounts on current ₹2 face value. Figures cited from external sources.
Expert Commentary on Donear Industries Limited Dividend
The Donear Industries dividend of ₹0.20 is best read as a token, habit-driven payout rather than a wealth-transfer event. At a payout ratio near 2.4% of profit, the company keeps roughly 97-98 paise of every rupee earned inside the business. That is defensible for a firm carrying over ₹400 crore of gross debt — retained earnings and cash are arguably better spent trimming interest costs (FY26 finance costs were ₹28.55 crore) than paid out. The dividend is comfortably covered (EPS ₹8.35 vs DPS ₹0.20), so there is no sustainability concern. But income-focused investors should be clear-eyed: the ~0.24% yield is immaterial. The real question is capital allocation, not the coupon.
Donear Industries Limited Dividend Outlook
The forward picture for the Donear Industries dividend points to continuity, not growth. The company has paid a flat ₹0.20 per share for six consecutive years, through both strong and weak profit years, signalling a fixed-policy approach rather than a progressive one. With debt reduction and working-capital needs (inventory of ₹415 crore) competing for cash, a step-up in payout looks unlikely near-term. A meaningfully higher dividend would probably require either sustained margin expansion or a lighter balance sheet. For now, expect the same modest cheque, with the investment case resting on earnings and re-rating rather than dividend income.
Dividend Snapshot – Donear Industries Limited
- Dividend Per Share₹0.20
- Dividend %10%
- Face Value₹2
- Dividend TypeFinal
- Dividend Yield (CMP)~0.24%
- Announcement Date30-05-2026
- Record Date18-09-2026
- AGM Date26-09-2026
- Payout Ratio~2.4%
- Dividend Outflow~₹1.04 Cr
Donear Industries Limited Dividend Announcement Summary
At its board meeting on 30 May 2026, Donear Industries recommended a Final Dividend of ₹0.20 per equity share of face value ₹2 (a 10% dividend) for the year ended 31 March 2026, subject to shareholder approval at the ensuing AGM. The board simultaneously approved audited standalone and consolidated results carrying an unmodified audit opinion, and re-appointed cost auditors M/s Y. R. Doshi & Co. for FY2026-27. The company later fixed the record date as 18 September 2026 and called its 40th AGM for 26 September 2026, with payment to follow AGM approval. This is a standalone final dividend — no interim or special component was declared.
Donear Industries Limited Key Dates Timeline
- 30 May 2026 — Board recommends ₹0.20 final dividend
- ~17 Sep 2026 — Ex-dividend date (one business day before record date)
- 18 Sep 2026 — Record date (eligibility cut-off)
- 26 Sep 2026 — 40th AGM (shareholder approval)
- On/after 26 Sep 2026 — Dividend payment / dispatch
Ex-date is derived from the record date; exact payment date to be confirmed post-AGM. Record/AGM dates cited from external corporate filings.
Donear Industries Limited Dividend Yield Analysis
On a recent market price of about ₹83, the ₹0.20 dividend gives a yield of roughly 0.24%. On the announcement-date price (~₹84 in late May 2026), the yield was almost identical at ~0.24%. To put that in context: ₹1 lakh invested in Donear earns about ₹240 a year in dividends — far below a savings account. Importantly, the yield has not risen because of a bigger dividend; the payout has been fixed at ₹0.20 for years. Any small uptick in yield simply reflects a lower share price (the stock is down ~13-16% over one year), not improved shareholder generosity. This is a growth/value stock, not an income stock.
Donear Industries Limited Dividend History Analysis
Donear Industries qualifies as a consistent but flat payer. It has distributed ₹0.20 per share every year for at least six years (FY21 through FY26), with no cuts and no suspensions — a positive signal of financial stability and management discipline. However, there has been zero dividend growth over this period, and no special dividends despite the strong FY26 profit jump. The consistency is reassuring; the stagnation is telling. It confirms a deliberate policy of prioritising retention and debt servicing over rising cash returns. Investors should treat the ₹0.20 as a stable floor, not a growing income stream.
Donear Industries Limited Financial Performance Analysis
The headline for FY26 is margin-driven profit growth on flat sales. Consolidated revenue was ₹912.47 crore (down 0.13%), but PAT rose ~36% to ₹43.46 crore, lifting consolidated EPS to ₹8.35 from ₹6.13. Profit before tax climbed to ₹59.26 crore from ₹44.61 crore. The negative read: the profit gain is not volume-led — it came from a ₹14 crore cut in total expenses, so it depends on cost discipline holding. With revenue stuck near ₹912 crore for two straight years, top-line growth remains the key missing ingredient. Strong ROE (~17%) shows the capital base is productive, but a flat topline caps how durable the earnings surge can be.
Donear Industries Limited Cash Flow Analysis
Cash is where the caution lies. FY26 operating cash flow was just ₹15.60 crore against reported PAT of ₹43.46 crore — a wide gap that signals profits are not fully converting to cash, largely due to working-capital drag (trade & other receivables rose ₹4.61 crore and inventory absorbed cash). After capex of ₹13.22 crore, free cash flow was a thin ~₹2.38 crore. The good news: the ₹0.20 dividend costs only ₹1.04 crore, so it is still covered ~2.3x by FCF and ~11x by liquid balances. The dividend is funded from current earnings, not borrowings — but the weak OCF-to-PAT conversion is the single most important number income investors should watch.
Donear Industries Limited Balance Sheet Strength
The balance sheet is the weakest link. Total borrowings stand at roughly ₹425 crore (mostly ₹424.9 crore current borrowings), against total equity of about ₹276.9 crore — a debt-to-equity near 1.5x, the highest among listed textile peers. Liquid balances (cash plus other bank balances) are modest at around ₹11.7 crore. This heavy, short-term-skewed debt load is exactly why the tiny dividend makes strategic sense: cash retained services interest (₹28.55 crore in FY26) and funds a large inventory book (~₹415 crore). Book value per share is around ₹53. A stronger balance sheet — via debt reduction — would do more for shareholders than a bigger dividend.
Donear Industries Limited Dividend Sustainability
Verdict: Highly Sustainable
At just ~2.4% of profit and ~₹1.04 crore in cash, the Donear Industries dividend is trivially easy to maintain. Dividend coverage is ~42x (EPS ₹8.35 / DPS ₹0.20), cash coverage ~11x and FCF coverage ~2.3x.
The Trade-off
Sustainability is not the issue — size is. The payout is so small that even a bad year would not threaten it. The flip side is there is little scope for the dividend to matter to returns while debt stays elevated.
Donear Industries Limited Peer Comparison
| Company | Dividend Yield | ROE | Debt/Equity |
|---|---|---|---|
| Donear Industries | ~0.24% | ~17% | ~1.5x |
| Sutlej Textiles | ~2.5% | Negative (loss) | ~0.96x |
| Dollar Industries | ~0.84% | Positive | Lower |
Donear stands out for the best profitability (ROE ~17%) but the lowest dividend yield and highest leverage in the group. Peers like Sutlej yield far more (~2.5%) but are currently loss-making. Donear's profile is "earn well, retain heavily, pay little."
Donear Industries Limited Promoter Impact Analysis
Promoters (the Agarwal family) hold 74.56% of Donear Industries, with no FII or DII holding and ~25% public float. Of the ~₹1.04 crore total dividend outflow, promoters receive about ₹0.78 crore and public shareholders roughly ₹0.26 crore. Because the payout is so small, the dividend is not a meaningful promoter cash-extraction route — unlike high-payout firms, promoters here are clearly favouring reinvestment and debt reduction over dividends, which aligns their interests with minority holders on balance-sheet repair. One governance item to note: the AGM also proposes a ₹250 crore related-party transaction with GBTL, which minority investors should review.
Donear Industries Limited Taxation Analysis
Since April 2020, dividends in India are taxable in the hands of the investor at their income-tax slab rate. Companies deduct TDS at 10% if a resident's total dividend exceeds ₹5,000 in a financial year (₹10,000 threshold applies from FY25-26 onwards per Budget changes). Given Donear's tiny ₹0.20 payout, most retail holders will fall below the TDS threshold.
Worked Example (1,000 shares, ₹0.20/share, 30% slab)
- Gross Dividend (1,000 × ₹0.20)₹200
- Tax @ 30% slab₹60
- Net Dividend in hand₹140
- Effective post-tax yield (on ~₹83)~0.17%
No TDS here as ₹200 is below the threshold. Illustrative; consult a tax advisor. This is not tax advice.
Donear Industries Limited Key Risks
- High leverage: Debt-to-equity ~1.5x (~₹425 crore borrowings) is the highest among peers; rising rates directly pressure profit.
- Weak cash conversion: FY26 OCF of ₹15.60 crore is far below PAT of ₹43.46 crore, driven by heavy receivables and ~₹415 crore inventory.
- Flat revenue: Sales stuck near ₹912 crore for two years; profit growth is cost-led and may not repeat.
- Raw material & input volatility: Fabric margins are exposed to polyester, viscose and cotton price swings.
- Related-party exposure: Proposed ₹250 crore GBTL related-party transaction warrants governance scrutiny.
- Negligible dividend: ~0.24% yield offers no income cushion during price drawdowns.
Donear Industries Limited — What To Monitor
- Debt reduction: Track quarterly borrowings and finance cost — falling debt is the real shareholder catalyst here.
- Operating cash flow vs PAT: Watch whether OCF converges toward reported profit in future years.
- Working capital: Inventory and receivable days — the main drain on cash generation.
- Revenue growth: Any return to top-line growth would validate the earnings surge.
- Margin durability: Whether FY26's cost savings and ~17% ROE hold up.
- Dividend policy shift: Any move above the fixed ₹0.20 would signal changed capital-allocation priorities.
Should You Consider Donear Industries Limited for Dividend Income?
The Donear Industries FY26 dividend of ₹0.20 per share tells a coherent story: a profitable, well-run fabric maker (ROE ~17%, FY26 PAT up ~36% to ₹43.46 crore) that deliberately keeps its cash to service a heavy ~₹425 crore debt load rather than reward shareholders with income. The payout is rock-solid but immaterial — a ~0.24% yield, covered ~42x by earnings. For pure dividend-income seekers, that yield is negligible. The genuine watch-items are debt reduction, cash conversion and revenue growth, not the dividend cheque. On the plus side, consistent six-year payment and strong profitability signal stability; the concerns are leverage, weak OCF and a flat topline. Positives, negatives, risks and monitoring points are laid out above — the decision is yours.
Frequently Asked Questions About Donear Industries Limited Dividend
What dividend has Donear Industries announced for FY26?
What is the Donear Industries dividend yield?
What is the record date for the Donear Industries dividend?
What is the ex-dividend date for Donear Industries?
When will the Donear Industries dividend be paid?
Who is eligible for the Donear Industries dividend?
How is the Donear Industries dividend taxed?
Is the Donear Industries dividend sustainable?
What is the Donear Industries dividend history?
What should Donear Industries investors monitor?
What is Donear Industries' FY26 profit?
Does Donear Industries have high debt?
Disclaimer
This article is for informational and educational purposes only and does not constitute investment, financial or tax advice, nor a Buy, Sell or Hold recommendation. Figures for the FY26 dividend, financial results and record/AGM dates are drawn from Donear Industries' official filing dated 30 May 2026 and its subsequent corporate disclosures; market prices, ratios, shareholding and peer data are sourced from public financial portals and may change. Some values are approximate or "Not Disclosed by Company" where filings are silent. Securities markets carry risk. Please verify all figures independently and consult a SEBI-registered financial advisor before making any investment decision. ShareBazaar Online is not liable for any loss arising from the use of this content.