
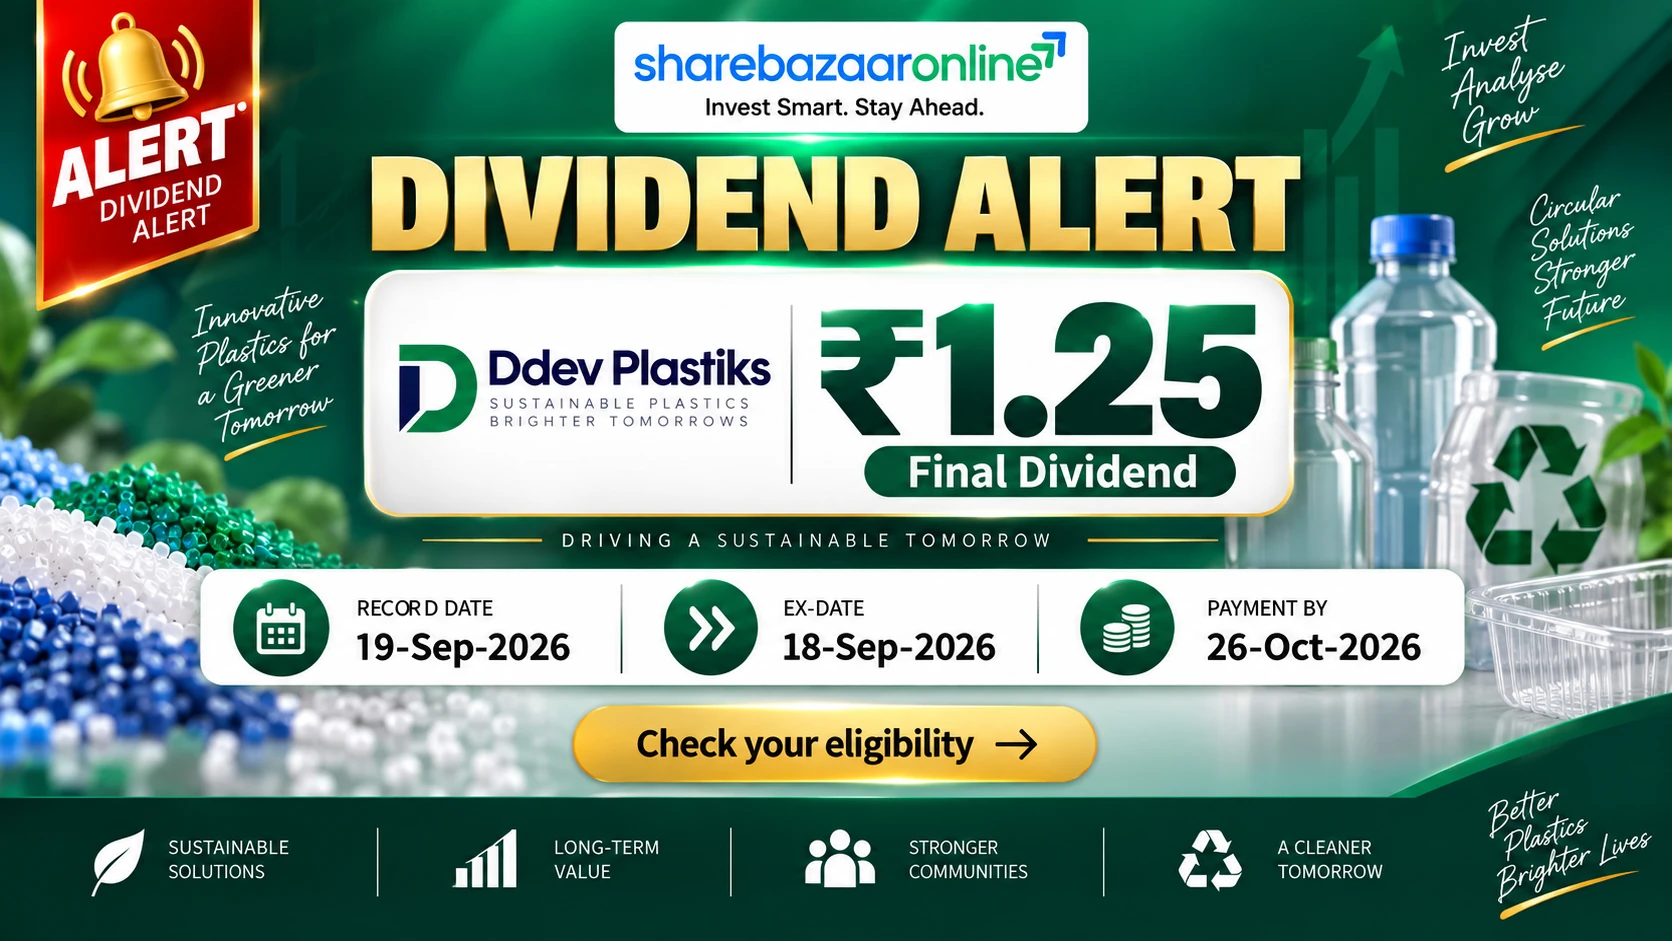
Ddev Plastiks Industries Dividend 2026 – At a Glance
Ddev Plastiks Industries Limited (NSE: DDEVPLSTIK, BSE: 543547) announced a final dividend of ₹1.25 per equity share for FY2025-26, styled as a headline 125% dividend. That percentage is calculated on a face value of just Re 1, so the real cash payout is only ₹1.25 a share — a dividend yield of about 0.49% at the current market price of ₹255.15 (NSE, 17-Sep-2026). The record date of 19-Sep-2026 has already passed. This Ddev Plastiks dividend 2026 analysis goes beyond the headline number to test coverage, cash flow, sustainability and promoter impact.
Company Overview – Ddev Plastiks Industries Limited
Ddev Plastiks Industries Limited is India’s largest listed manufacturer of polymer compounds, with over four decades of operating history and an installed capacity of roughly 2,68,400 MTPA across seven plants. It supplies customised compounds — PVC, PE, filler, masterbatch, HFFR, footwear, pipe and peroxide grades — mainly to the wires & cables industry, plus packaging, white goods and engineering plastics. The company (CIN: L24290WB2020PLC241791) is Kolkata-headquartered and listed on the NSE and BSE since July 2022. It classifies under the Specialty Chemicals space. Ddev Plastiks is almost debt-free and posted a return on equity of about 21.8% and ROCE near 31%, making it a financially conservative dividend payer worth examining closely.
Ddev Plastiks Industries Financial Analysis (FY26)
For the year ended March 2026, Ddev Plastiks reported consolidated revenue from operations of ₹2,948 crore, up 12.2% from ₹2,627 crore in FY25 (source: ICICIdirect/company filing). Net profit rose 9.2% to ₹202 crore (₹20,181.63 lakh) from ₹185 crore, and EPS improved to ₹19.50 from ₹17.93. Profitability, however, lagged revenue: Q4FY26 operating margin was about 9.7%, reflecting raw-material and geopolitical cost pressure. The stock traded at a P/E near 13x with a book value of about ₹97.9. The dividend must be read against this backdrop of steady top-line growth but modest margin compression at the Ddev Plastiks operating level.
Ddev Plastiks Industries Dividend History
The table below sets out the Ddev Plastiks dividend payment history since listing (all on face value Re 1). External dates are sourced from exchange/registrar disclosures and public dividend records.
| Financial Year | Type | Dividend (₹/share) | Dividend % | Record/Ex Period |
|---|---|---|---|---|
| FY2021-22 | Final | 0.24 | 24% | Sep 2022 |
| FY2022-23 | Final | 1.00 | 100% | Sep 2023 |
| FY2023-24 | Interim | 0.50 | 50% | Nov 2023 |
| FY2023-24 | Final | 1.00 | 100% | Sep 2024 |
| FY2024-25 | Final | 1.00 | 100% | Sep 2025 |
| FY2025-26 | Interim | 0.50 | 50% | Feb 2026 |
| FY2025-26 | Final | 1.25 | 125% | 19-Sep-2026 |
Annual totals: FY24 ₹1.50, FY25 ₹1.00, FY26 ₹1.75 (interim + final). Ddev Plastiks has paid a dividend every year since listing.
Expert Commentary on the Ddev Plastiks Dividend
The most important thing to understand about the Ddev Plastiks final dividend is the face-value illusion. A “125% dividend” sounds generous, but the percentage is on a Re 1 face value — so the actual cash is only ₹1.25 per share. On a market price above ₹255, that translates to a real yield of roughly 0.49%, far below a bank savings account. This is a token, growth-stage payout, not an income play. The company is retaining almost all of its earnings — the FY26 final payout ratio is only about 6.4% of profit — to fund capacity expansion. Investors chasing yield will be disappointed; the real signal here is management’s confidence and balance-sheet strength, not distribution.
Ddev Plastiks Industries Future Outlook
Ddev Plastiks has set an ambitious compounding-business revenue target of ₹5,000 crore by FY30, against ₹2,948 crore in FY26. Near-term, management guides to about 13% revenue growth in FY27. A dedicated 48,000 MTPA XLPE unit (₹80 crore investment) became operational from April 2026, targeting the wires & cables demand wave from new entrants like Adani and UltraTech. The board also approved a foray into Battery Energy Storage System (BESS) projects, targeting ₹200–250 crore of revenue in FY27. Exports grew 30% in FY26 despite geopolitical disruption. This heavy reinvestment phase explains why Ddev Plastiks keeps its dividend deliberately small.
Dividend Snapshot – Ddev Plastiks Industries Limited
Dividend Per Share
₹1.25
Dividend Percentage
125% (on Re 1 FV)
Dividend Type
Final Dividend
Dividend Yield (at CMP ₹255.15)
~0.49%
Record Date
19-Sep-2026
Total Dividend Outflow (Final)
₹12.93 crore
Ddev Plastiks Dividend Announcement Summary
The board of Ddev Plastiks Industries, at its meeting on 25-May-2026, recommended a final dividend of ₹1.25 per equity share (125% on face value Re 1) for the financial year 2025-26, subject to shareholder approval at the Annual General Meeting. Per the company’s exchange filing dated 31-Aug-2026, the record/cut-off date was fixed at 19-Sep-2026, with the register of members closed from 20-Sep-2026 to 26-Sep-2026. The total final-dividend outflow is disclosed at ₹1,293.46 lakh (₹12.93 crore). The dividend was placed for approval at the 6th AGM on 26-Sep-2026, and once declared, is payable within 30 days of that declaration.
Ddev Plastiks Dividend – Key Dates Timeline
| Event | Date |
|---|---|
| Board Recommendation (Announcement) | 25-May-2026 |
| Ex-Dividend Date (inferred, pending exchange circular) | 18-Sep-2026 |
| Record / Cut-off Date | 19-Sep-2026 |
| Book Closure | 20-Sep-2026 to 26-Sep-2026 |
| Remote E-Voting Window | 23-Sep-2026 to 25-Sep-2026 |
| 6th Annual General Meeting | 26-Sep-2026, 11:30 AM (VC/OAVM) |
| Expected Payment (within 30 days of declaration) | By ~26-Oct-2026 |
Note: The ex-date is inferred under India’s T+1 framework because the record date (19-Sep-2026) falls on a Saturday; the last cum-dividend trading day was the prior working day. Confirm against the official NSE/BSE corporate-action circular.
Ddev Plastiks Industries Dividend Yield Analysis
Yield is where the Ddev Plastiks dividend reality check bites. Against the current market price of ₹255.15, the final ₹1.25 gives a yield of just 0.49%; measured against the price around the 25-May-2026 announcement (~₹245), it was about 0.51%. Even combining the FY26 interim (₹0.50) and final (₹1.25) for a full-year ₹1.75, the trailing yield is only ~0.69%. This low yield is not the result of a falling share price masking a large payout — it is simply a small absolute dividend on a Re 1 face value. For income-focused investors, Ddev Plastiks offers negligible cash return; the stock is a capital-appreciation candidate, not a yield instrument.
Ddev Plastiks Dividend History Analysis
Across its short listed life, Ddev Plastiks qualifies as a consistent dividend payer with a gently rising trend. Annual dividends moved from ₹0.24 (FY22) to ₹1.00 (FY23), ₹1.50 (FY24), ₹1.00 (FY25) and ₹1.75 (FY26). There have been no dividend suspensions or cuts of note, and no special dividends. The FY26 final of ₹1.25 is the single largest final payout so far. The pattern is best described as a steadily growing token distribution that tracks earnings while leaving the bulk of profit for reinvestment. This consistency, though small in rupee terms, signals financial discipline rather than an income commitment.
Ddev Plastiks Industries Financial Performance Analysis
Operating leverage tells the real story. In FY26, revenue grew 12.2% but PAT grew only 9.2% and EPS 8.8% — profit rose slower than sales, a classic sign of margin compression. Management attributed this to geopolitical tensions disrupting exports and to input-cost inflation, even as volumes rose ~6% and exports jumped 30%. EBITDA growth of about 12% broadly matched revenue, but higher raw-material and finance costs trimmed the flow-through to net profit. Q4FY26 operating margin sat near 9.7%. The takeaway: Ddev Plastiks is scaling well on the top line, but profitability is under mild pressure — a factor to weigh when judging the durability of future dividend growth.
Ddev Plastiks Cash Flow Analysis
Reported profit is an opinion; cash is fact. Ddev Plastiks generates healthy operating cash flow — independent data show its small debt is covered by operating cash flow over 400%, implying OCF in the region of ₹180 crore against a net profit of ₹202 crore. The company is in a heavy capex phase (guided around ₹110 crore for FY26 plus working-capital build), so free cash flow is thinner but still positive enough to fund the payout many times over. Exact FY26 free cash flow is Not Disclosed by Company in the filing reviewed. Crucially, the ₹12.93 crore final dividend is funded from current earnings and internal accruals, not from borrowings or asset sales.
Ddev Plastiks Industries Balance Sheet Strength
Ddev Plastiks runs one of the cleaner balance sheets in its sector. As of March 2026 it held roughly ₹110 crore of cash and investments against total debt of only about ₹42 crore — a net cash position of ~₹68 crore and a debt-to-equity ratio near 0.05. Shareholder funds stood around ₹920 crore, up from ₹835 crore a year earlier. Current assets comfortably exceed current liabilities, and interest cover is strong (EBIT covering interest 12–18x). Against this, the ₹12.93 crore final dividend is trivially small — cash and investments alone cover the final outflow about 8.5x. Balance-sheet risk to the dividend is effectively negligible.
Ddev Plastiks Dividend Sustainability Analysis
Earnings Coverage
EPS ₹19.50 vs final DPS ₹1.25 = ~15.6x cover (6.4% payout). Extremely comfortable.
Operating Cash Flow Coverage
OCF ~₹180 cr vs ₹12.93 cr outflow = 13x+ cover. Dividend funded from operations.
Free Cash Flow Coverage
FCF thinner in capex phase (exact figure Not Disclosed by Company), but positive and multiples of the payout.
Liquidity / Cash Coverage
Cash & investments ~₹110 cr cover the final outflow ~8.5x; net cash balance sheet.
Verdict: Sustainable. On every test — earnings, cash flow and liquidity — the Ddev Plastiks final dividend is trivially covered. The only caveat is that it is small by design, so “sustainable” here means the token payout can easily continue and grow modestly, not that it delivers meaningful income.
Ddev Plastiks Industries Peer Comparison
| Metric | Ddev Plastiks | Plastiblends India |
|---|---|---|
| Dividend Yield | ~0.49% | ~1.35% |
| Payout Ratio | ~6.4% (final) | ~20.6% |
| ROE | ~21.8% | Lower |
| ROCE | ~31% | Lower |
| Balance Sheet | Net cash | Low debt |
Ddev Plastiks pays a lower yield and payout than dividend-oriented peer Plastiblends, but earns superior returns on capital and holds a stronger, net-cash balance sheet. It is prioritising reinvestment over distribution — a reasonable trade-off given its growth runway.
Ddev Plastiks Promoter Impact Analysis
Promoters hold 74.99% of Ddev Plastiks (as of June 2026), near the regulatory ceiling. Of the ₹12.93 crore final-dividend outflow, roughly ₹9.70 crore flows to the promoter group, with only about ₹3.23 crore reaching public and institutional shareholders (FIIs ~1.47%, DIIs ~0.09%, public ~23.46%). Because promoters own three-quarters of the equity, most of any dividend is effectively a transfer to the founding family. However, the sums are small in absolute terms, and the low payout ratio means the company is retaining the vast majority of profit inside the business — which benefits all shareholders through reinvestment. The promoter-benefit angle is worth noting but is not, at these amounts, a governance red flag.
Ddev Plastiks Dividend Taxation Analysis
In India, dividends are taxable in the hands of the shareholder at their income-tax slab rate. Companies deduct TDS at 10% under Section 194 when a shareholder’s total dividend from that company exceeds ₹5,000 in a financial year (20% if PAN is not furnished). The TDS is adjustable against final tax liability.
Worked Example (illustrative — ₹10/share):
Investor holds 1,000 shares, dividend ₹10/share, 30% slab → Gross dividend ₹10,000; TDS @10% ₹1,000 (as it exceeds ₹5,000); tax @30% slab ₹3,000; net in hand ₹7,000.
Applied to Ddev Plastiks (₹1.25/share):
Investor holds 1,000 shares → gross dividend ₹1,250. As this is below ₹5,000, no TDS applies. At a 30% slab, tax is ₹375, leaving ₹875 net — an effective post-tax yield of about 0.34% at the current price.
Key Risks – Ddev Plastiks Industries
- Margin compression: PAT is growing slower than revenue; raw-material (polymer/crude-linked) inflation can further squeeze the ~9–10% operating margin.
- Client concentration in wires & cables: Heavy reliance on a single end-industry makes earnings sensitive to that sector’s capex cycle.
- Execution risk on expansion: Large XLPE and BESS investments must deliver returns; delays or weak utilisation would pressure cash flows.
- Export/geopolitical exposure: ~27–30% of revenue is exports, vulnerable to shipping, tariff and conflict disruptions.
- Very low dividend yield: At ~0.49%, the stock offers negligible income cushion in a market drawdown.
- High promoter holding (74.99%): Limited free float can amplify price volatility and concentrate control.
What To Monitor – Ddev Plastiks Industries
- Operating margin trend: Whether EBITDA margin recovers above 10% as XLPE and value-added grades scale.
- Capacity utilisation: Ramp-up of the 48,000 MTPA XLPE unit and progress toward the FY30 ₹5,000 crore target.
- BESS foray: Actual revenue and capital deployed in the new battery-storage business vs the ₹200–250 crore FY27 guidance.
- Free cash flow: Whether OCF stays ahead of the elevated capex, keeping the balance sheet net-cash.
- Dividend growth vs EPS: If future payout ratios rise, signalling a shift from pure reinvestment toward distribution.
- Export share & realisations: Stability of the 30%-growth export book amid global trade conditions.
Conclusion – Ddev Plastiks Industries Dividend 2026
Positives
- Consistent dividend record since listing, rising to ₹1.75 in FY26
- Extremely well covered (15.6x earnings, ~8.5x cash)
- Net-cash balance sheet, ROE ~21.8%, ROCE ~31%
- Strong reinvestment runway (XLPE, BESS, FY30 target)
Negatives / Watch-outs
- Token yield of ~0.49% — negligible income
- Margin compression; PAT lagging revenue
- ~75% of the payout accrues to promoters
- Export and single-industry concentration risk
In short, the Ddev Plastiks final dividend for FY26 is a safe but symbolic payout. The headline “125%” masks a real yield under half a percent. Read it as a marker of financial health and management confidence, not as income. Investors should weigh the positives, negatives, risks and monitoring factors above and decide for themselves.
Frequently Asked Questions About Ddev Plastiks Dividend
What dividend has Ddev Plastiks announced for FY26?
What is the Ddev Plastiks dividend yield?
What was the Ddev Plastiks dividend record date?
What was the ex-dividend date?
When will the Ddev Plastiks dividend be paid?
Who was eligible for the dividend?
How is the Ddev Plastiks dividend taxed?
Is the Ddev Plastiks dividend sustainable?
What is the Ddev Plastiks dividend history?
How much of the dividend goes to promoters?
What should investors monitor going forward?
Is Ddev Plastiks a good dividend income stock?
Disclaimer – Ddev Plastiks Industries Dividend Analysis
This article is for informational and educational purposes only and does not constitute investment, financial or tax advice, nor a buy, sell or hold recommendation. Figures are drawn from company filings and publicly available sources and may contain errors or become outdated; some keyword and market data points could not be independently verified at the time of writing. Dividend approval, dates and payment are subject to regulatory and shareholder processes. Investors should verify all figures against official NSE/BSE and company disclosures and consult a SEBI-registered adviser before making any decision. ShareBazaar Online and the author accept no liability for actions taken based on this content. Equity investments are subject to market risks.