
Company Overview – Caplin Point Laboratories Limited
Caplin Point Laboratories Limited (NSE: CAPLIPOINT, BSE: 524742, ISIN: INE475E01026) is a Chennai-based, fully integrated pharmaceutical company incorporated in 1990. It manufactures and sources APIs and finished formulations across 36 therapeutic areas, with a strong front-end presence in Latin America, Africa and the United States. On 12 August 2026, Caplin Point Laboratories declared a final dividend for FY2025-26, taking its full-year payout to ₹8 per share. The company remains almost debt-free, cash-generative and promoter-led, with revenue rising to ₹2,187 Cr (consolidated) in FY26. This analysis examines the Caplin Point Laboratories dividend on its merits — yield, coverage, cash backing and sustainability — rather than simply reporting the announcement.
Financial Analysis – Caplin Point Laboratories Limited
Profitability
FY26 consolidated net profit stood at ₹649.73 Cr on revenue of ₹2,187 Cr, with consolidated EPS of ₹84.36. Q1 FY27 (quarter ended June 2026) profit rose to ₹179.09 Cr, up ~18.8% YoY. Return on equity is 20.9% and ROCE 24.2% (Source: Screener.in).
Balance Sheet
The company is almost debt-free, with borrowings of only ~₹221 Cr against reserves of ~₹3,355 Cr. Consolidated unallocated (treasury) assets were ₹1,471 Cr in FY26. Operating margins are strong at ~35%, supporting comfortable dividend capacity for Caplin Point Laboratories.
Caplin Point Laboratories Dividend History Table
| Financial Year | Interim (₹) | Final (₹) | Total DPS (₹) | Payout %* |
|---|---|---|---|---|
| FY2025-26 | 4.00 | 4.00 | 8.00 | ~9% |
| FY2024-25 | 2.50 | 3.00 | 5.50 | ~8% |
| FY2023-24 | 2.50 | 2.50 | 5.00 | ~8% |
| FY2022-23 | 2.00 | 2.00 | 4.00 | ~9% |
| FY2021-22 | 1.50 | 2.00 | 3.50 | ~10% |
| FY2020-21 | 1.50 | 1.50 | 3.00 | ~9% |
*Payout % on consolidated PAT (Source: Screener.in). FY26 amounts from the company's 12 August 2026 exchange filing; earlier instalments per exchange/aggregator dividend records. Long-run trend: dividend has risen from ₹0.20 per share (FY2011) to ₹8.00 (FY2026) — Source: Simply Wall St.
Expert Commentary – Caplin Point Laboratories Dividend
The Caplin Point Laboratories dividend is best read as a token shareholder return, not an income play. At ₹8 per share, the FY26 payout yields just ~0.29% on a market price near ₹2,758, versus a pharma peer average of ~0.7% (Source: Simply Wall St). The low yield is a deliberate capital-allocation choice: management retains over 90% of profit to fund capacity expansion, US front-end build-out and R&D. What makes the dividend notable is its quality of backing — it is covered 10.5x by consolidated earnings and roughly 24x by treasury assets. Investors should value Caplin Point Laboratories for compounding and balance-sheet strength; the dividend is a modest, highly secure bonus rather than the core reason to hold.
Caplin Point Laboratories Dividend Outlook
With profit compounding at ~21% CAGR over five years and a payout ratio anchored below 10%, absolute dividends from Caplin Point Laboratories are likely to keep rising in rupee terms even as the yield stays low. The FY26 step-up to ₹8 (from ₹5.50 in FY25) — a ~45% increase — signals growing confidence in cash generation. Management's stated priorities remain the US injectables ramp, new geographies and automation, all internally funded. Barring a large acquisition, the company can comfortably sustain and grow the dividend. Income-focused investors should not expect a yield re-rating; growth-focused investors gain a rising, well-covered payout alongside capital appreciation potential.
Dividend Snapshot – Caplin Point Laboratories Limited
| Dividend Type | Final Dividend (FY2025-26) |
| Final Dividend | ₹4.00 per share (200%) |
| Interim (already paid) | ₹4.00 per share (200%) |
| Total FY26 Dividend | ₹8.00 per share (400%) |
| Face Value | ₹2.00 |
| Total FY26 Yield | ~0.29% |
| Final Dividend Outflow | ₹30.40 Cr |
| Total FY26 Outflow | ₹60.81 Cr |
| Payout Ratio (Consolidated) | ~9.4% |
| Earnings Coverage | 10.5x |
Dividend Announcement Summary – Caplin Point Laboratories Limited
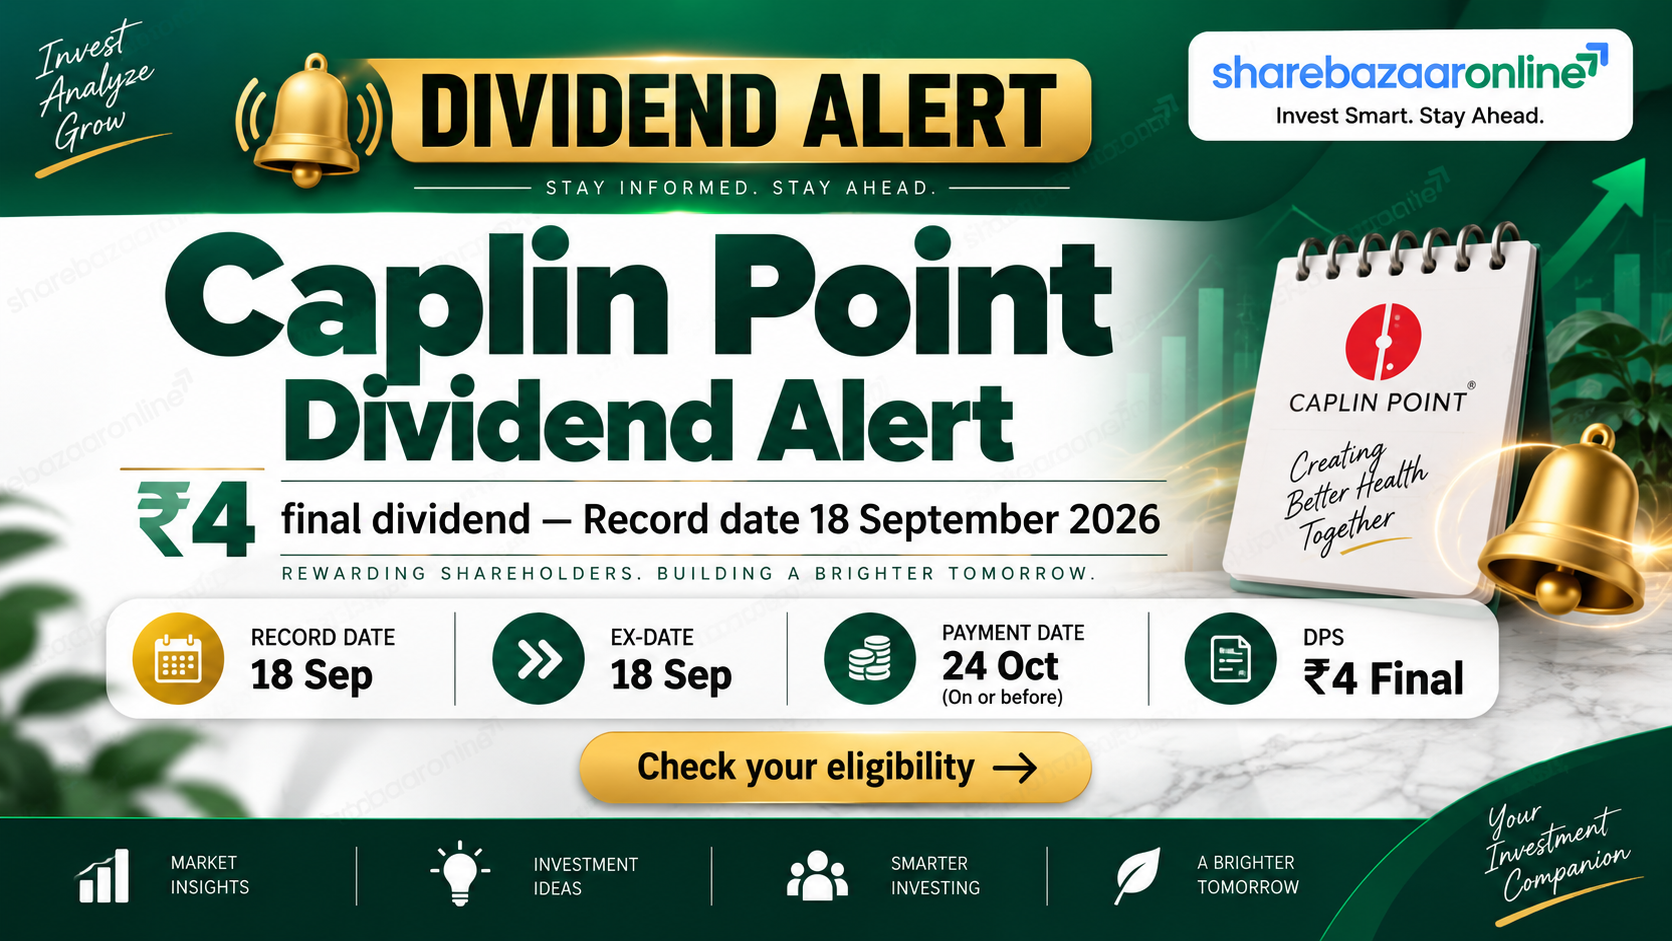
At its board meeting on 12 August 2026, the Board of Caplin Point Laboratories recommended a final dividend of ₹4 per equity share (200%) of face value ₹2, for the financial year ended 31 March 2026. This is in addition to the ₹4 interim dividend declared on 14 May 2026 and paid on 8 June 2026, bringing the total FY2025-26 dividend to ₹8 per share (400%). The final dividend is subject to shareholder approval at the 35th Annual General Meeting on 25 September 2026 and, once approved, will be paid on or before 24 October 2026. The company also approved key management re-appointments at the same meeting.
Key Dates Timeline – Caplin Point Laboratories Dividend
| Event | Date |
|---|---|
| Announcement Date | 12 August 2026 |
| Record Date | 18 September 2026 |
| Ex-Dividend Date | 18 September 2026 |
| 35th AGM (Approval) | 25 September 2026 |
| Payment Date | On or before 24 October 2026 |
Record/ex-date and payment window sourced from company exchange filings and market data. Shares must be held as of the record date to qualify for the final dividend.
Caplin Point Laboratories Dividend Yield Analysis
On the current market price of ~₹2,758 (21 September 2026), the ₹8 total FY26 dividend yields ~0.29%; the ₹4 final dividend alone yields ~0.15%. On the announcement-date price of ₹2,506 (12 August 2026), the total-year yield was ~0.32%. This is well below the Indian market average and the pharma peer average of ~0.7% (Source: Simply Wall St). The low yield is not a warning sign — it reflects a rising share price and a deliberately low payout, not a weak or cut dividend. For Caplin Point Laboratories, yield is a poor lens; coverage and growth matter more.
Caplin Point Laboratories Dividend History Analysis
Caplin Point Laboratories is a consistent and growing dividend payer. Absolute dividend per share has climbed steadily from ₹3.00 (FY21) to ₹8.00 (FY26), and from just ₹0.20 in FY2011 over the long run (Source: Simply Wall St). There have been no dividend cuts or suspensions in the last decade, and the company has moved to a twice-yearly (interim + final) rhythm. The payout ratio has stayed disciplined in a ~8-12% band, meaning rising dividends have been funded entirely by rising profits, not by stretching the balance sheet. On this record, Caplin Point Laboratories classifies clearly as a Consistent Payer with a progressive dividend policy.
Caplin Point Laboratories Financial Performance Analysis
Growth has been both strong and profitable. Consolidated revenue rose from ₹1,061 Cr (FY21) to ₹2,187 Cr (FY26), a ~15.6% five-year CAGR, while net profit grew from ₹251 Cr to ₹649.73 Cr, a ~21% CAGR (Source: Screener.in). Crucially, profit is growing faster than revenue — operating margin expanded to ~35% — so there is no operating-leverage red flag here. Q1 FY27 continued the trend with revenue up ~20% YoY and PAT up ~18.8% YoY. This widening-margin, cash-rich profile is exactly what underpins Caplin Point Laboratories' ability to raise dividends while still funding heavy growth capex.
Caplin Point Laboratories Cash Flow Analysis
Reported profits are backed by real cash. FY26 operating cash flow was ₹523 Cr against consolidated PAT of ₹649.73 Cr — a CFO/PAT conversion of ~80%, healthy for a growth pharma company carrying rising inventory and receivables. Free cash flow was ₹275 Cr after capex. Against a total dividend outflow of just ₹60.81 Cr, the dividend is covered 8.6x by operating cash flow and 4.5x by free cash flow (Source: Screener.in). This confirms the Caplin Point Laboratories dividend is funded entirely from current cash earnings — not from reserves, asset sales or borrowings. One watch-point: receivable and inventory days have been rising, which is worth monitoring.
Caplin Point Laboratories Balance Sheet Strength
The balance sheet is a core strength. Caplin Point Laboratories is almost debt-free, with borrowings of only ~₹221 Cr against reserves of ~₹3,355 Cr and consolidated unallocated treasury assets of ₹1,471 Cr in FY26. Balance-sheet investments stood at ₹859 Cr. Set against the ₹60.81 Cr total dividend outflow, treasury assets alone cover the payout ~24x, and investments ~14x. With ROE of 20.9% and ROCE of 24.2%, the company earns high returns on this capital. There is no scenario in which the current dividend strains the balance sheet of Caplin Point Laboratories.
Caplin Point Laboratories Dividend Sustainability Analysis
Testing the FY26 dividend against four sustainability pillars for Caplin Point Laboratories:
- Cash position: Treasury covers the payout ~24x — overwhelmingly affordable.
- Free cash flow: FCF of ₹275 Cr covers the ₹60.81 Cr outflow 4.5x.
- Debt: Almost debt-free; dividends are not funded by borrowing.
- Earnings trend: Profit compounding ~21%; payout only ~9%.
Verdict: Sustainable. Every metric points to a dividend that is not only safe but has substantial room to grow.
Caplin Point Laboratories Peer Comparison
| Company | Div Yield | Payout | ROE | ROCE |
|---|---|---|---|---|
| Caplin Point Laboratories | ~0.29% | ~9% | 20.9% | 24.2% |
| Divi's Laboratories | ~0.7% | ~30% | ~17% | ~22% |
| Dr Reddy's Labs | ~0.7% | ~12% | ~19% | ~22% |
| Cipla | ~0.5% | ~15% | ~17% | ~20% |
Caplin Point Laboratories carries the lowest yield and payout in the group but among the highest ROE/ROCE. The peer average yield is ~0.7% (Source: Simply Wall St); Caplin's ~0.29% reflects growth-first capital allocation, not weaker fundamentals.
Peer figures are indicative market estimates and should be verified against the latest filings before use.
Caplin Point Laboratories Promoter Impact Analysis
Promoters hold 70.57% of Caplin Point Laboratories (June 2026), so the bulk of the dividend flows to the promoter group. Of the ₹60.81 Cr total FY26 payout, promoters receive ~₹42.91 Cr and public/minority shareholders ~₹17.90 Cr. FIIs hold 5.76% and DIIs 2.49%. Because promoter holding is high and stable — and because the payout ratio is low — the dividend is not being used to extract cash disproportionately; retained earnings still overwhelmingly fund reinvestment that benefits all shareholders. The alignment is reasonable: promoters gain the most in absolute rupees, but only ~9% of profit is distributed, leaving 91% compounding inside the business.
Caplin Point Laboratories Dividend Taxation Analysis
Since FY2020-21, dividends in India are taxable in the hands of the investor at their applicable income-tax slab rate. The company deducts TDS at 10% if total dividend paid to a resident shareholder exceeds ₹5,000 in a financial year (20% without PAN). The TDS is adjustable against final tax liability.
Worked Example
- Investor owns 1,000 shares; dividend ₹10/share (illustrative)
- Gross dividend = ₹10,000
- TDS @10% (crosses ₹5,000) = ₹1,000 deducted at source
- Tax @30% slab = ₹3,000 total liability
- Net in-hand dividend = ₹7,000
For the actual FY26 dividend of ₹8/share on 1,000 shares (₹8,000 gross), a 30%-slab investor keeps ~₹5,600 after tax. Post-tax effective yield at CMP is therefore ~0.20%.
Key Risks – Caplin Point Laboratories
- Very low yield: At ~0.29%, the stock offers negligible dividend income — unsuitable for income-seeking investors.
- Rising working capital: Debtor days rose to 138 and inventory days to 181 in FY26, tying up cash and pressuring future free cash flow.
- Geographic concentration: Heavy reliance on Latin America and emerging markets exposes revenue to currency and regulatory shocks.
- US/regulatory dependence: Growth hinges on USFDA approvals and the US injectables ramp; delays or observations could hit earnings.
- Valuation risk: At a P/E of ~31x, any earnings miss could de-rate the stock sharply, given the thin dividend cushion.
What To Monitor – Caplin Point Laboratories
- Payout ratio trend: Whether management lifts the ~9% payout as the cash pile grows.
- Working-capital cycle: Cash conversion cycle (194 days in FY26) — is it stabilising or worsening?
- Free cash flow growth: Sustained FCF above ₹275 Cr to keep funding both capex and dividends.
- US business scale-up: Caplin Steriles USFDA approvals and revenue contribution.
- Capital deployment: How the ~₹1,471 Cr treasury is used — buyback, acquisition, higher dividend or capex.
Conclusion – Should You Consider Caplin Point Laboratories for Dividend Income?
Positives: The Caplin Point Laboratories dividend of ₹8 for FY26 is exceptionally well-secured — covered 10.5x by earnings, 4.5x by free cash flow and ~24x by treasury — from an almost debt-free, high-return (ROE 20.9%, ROCE 24.2%), fast-growing business. Negatives: The yield of ~0.29% is far below peers, working capital is stretching, and the valuation leaves little margin for error. In short, this is a growth compounder with a token, rising dividend, not an income stock. Dividend-income seekers will find the yield inadequate; long-term growth investors get a secure, progressive payout as a bonus. Weigh these positives, negatives and risks against your own objectives.
Frequently Asked Questions About Caplin Point Laboratories Dividend
What dividend has Caplin Point Laboratories announced?
What is the Caplin Point Laboratories dividend yield?
What is the record date for the Caplin Point Laboratories dividend?
What is the ex-dividend date?
When will the Caplin Point Laboratories dividend be paid?
Who is eligible for the dividend?
How is the Caplin Point Laboratories dividend taxed?
Is the Caplin Point Laboratories dividend sustainable?
What is the Caplin Point Laboratories dividend history?
What should investors monitor going forward?
Is Caplin Point Laboratories a good dividend stock for income?
How much dividend do promoters of Caplin Point Laboratories receive?
Disclaimer
This article on the Caplin Point Laboratories dividend is for informational and educational purposes only and does not constitute investment advice or a recommendation to buy, sell or hold any security. Figures are sourced from the company's exchange filings and public financial databases (Screener.in, Simply Wall St and others) as cited, and some market figures are indicative and may change. ShareBazaar Online does not guarantee accuracy or completeness. Investments in securities are subject to market risks; please read all related documents carefully and consult a SEBI-registered financial advisor before investing.