
Kajaria Ceramics Dividend 2026 – Company Overview
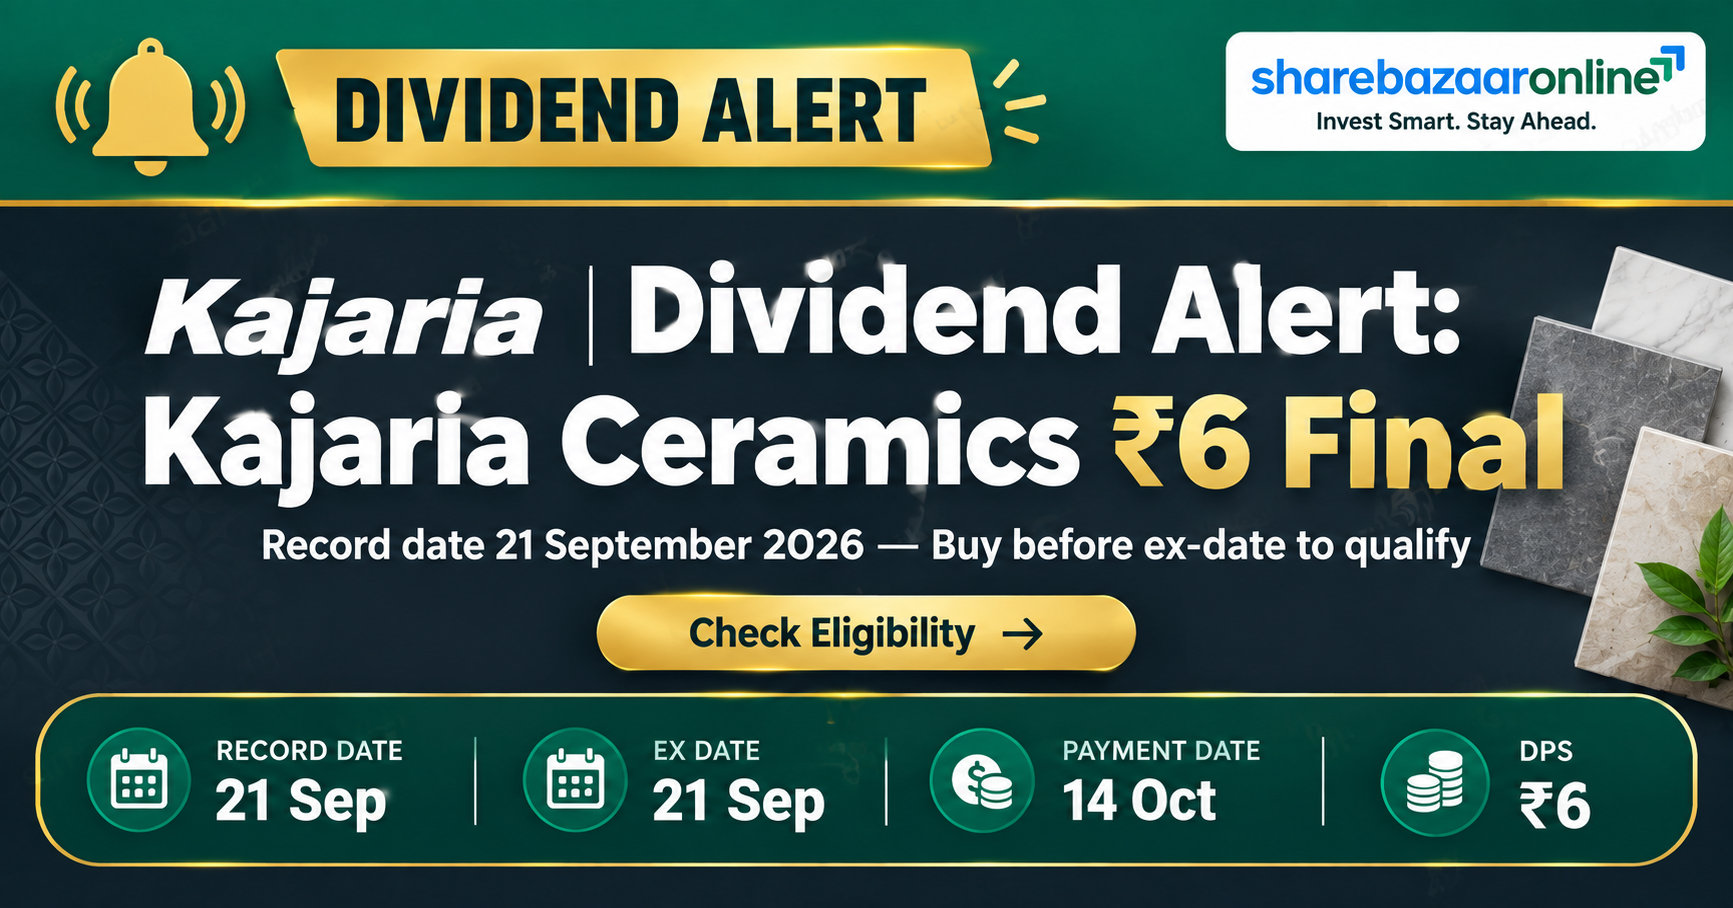
Kajaria Ceramics Limited (NSE: KAJARIACER, BSE: 500233, ISIN: INE217B01036) is India's largest manufacturer of ceramic and vitrified tiles and the 8th largest globally. Its portfolio spans ceramic wall & floor tiles, polished and glazed vitrified tiles, bathware, and plywood & laminates. On April 30, 2026, the Board recommended a final dividend of ₹6 per share (face value ₹1) for FY2025-26, subject to approval at the 40th AGM. With a market capitalisation near ₹18,846 crore and a nearly debt-free balance sheet, Kajaria Ceramics remains a structural play on India's housing and renovation demand. This Kajaria Ceramics dividend analysis examines whether the payout is affordable, sustainable, and how it compares with tile-sector peers.
Kajaria Ceramics Financial Analysis
Kajaria Ceramics closed FY2025-26 (consolidated) with revenue of ₹4,830 crore and net profit of ₹487 crore, a sharp +62% profit recovery from FY25's ₹300 crore. Operating profit rose +37% to ₹869 crore, lifting the operating margin to 18% from 14%. EPS jumped to ₹30.48 from ₹18.48. The company earns a healthy ROCE of 23.4% and ROE of 17.9%, and is almost debt-free. The weak spot is the top line: five-year revenue growth is only ~7% CAGR, reflecting soft tile realisations and competitive pressure. The FY26 profit surge is largely a margin-led rebound rather than volume acceleration — an important nuance for anyone evaluating the Kajaria Ceramics dividend.
Kajaria Ceramics Dividend History Table (Last 10 Years)
| Financial Year | Total DPS (₹) | Payout Ratio | Trend |
|---|---|---|---|
| FY2017 | ~3.00 | 19% | Base |
| FY2018 | ~3.00 | 20% | Stable |
| FY2019 | ~3.00 | 21% | Stable |
| FY2020 | ~3.00 | 19% | Stable |
| FY2021 | ~10.00 | 52% | Step-up |
| FY2022 | 11.00 | 46% | High |
| FY2023 | 9.00 | 42% | Trim |
| FY2024 | 12.00 | 45% | Rise |
| FY2025 | 9.00 | 49% | Trim |
| FY2026 | 14.00 (₹8 interim + ₹6 final) | 46% | Record high |
DPS reconstructed from consolidated payout ratios and declared interim/final dividends. Source: Screener.in, TipRanks. Figures for FY17–FY21 are approximate.
Expert Commentary on Kajaria Ceramics Dividend
The standout FY26 story is not the ₹6 final dividend alone — it is the combined capital return. Alongside the dividend, Kajaria Ceramics approved its first-ever buyback of ₹296.70 crore at ₹1,380 per share (record date June 29, 2026). Together, dividends of ₹223.7 crore and the buyback total ₹520 crore — roughly 107% of FY26 PAT and 92% of free cash flow. This signals a management confident in cash generation and short of large greenfield needs. The trade-off: with revenue growth muted at ~7%, returning nearly all profit leaves less internal fuel for aggressive expansion. For income-focused investors, the dividend is comfortably covered; for growth investors, the heavy payout hints at a maturing, cash-cow phase.
Kajaria Ceramics Dividend Outlook & Future View
Kajaria Ceramics enters FY27 with margin momentum — Q1 FY27 operating margin touched 20% and PAT reached ₹171 crore. If tile demand from housing and renovation holds and gas/energy costs stay contained, the recent ~46% payout band looks maintainable, supported by strong operating cash flow of ₹664 crore. The company is also investing in captive solar and wind power (up to ₹12.15 crore in Sunsure) to protect margins. Key swing factors are realisation recovery, import competition, and whether management repeats buybacks. On current trajectory, the Kajaria Ceramics dividend appears set to stay in the ₹12–₹15 per year range, though shareholders should treat forward figures as scenario-based, not guaranteed.
Dividend Snapshot – Kajaria Ceramics Limited
Dividend Type
Final Dividend
Dividend Per Share
₹6.00 (600% of ₹1 face value)
Final Dividend Yield (at CMP ₹1,199)
0.50%
FY26 Total Yield (₹14 at CMP)
1.17%
Record Date
21 September 2026
Payment Date
On or before 14 October 2026
Kajaria Ceramics Dividend Announcement Summary
Per the exchange filing dated August 12, 2026, the Board of Kajaria Ceramics, at its meeting on April 30, 2026, recommended a final dividend of ₹6 per equity share (face value ₹1) for FY2025-26. The dividend is subject to shareholder approval at the 40th Annual General Meeting, to be held via video conferencing on Tuesday, September 15, 2026 at 1:00 PM IST. The company fixed Monday, September 21, 2026 as the record date to determine eligible members. If declared, the dividend will be paid on or before Wednesday, October 14, 2026. The filing was signed by Vinit Kumar, General Counsel & Company Secretary. This is a routine final dividend within Kajaria Ceramics' established payout policy.
Kajaria Ceramics Dividend – Key Dates Timeline
Board Recommendation
30 April 2026
40th AGM
15 September 2026, 1:00 PM IST (VC/OAVM)
Ex-Dividend Date
21 September 2026 (aligned with record date)
Record Date
21 September 2026
Payment Date
On or before 14 October 2026
Financial Year
FY2025-26
Kajaria Ceramics Dividend Yield Analysis
At the current market price of ₹1,199 (21 Sep 2026, Screener.in), the ₹6 final dividend gives a yield of just 0.50%, while the full FY26 payout of ₹14 yields 1.17%. This is a modest yield — Kajaria Ceramics is a growth-and-quality compounder, not a high-yield stock. Importantly, the low yield reflects a strong, elevated share price, not a weak dividend: the DPS itself is at a record ₹14. The exact NSE close on the April 30, 2026 announcement date was not separately verified in this research, so the announcement-date yield is not stated. Yield-focused investors should note that the real return here has historically come from capital appreciation plus a rising dividend, rather than a high cash yield.
Kajaria Ceramics Dividend History Analysis
Kajaria Ceramics is a consistent dividend payer with an uninterrupted record over the past decade — no suspensions, no zero years. The payout ratio stepped up structurally from ~19-21% (FY17–FY20) to a 42–52% band from FY21 onward, marking a shift from a reinvestment phase to a balanced capital-return phase. Absolute DPS has trended up from ~₹3 to a record ₹14 in FY26, though the path is not perfectly linear — FY23 (₹9) and FY25 (₹9) saw trims that tracked softer earnings. This makes Kajaria Ceramics a consistent but earnings-linked payer: the dividend flexes with profit rather than following a fixed rupee commitment, so it is best described as a reliable, growing, but variable payout.
Kajaria Ceramics Financial Performance Analysis (Operating Leverage)
FY26 is a textbook operating-leverage recovery. Revenue grew a modest +4.2% (₹4,635cr → ₹4,830cr), but operating profit surged +37% (₹635cr → ₹869cr) and PAT jumped +62% (₹300cr → ₹487cr). The gap between flat sales and soaring profit is explained by margin expansion: OPM rose from 14% to 18% as energy costs eased and product mix improved, while FY25 had been depressed by a weak Q4 (margin had fallen to 11%). In short, profits rose because each rupee of sales became more profitable, not because volumes exploded. The caution: this leverage cuts both ways — if input costs or realisations reverse, profit can fall faster than revenue, as FY25 showed.
Kajaria Ceramics Cash Flow Analysis
Cash quality is a clear strength. In FY26, Kajaria Ceramics generated operating cash flow of ₹664 crore against reported PAT of ₹487 crore — a CFO/PAT of ~136%, confirming that profits are backed by real cash, not just accruals. Free cash flow was ₹563 crore, the highest in years. The FY26 dividend outflow of ₹223.7 crore is funded entirely from current-year earnings and cash flow — not from reserves, asset sales, or borrowings. Even after adding the ₹296.70 crore buyback, total returns of ₹520 crore stay within FCF plus modest cash draw. Receivables discipline is intact (debtor days ~47), so the dividend rests on a genuinely cash-generative base.
Kajaria Ceramics Balance Sheet Strength
Kajaria Ceramics runs a fortress balance sheet. Against a net worth of ₹3,066 crore (book value ~₹192/share), total borrowings are just ₹229 crore, giving a debt-to-equity of only 0.08 — effectively debt-free. Net debt is a negligible ₹190 crore. This is critical for dividend safety: the company is not paying dividends by taking on leverage. Debt has stayed low and stable even through a heavy FY26 capital-return year, and interest cost of ₹23 crore is trivial versus ₹869 crore operating profit. A low-debt, cash-rich structure means the payout is not competing with debt-servicing obligations — a key differentiator versus more leveraged building-material peers.
Kajaria Ceramics Dividend Sustainability Analysis
Dividend Coverage (EPS ₹30.48 / DPS ₹14)
2.18x
FCF Coverage of FY26 Dividend
2.52x
On every test, the Kajaria Ceramics dividend looks well-supported. Earnings cover the full ₹14 payout 2.18 times; free cash flow covers it 2.5 times; the balance sheet is near debt-free; and earnings, while cyclical, are on an upswing. The only moderating factor is the earnings-linked variability — the company trims DPS in weak years (FY23, FY25), so the payout is dependable in direction but not fixed in amount. Overall assessment: Sustainable, with the caveat that the rupee amount will track the profit cycle rather than grow every single year.
Kajaria Ceramics Peer Comparison
| Company | Div Yield | Payout | ROE | ROCE | Balance Sheet |
|---|---|---|---|---|---|
| Kajaria Ceramics | ~1.17% | ~46% | 17.9% | 23.4% | Near debt-free |
| Somany Ceramics | ~0.66% | ~20% | ~9–12% | ~14% | Moderate debt |
| Cera Sanitaryware | ~1.08% | ~34% | ~18% | ~18% | Cash-rich |
Kajaria Ceramics leads its tile peers on payout ratio, ROCE and balance-sheet quality. Its yield sits between Somany (lower payout) and Cera. The takeaway: within the ceramics/building-materials pack, Kajaria Ceramics offers the most generous and best-covered dividend policy, backed by superior capital efficiency. Source: Screener.in, TipRanks.
Kajaria Ceramics Promoter Impact Analysis
Promoters hold 47.69% of Kajaria Ceramics (Jun 2026). On the ₹6 final dividend (outflow ~₹95.9 crore), promoters receive about ₹45.7 crore; on the full FY26 payout of ₹223.7 crore, their share is roughly ₹106.7 crore. Public and institutional shareholders — who own the majority 52.31% — collectively receive the larger slice (~₹117 crore of the full-year payout). Because the payout is a flat per-share amount, every shareholder is treated identically; there is no structural bias toward promoters. The buyback, being a tender offer open to all, is likewise pro-rata. So while promoters benefit meaningfully in absolute rupees, minority shareholders are the larger aggregate beneficiary of the Kajaria Ceramics dividend.
Kajaria Ceramics Dividend Taxation Analysis
In India, dividends are taxable in the hands of the investor at their income-tax slab rate (there is no separate dividend distribution tax). The company deducts TDS at 10% if total dividend paid to a resident shareholder exceeds ₹5,000 in a financial year (₹10,000 threshold applies from FY26 under recent Budget changes — verify with your tax advisor). NRIs face TDS at 20% plus surcharge.
Worked example — investor holding 1,000 shares, ₹6 final dividend, 30% slab:
- Gross dividend: 1,000 × ₹6 = ₹6,000
- TDS deducted at 10% (as > ₹5,000): ₹600 (adjustable against final tax)
- Tax at 30% slab: ₹1,800
- Net in-hand dividend after tax: ₹4,200
- Effective post-tax yield on final dividend (at CMP ₹1,199): ~0.35%
Kajaria Ceramics Dividend – Key Risks
- Earnings-linked payout: DPS is trimmed in weak years (FY23, FY25), so the dividend is not a fixed commitment.
- Weak revenue growth: ~7% five-year sales CAGR limits how fast the dividend base can compound.
- Margin volatility: gas/energy prices and tile realisations swing margins sharply, as FY25's 11% Q4 margin showed.
- Import & competitive pressure: cheap imports and Morbi-cluster competition can cap pricing power.
- Low absolute yield: at ~1.17%, the stock offers limited cash income; total return depends on price appreciation.
- Heavy FY26 capital return (~107% of PAT via dividend + buyback) leaves thinner retained cash for large expansion.
Kajaria Ceramics Dividend – What To Monitor
- Tile volume growth — watch whether volumes accelerate beyond the ~4% revenue growth seen in FY26.
- Operating margin trend — sustainability of the 18–20% OPM band (energy costs, product mix).
- Payout ratio — whether management holds the ~46% band or lets it drift with earnings.
- Free cash flow — continued FCF above ₹500 crore keeps the dividend comfortably funded.
- Capex & expansion plans — how the company balances growth investment against buybacks/dividends.
- Repeat buybacks — whether the FY26 buyback becomes a recurring return tool.
Should You Consider Kajaria Ceramics for Dividend Income? – Conclusion
The Kajaria Ceramics ₹6 final dividend caps a record FY26 payout of ₹14, backed by a 62% profit rebound, ₹563 crore free cash flow, a near debt-free balance sheet, and a first-ever ₹297 crore buyback. On sustainability, coverage and balance-sheet quality, the dividend scores strongly. The honest caveats: the yield is low (~1.17%), revenue growth is soft, and the payout flexes with the profit cycle. This is a quality compounder that also pays a growing, well-covered dividend — attractive for investors seeking capital appreciation with a rising income kicker, less so for those chasing pure high yield. Weigh the positives, negatives, risks and monitoring points above, and decide based on your own objectives.
Frequently Asked Questions About Kajaria Ceramics Dividend
What dividend has Kajaria Ceramics announced for FY2025-26?
What is the Kajaria Ceramics dividend yield?
What is the record date for the Kajaria Ceramics dividend?
What is the ex-dividend date for Kajaria Ceramics?
When will Kajaria Ceramics pay the dividend?
Who is eligible for the Kajaria Ceramics dividend?
How is the Kajaria Ceramics dividend taxed?
Is the Kajaria Ceramics dividend sustainable?
What is the Kajaria Ceramics dividend history?
Did Kajaria Ceramics announce a buyback along with the dividend?
What should investors monitor in Kajaria Ceramics?
How does the Kajaria Ceramics dividend compare with peers?
Disclaimer
This article is for informational and educational purposes only and does not constitute investment, financial, or tax advice, nor a buy, sell, or hold recommendation. Figures are sourced from the company's exchange filing, Screener.in, TipRanks, and public financial data as of September 2026, and may contain errors or become outdated. Dividend approval is subject to the 40th AGM. Market investments carry risk; please consult a SEBI-registered advisor and verify all data independently before investing. ShareBazaar Online is not liable for any losses arising from the use of this information.