
Company Overview – Indian Hotels Company Limited (IHCL)
Indian Hotels Company Limited (IHCL), a Tata Group flagship, is India’s largest hospitality company operating the iconic Taj, Vivanta, SeleQtions, and Ginger brands. Listed on the NSE (INDHOTEL) and BSE (500850) with ISIN INE053A01029, the company commands a market capitalisation exceeding ₹1,06,000 Crore at the current price of ₹746.30. IHCL operates 300+ hotels across 130+ locations in 12 countries. The promoter group – Tata Sons and affiliates – holds 38.12% equity. For FY26, IHCL reported consolidated revenue of ₹9,689 Crore and profit after tax of ₹2,247 Crore, reflecting the strongest financial year in its century-long history. The company’s face value is ₹1 per share.
Indian Hotels Financial Analysis – FY26 Consolidated Performance
Revenue & Profitability
| Revenue from Operations | ₹9,689 Cr |
| EBITDA | ₹3,197 Cr |
| Operating Profit Margin | 33.0% |
| Net Profit (PAT) | ₹2,247 Cr |
| PAT (Owners) | ₹2,084 Cr |
Per-Share & Return Metrics
| EPS (Consolidated) | ₹14.64 |
| EPS (Standalone) | ₹14.13 |
| Return on Equity | 14.2% |
| Return on Capital Employed | 17.1% |
| Debt-to-Equity | 0.22x |
Indian Hotels Dividend History – Last 10 Years
| Financial Year | DPS (₹) | Dividend % | Type | YoY Growth |
|---|---|---|---|---|
| FY26 | ₹3.25 | 325% | Final | +44.4% |
| FY25 | ₹2.25 | 225% | Final | +28.6% |
| FY24 | ₹1.75 | 175% | Final | +16.7% |
| FY23 | ₹1.50 | 150% | Final | +275.0% |
| FY22 | ₹0.40 | 40% | Final | Resumed |
| FY21 | ₹0.00 | 0% | – | Suspended |
| FY20 | ₹0.00 | 0% | – | Suspended |
| FY19 | ₹0.25 | 25% | Final | –37.5% |
| FY18 | ₹0.40 | 40% | Final | +14.3% |
| FY17 | ₹0.35 | 35% | Final | +29.6% |
| FY16 | ₹0.27 | 27% | Final | – |
Source: IHCL Annual Reports, TipRanks. Face Value: ₹1 per share throughout.
Expert Commentary – Indian Hotels Dividend Decision
IHCL’s decision to raise the dividend by 44.4% to ₹3.25 per share signals management confidence in the company’s earnings trajectory. The ₹462.61 Crore total outflow represents just 22.2% of consolidated owners’ PAT and 18.7% of operating cash flow – leaving substantial headroom for reinvestment. However, the 325% headline on a ₹1 face value creates a perception gap: the actual dividend yield is only 0.44% at the current market price of ₹746.30. This is the face-value illusion – a 325% dividend sounds spectacular but delivers less than a savings account on a per-rupee-invested basis. What truly matters is that IHCL has delivered a 4-year DPS CAGR of 68.8% since resuming dividends post-COVID, demonstrating a credible progressive dividend policy backed by real cash flows.
Indian Hotels Future Outlook – Dividend Growth Prospects
IHCL’s ambitious expansion plan targets 300+ operational hotels by FY28, with a strong pipeline of new-brand and management-contract properties. The domestic travel boom, rising premium-segment demand, and international tourism recovery provide structural revenue tailwinds. With a conservative 22.2% payout ratio and 0.22x debt-to-equity, management retains significant flexibility to simultaneously fund expansion and grow dividends. Risks include cyclical hospitality demand, rising operating costs (employee expenses grew faster than revenue in FY26), and competitive intensity from new entrants. If IHCL sustains 15–20% PAT growth, the current payout ratio suggests dividends could reach ₹4–5 per share by FY28–FY29, though this is a projection, not a guarantee. Investors should track occupancy rates, average room rates, and new hotel openings as lead indicators.
Dividend Snapshot – Indian Hotels Company Limited
Dividend Details
| Dividend Type | Final Dividend |
| Dividend Per Share | ₹3.25 |
| Dividend % | 325% |
| Face Value | ₹1 |
| Financial Year | FY 2025–26 |
| Total Dividend Outflow | ₹462.61 Cr |
Market & Yield Data
| CMP (Announcement Date) | ₹664.80 |
| Latest CMP | ₹746.30 |
| Announcement Yield | 0.49% |
| Current Yield | 0.44% |
| Payout Ratio | 22.2% |
| Shares Outstanding | 142.34 Cr |
Indian Hotels Dividend Announcement Summary – FY26
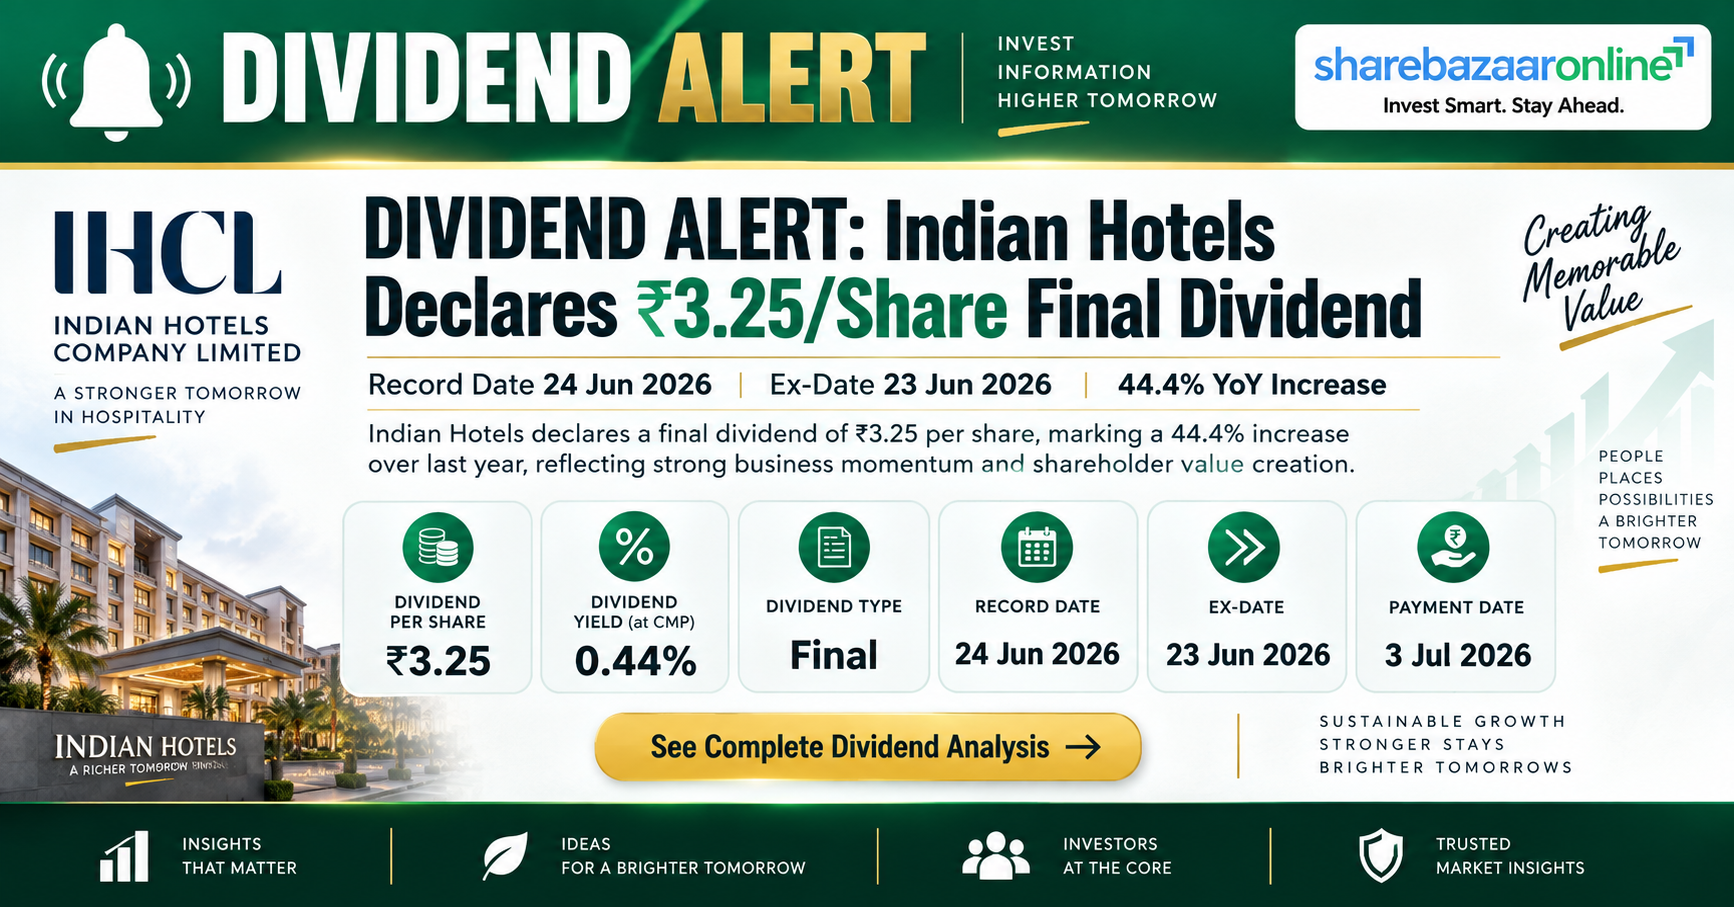
On 11 May 2026, the Board of Directors of Indian Hotels Company Limited recommended a final dividend of ₹3.25 per equity share (325% on the face value of ₹1) for the financial year ended 31 March 2026. The recommendation was made at the board meeting that also approved the audited standalone and consolidated financial results for Q4 FY26 and the full year. The dividend was subsequently approved by shareholders at the Annual General Meeting held on 30 June 2026. This represents a 44.4% increase over the FY25 dividend of ₹2.25 per share, and marks the fourth consecutive year of dividend increases since IHCL resumed payouts in FY22 after the COVID-19 suspension. The total outflow of ₹462.61 Crore was comfortably funded from FY26 earnings and free cash flow.
Indian Hotels Dividend Key Dates Timeline
Announcement Date
11 May 2026 (Board Meeting)
Ex-Dividend Date
23 June 2026 (T+1 Settlement)
Record Date
24 June 2026
AGM Date
30 June 2026 (Approved)
Payment Date
3 July 2026
Note: The ex-date of 23 June 2026 is inferred under T+1 settlement rules (one trading day before the record date). Shareholders who held IHCL shares on or before 20 June 2026 (the last trading day before ex-date) were eligible for this dividend.
Indian Hotels Dividend Yield Analysis – The Face-Value Reality
IHCL’s 325% dividend sounds extraordinary – but this percentage is calculated on the ₹1 face value, not on the market price investors actually pay. At the announcement-date price of ₹664.80, the actual yield was just 0.49%. At the current market price of ₹746.30, the yield drops further to 0.44%. This is the classic face-value illusion that traps uninformed investors. For context, a 1-year fixed deposit currently offers 6.5–7.5%, making IHCL’s dividend yield roughly 15x lower than a bank FD. However, dividend yield alone does not capture the full picture – IHCL’s stock price has appreciated significantly, and the 44.4% YoY DPS growth suggests management is progressively returning more capital to shareholders as earnings scale.
Indian Hotels Dividend History Analysis – From Suspension to Record Payouts
IHCL’s dividend history reveals a cyclical payer that has transformed into a consistent growth payer. Pre-COVID dividends were modest (₹0.25–0.40 range). The pandemic forced a two-year suspension (FY20–FY21) – understandable given hospitality was among the hardest-hit sectors. Since resumption in FY22 at ₹0.40, dividends have grown every single year: ₹0.40 → ₹1.50 → ₹1.75 → ₹2.25 → ₹3.25. The 4-year DPS CAGR of 68.8% is exceptional. The 3-year CAGR of 29.4% is more sustainable as a forward indicator. Critically, these increases have been backed by real earnings growth – the payout ratio has remained steady around 20–23%, meaning higher dividends reflect higher profits, not aggressive cash distribution. Classification: Consistent Growth Payer (post-FY22).
Indian Hotels Financial Performance Analysis – FY26
Revenue & Margin Trend
Consolidated revenue grew to ₹9,689 Crore in FY26, driven by strong occupancy rates and average room rate improvements across Taj and Vivanta properties. Operating profit margin held steady at 33%, indicating pricing power and operational discipline. However, employee costs grew faster than revenue – a potential margin headwind going forward. Revenue has delivered approximately 25% 5-year CAGR, while PAT CAGR stands at approximately 45%, demonstrating strong operating leverage.
Earnings Quality Check
PAT of ₹2,247 Crore is supported by operating cash flow of ₹2,471 Crore – a healthy OCF-to-PAT ratio of 1.10x, indicating reported profits are converting to actual cash. This is a critical quality indicator: companies where PAT exceeds OCF may be recognising revenue aggressively. IHCL passes this test. EPS of ₹14.64 provides 4.50x earnings coverage for the ₹3.25 dividend, meaning the company earns ₹4.50 for every ₹1 it pays out.
Indian Hotels Cash Flow Analysis – Following the Money
Reported profits are accounting opinions. Cash is fact. IHCL’s cash flow analysis reveals a company that genuinely generates the cash its income statement claims.
| Operating Cash Flow (Consolidated) | ₹2,471.41 Cr |
| Capex (Approx.) | ₹1,027 Cr |
| Free Cash Flow | ₹1,444 Cr |
| Dividend Outflow | ₹462.61 Cr |
| OCF Coverage of Dividend | 5.34x |
| FCF Coverage of Dividend | 3.12x |
| Dividend as % of OCF | 18.7% |
Key Insight: IHCL’s dividend is funded entirely from current-year free cash flow. The company is not borrowing to pay dividends or depleting cash reserves. After paying ₹462.61 Crore in dividends, IHCL still has approximately ₹981 Crore of excess FCF for reinvestment, debt reduction, or cash building. Standalone OCF of ₹1,714 Crore also comfortably covers the outflow.
Indian Hotels Balance Sheet Strength – Can IHCL Afford This Dividend?
Leverage Position
| Total Borrowings | ₹2,837 Cr |
| Reserves & Surplus | ₹12,910 Cr |
| Debt-to-Equity Ratio | 0.22x |
| Cash & Investments (Approx.) | ₹1,200 Cr |
Assessment
IHCL’s balance sheet is conservatively managed. Reserves of ₹12,910 Crore are 4.5x total borrowings of ₹2,837 Crore. The debt-to-equity ratio of 0.22x is low for a capital-intensive hospitality business. Cash and investments of approximately ₹1,200 Crore provide 2.59x coverage of the annual dividend outflow. The company is not stretching its balance sheet to fund dividends. Borrowings have remained stable while reserves have grown – indicating retained earnings are accumulating faster than debt.
Indian Hotels Dividend Sustainability Analysis – 4-Point Scorecard
Earnings Coverage: 4.50x
Threshold: >1.5x — IHCL earns ₹4.50 for every ₹1 paid as dividend
OCF Coverage: 5.34x
Threshold: >1.5x — Dividend consumes only 18.7% of operating cash flow
FCF Coverage: 3.12x
Threshold: >1.0x — Even after capex, FCF fully funds the dividend 3x over
Payout Ratio: 22.2%
Threshold: <60% — Conservative payout leaves room for future increases
Verdict: SUSTAINABLE (4/4 Tests Passed)
IHCL’s dividend is well-covered by earnings, operating cash flow, and free cash flow with a conservative payout ratio.
Indian Hotels Peer Comparison – Hospitality Sector Dividends
| Company | Yield % | Payout % | ROE % | ROCE % |
|---|---|---|---|---|
| Indian Hotels (IHCL) | 0.44% | 22.2% | 14.2% | 17.1% |
| EIH Ltd | 0.30% | ~20% | ~12% | ~15% |
| Lemon Tree Hotels | 0.15% | ~10% | ~8.5% | ~11% |
| Chalet Hotels | 0.20% | ~15% | ~10% | ~13% |
Analysis: IHCL leads the Indian hospitality sector on every key metric – highest dividend yield, highest payout ratio, best ROE, and best ROCE. This reflects Taj’s pricing power, scale advantages, and the Tata Group’s capital discipline. However, all hospitality sector yields remain well below traditional “income stock” levels (3–5%), meaning this sector is primarily a growth play rather than an income play. Peer figures are approximate and based on latest available data.
Indian Hotels Promoter Impact Analysis – Who Benefits Most?
Dividend Distribution by Shareholder Category
| Promoters (38.12%) | ₹176.35 Cr |
| DIIs (24.47%) | ₹113.20 Cr |
| FIIs (21.71%) | ₹100.43 Cr |
| Public (15.59%) | ₹72.12 Cr |
Interpretation
The Tata Group (promoter) receives the largest share – ₹176.35 Crore – proportional to their 38.12% holding. This is a straightforward proportional distribution, not a disproportionate benefit. With institutional investors (FII + DII) holding 46.18% collectively, the dividend structure aligns promoter and institutional interests. Public shareholders receive ₹72.12 Crore, or approximately ₹3.25 per share held, same as every other category – demonstrating equitable treatment.
Indian Hotels Dividend Taxation Analysis – What You Actually Take Home
Tax Rules for Indian Dividends
Since April 2020, dividends are taxable in the hands of the shareholder at their applicable income tax slab rate. Companies deduct TDS at 10% if total dividend from a single company exceeds ₹5,000 in a financial year. Non-resident shareholders face TDS at 20% (or lower under applicable DTAA). There is no separate Dividend Distribution Tax (DDT) payable by the company.
Worked Example: 1,000 Shares at 30% Slab
| Gross Dividend (1,000 × ₹3.25) | ₹3,250 |
| Tax Slab | 30% |
| Health & Education Cess | 4% |
| Effective Tax Rate | 31.20% |
| Tax Payable | ₹1,014 |
| Net Dividend | ₹2,236 |
| TDS Deducted at Source | ₹0 (below ₹5,000 threshold) |
| Post-Tax Effective Yield | 0.30% |
Note: At the 30% slab, the effective yield drops from 0.44% (pre-tax) to just 0.30% (post-tax). Lower tax-slab investors retain more.
Key Risks – Indian Hotels Dividend Investors Should Know
1. Cyclical Industry Exposure
Hospitality is inherently cyclical. Economic slowdowns, pandemics (as seen in FY20–21), or geopolitical events can sharply reduce occupancy and room rates, directly impacting earnings and dividend-paying capacity.
2. Rising Employee & Operating Costs
Employee costs and other operating expenses grew faster than revenue in FY26. If this trend continues, operating margins could compress from the current 33%, threatening profitability and dividend growth.
3. Aggressive Expansion Risk
IHCL’s target of 300+ hotels by FY28 requires significant capital allocation. Expansion into new geographies or segments could dilute returns if demand does not materialise as expected.
4. Valuation Premium Leaves No Margin for Error
At a CMP of ₹746.30 with a P/E of approximately 51x and dividend yield of just 0.44%, the stock is priced for perfection. Any earnings miss could trigger sharp corrections that dwarf multiple years of dividend income.
5. Competitive Intensity
New entrants and existing players (Lemon Tree, ITC Hotels post-demerger, international chains) are expanding aggressively in India’s premium hospitality segment, which could pressure room rates and market share over the medium term.
6. Regulatory & Tax Policy Changes
Changes in GST rates on hotel rooms, tourism policies, or dividend taxation rules could affect investor returns. The current 30% + cess effective tax on dividends already reduces yield to 0.30% for high-bracket investors.
What To Monitor – Indian Hotels Dividend Investors
1. Quarterly RevPAR Trends
Revenue Per Available Room is the hospitality industry’s core operating metric. Track IHCL’s RevPAR growth quarter-on-quarter to gauge pricing power and occupancy strength.
2. Operating Margin Trajectory
Watch whether the 33% OPM is maintained or eroded. Employee cost ratio and other expenses as a percentage of revenue are the key sub-metrics.
3. Free Cash Flow vs Capex
As IHCL accelerates hotel openings, capex will rise. Monitor whether FCF remains sufficient to cover dividends without resorting to debt funding. Current FCF coverage of 3.12x provides a healthy buffer.
4. Debt Levels
With borrowings at ₹2,837 Crore and a 0.22x D/E ratio, any significant increase in debt relative to equity or cash flow would be a warning signal for dividend sustainability.
5. Payout Ratio Consistency
IHCL has maintained a steady 20–23% payout ratio. A sudden spike above 40–50% without corresponding earnings growth would suggest management is overpaying to maintain the dividend trajectory.
6. New Hotel Pipeline Execution
Track the rate of new hotel openings versus the announced pipeline. Delays or cancellations could indicate demand softening or execution challenges.
Conclusion – Indian Hotels Dividend FY26 Assessment
Indian Hotels Company Limited’s ₹3.25 per share final dividend for FY26 represents a well-managed capital return backed by genuine earnings growth. The 44.4% YoY increase continues a four-year streak of rising payouts since the post-COVID resumption. All four sustainability tests pass comfortably – with 4.50x earnings coverage, 5.34x OCF coverage, 3.12x FCF coverage, and a conservative 22.2% payout ratio. However, investors should recognise the face-value reality: the 325% headline translates to just 0.44% current yield (0.30% post-tax at the 30% slab). IHCL is a dividend growth story, not a dividend income story. The real value lies in the 68.8% 4-year DPS CAGR and the potential for further increases as earnings scale – provided cyclical risks, cost pressures, and valuation premium risks are monitored carefully.
Frequently Asked Questions – Indian Hotels Dividend FY26
What dividend has Indian Hotels announced for FY26?
What is the current dividend yield of Indian Hotels?
What is the record date for Indian Hotels FY26 dividend?
What is the ex-dividend date for IHCL FY26 dividend?
When was the Indian Hotels FY26 dividend paid?
Who was eligible for the Indian Hotels FY26 dividend?
How is Indian Hotels dividend taxed in India?
Is the Indian Hotels dividend sustainable?
What is the dividend history of Indian Hotels over the last 10 years?
What should investors monitor after the Indian Hotels dividend?
How does Indian Hotels dividend compare with peers like EIH and Lemon Tree?
What is the face value of Indian Hotels shares?
How much dividend income will promoters receive from Indian Hotels FY26?
Disclaimer – Indian Hotels Dividend Analysis
ShareBazaar Online is not a SEBI-registered investment advisor, research analyst, or portfolio manager. This article is for informational and educational purposes only and does not constitute a recommendation to buy, sell, or hold any security. All data has been sourced from publicly available company filings, stock exchange disclosures, and third-party financial data providers. While every effort has been made to ensure accuracy, ShareBazaar Online does not guarantee the completeness or correctness of any information presented. Market prices, yields, and financial metrics are subject to change. Investors should consult a qualified financial advisor before making investment decisions. Past dividend payments are not indicative of future payouts. Tax implications may vary based on individual circumstances – consult a tax professional for personalised advice. ShareBazaar Online, its authors, and affiliates may or may not hold positions in the securities discussed. By reading this content, you agree that ShareBazaar Online bears no liability for any investment decisions made based on this analysis.