
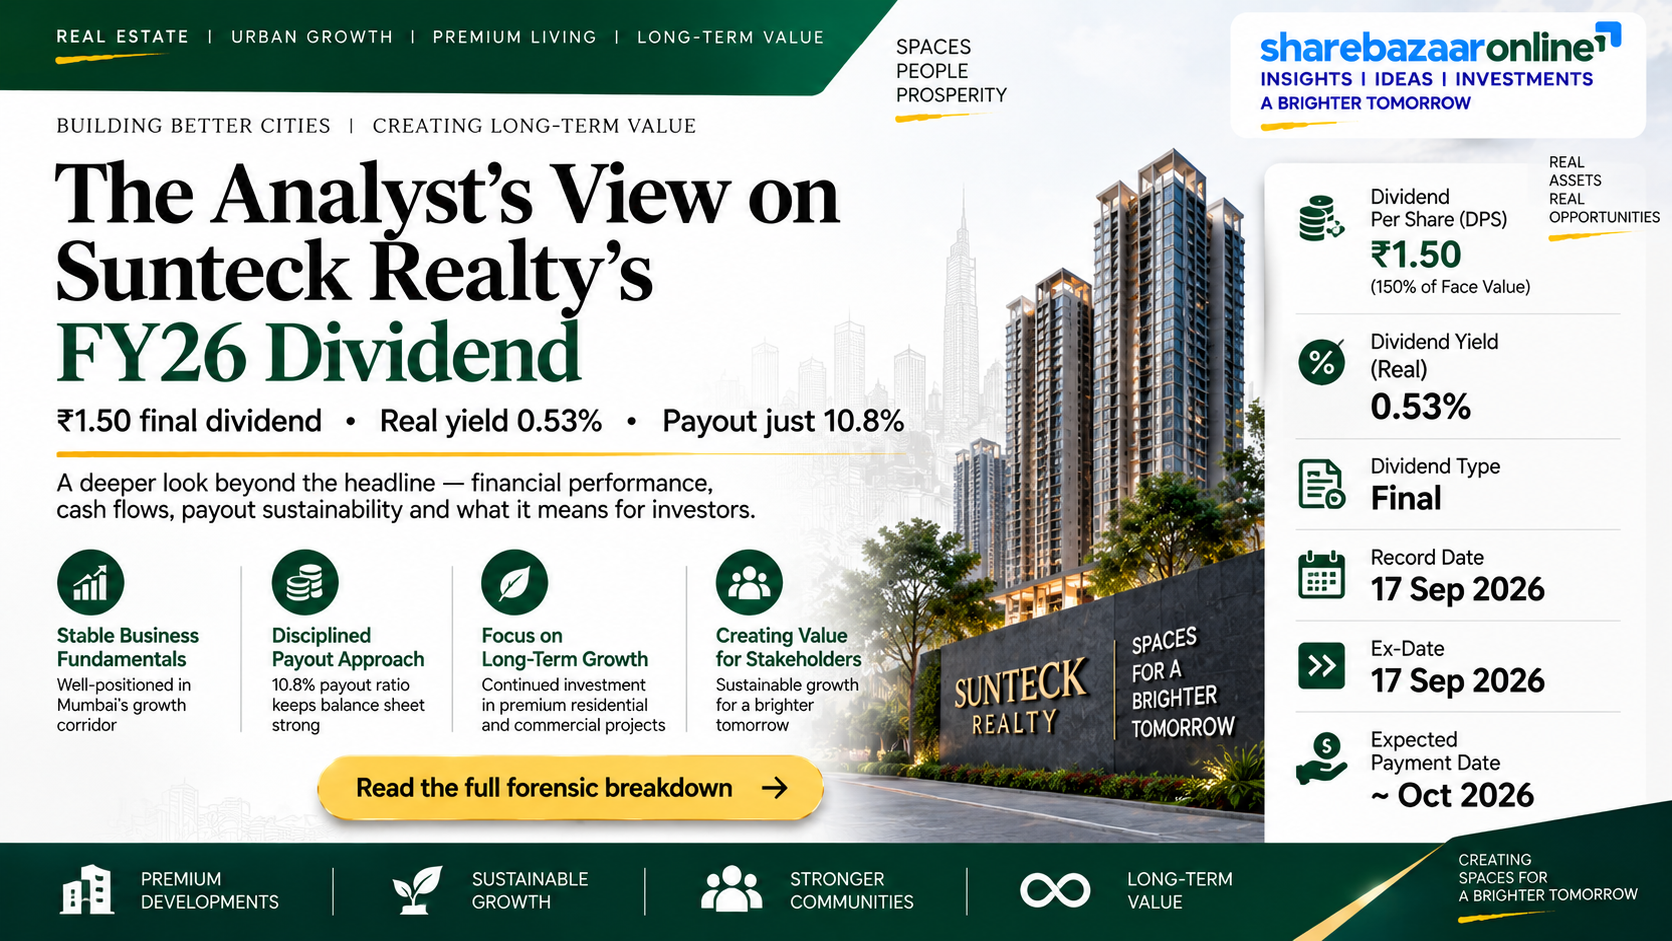
Dividend Snapshot – Sunteck Realty Limited
Sunteck Realty Limited (NSE: SUNTECK | BSE: 512179 | ISIN: INE805D01034) has recommended a final dividend of ₹1.50 per equity share for the financial year ended 31 March 2026 (FY26). The dividend is set at 150% of the face value of Re 1 and is subject to shareholder approval at the company’s 43rd Annual General Meeting. This is the Mumbai-based luxury real estate developer’s customary once-a-year payout, and the amount is unchanged from the ₹1.50 it has paid every year since FY2017.
Dividend Per Share
₹1.50
Final dividend • 150% of Re 1 face value
Real Market Yield (at CMP ₹282)
0.53%
Not the “150%” headline number
Record Date
17 Sep 2026
Eligibility cut-off for the payout
Total Dividend Outflow
₹22.03 cr
On ~14.68 crore shares
The one line that matters: the “150%” you may see in headlines is calculated on the Re 1 face value, not on the market price. At the current price of about ₹282, the actual cash return is roughly 0.53% — a reward-for-loyalty gesture, not an income stream.
Sunteck Realty Limited Dividend Announcement Summary
At its board meeting held on Tuesday, 21 April 2026 (6:00 p.m. to 6:45 p.m.), the Board of Directors of Sunteck Realty Limited approved the audited standalone and consolidated financial results for the year ended 31 March 2026 and recommended a final dividend of ₹1.50 per equity share (150% of face value).
The company’s statutory auditor, Walker Chandiok & Co LLP (a Grant Thornton member firm), issued an unmodified (unqualified) opinion on both the standalone and consolidated financial statements — a clean audit. The auditor did, however, flag two “Emphasis of Matter” items relating to the recoverability of ₹14.03 crore from a partnership firm and a lease-premium dispute at joint venture Piramal Sunteck Realty Private Limited; the auditor’s opinion was not modified on either.
Dividend type: Final dividend (annual). Sunteck does not pay interim or special dividends — it declares one final dividend each year after the audited results.
Approval status: The dividend is a Board recommendation and becomes payable only after shareholders approve it at the 43rd AGM scheduled for 24 September 2026.
Sunteck Realty Limited Dividend Record Date and Key Dates Timeline
| Event | Date | Note |
|---|---|---|
| Board Announcement | 21 April 2026 | Dividend recommended with FY26 results |
| Record Date | 17 September 2026 | Shareholders on register are eligible |
| Ex-Dividend Date | 17 September 2026 | Same as record date under T+1 settlement |
| 43rd AGM | 24 September 2026 | Shareholder approval of dividend |
| Payment Date | Within 30 days of AGM | Historically paid by end-October |
Under India’s T+1 settlement cycle, the ex-dividend date and the record date fall on the same day. To have been eligible for this dividend, an investor needed to hold Sunteck Realty shares in their demat account as of the record date, 17 September 2026. The exact payment date follows AGM approval; the Companies Act requires dividends to be paid within 30 days of declaration, and Sunteck has historically credited shareholders by late October.
Sunteck Realty Limited Dividend Yield Analysis
This is where most retail investors get misled. A “150% dividend” sounds enormous, but that percentage is applied to the face value of Re 1 — so 150% of Re 1 is simply ₹1.50 per share. The number that matters for your pocket is the dividend yield on the market price you actually pay.
Face-Value Headline
150%
Misleading — based on Re 1, not price
Real Yield at CMP ₹282
0.53%
₹1.50 ÷ ₹282 (17 Sep 2026)
Announcement-date yield: The dividend was announced on 21 April 2026 after market hours. The exact NSE closing price on that date should be confirmed against official exchange records before publication (flagged for desk verification — Not Independently Verified). For reference, the stock has traded in a 52-week band of roughly ₹271 to ₹473; at prices in that range the yield would sit between 0.32% and 0.55%, so the “low real yield” conclusion holds regardless of the exact April price.
Yield reality check: Sunteck’s yield is low not because the dividend was cut — it has been steady at ₹1.50 for years — but because the company is a growth-focused developer that deliberately retains cash for its land bank and project pipeline. A rising yield in future would more likely signal a falling share price than a bigger dividend.
Sunteck Realty Limited Dividend History and Growth Over the Years
| Financial Year | Dividend / Share | Type |
|---|---|---|
| FY26 (recommended) | ₹1.50 | Final |
| FY25 | ₹1.50 | Final |
| FY24 | ₹1.50 | Final |
| FY23 | ₹1.50 | Final |
| FY22 | ₹1.50 | Final |
| FY21 | ₹1.50 | Final |
| FY20 | ₹1.50 | Final |
| FY17–FY19 | ₹1.50 each | Final |
| FY16 & earlier | ₹1.00 | Final |
Per-share amounts reflect the current Re 1 face value. Sunteck’s shares were sub-divided over the years (face value moved from ₹2 to Re 1); older headline “percentages” should be read against the face value applicable at the time. Source: exchange filings and dividend-history aggregators; desk to confirm face-value-adjusted figures.
Classification: Consistent Payer. Sunteck Realty has paid a dividend every single year for over a decade, with no cuts and no suspensions, even through the weak-profit years of FY20–FY23.
But: no dividend growth. The payout has been frozen at ₹1.50 for roughly nine years while profits have swung widely. Investors get consistency, not a rising income stream.
Sunteck Realty Limited Financial Performance Analysis
| Metric (Consolidated) | FY26 | FY25 | Change |
|---|---|---|---|
| Revenue from Operations | ₹1,123.84 cr | ₹853.13 cr | +31.7% |
| Profit Before Tax | ₹268.01 cr | ₹183.46 cr | +46.1% |
| PAT (owners) | ₹204.37 cr | ₹150.32 cr | +36.0% |
| Basic EPS | ₹13.94 | ₹10.26 | +35.9% |
| Finance Costs | ₹67.32 cr | ₹40.87 cr | +64.7% |
On the face of it, FY26 was an excellent year for Sunteck Realty: revenue up 31.7%, profit up 36%, and EPS climbing to ₹13.94. The company reported strong presales momentum and margin expansion in its luxury segment.
The catch: finance costs jumped nearly 65% to ₹67.32 crore as borrowings were ramped up to fund land acquisition and projects. Reported profit grew, but so did the cost of the debt behind it — a theme that becomes critical in the cash-flow section below.
Consolidated vs Standalone: Almost all of Sunteck’s operating value sits in subsidiaries and joint ventures, so the consolidated numbers are the meaningful gauge. On a standalone basis the holding company reported a net loss in FY26 — meaning the dividend is being paid out of accumulated reserves, not out of current-year standalone profit. This is normal for a holding-company structure but important for judging dividend capacity.
Sunteck Realty Limited Cash Flow Analysis: Profit vs Cash
This is the single most important finding in this report. Reported profit is an accounting opinion; cash is fact. And in FY26, Sunteck Realty’s cash told a very different story from its profit.
Net Profit (consolidated)
+₹202.07 cr
Operating Cash Flow (FY26)
–₹432.50 cr
Free Cash Flow (approx)
–₹589 cr
Dividend Outflow
₹22.03 cr
Sunteck earned a book profit of ₹202 crore but operating cash flow was negative ₹432.50 crore. The gap is explained by a ₹167.85 crore rise in inventories (land and work-in-progress) and heavy deployment into projects — classic for a developer in an aggressive build-out phase, but it means the reported profit did not convert to cash this year.
How is the dividend funded? Not from current-year operating cash flow, and not from free cash flow — both were deeply negative. During FY26 the company raised cash through financing: roughly ₹538 crore of net financing inflows, including a ₹15 crore equity issue, ₹121 crore of share-warrant money, and a large increase in borrowings. In substance, the ₹22 crore dividend is supported by the company’s cash reserves and fresh capital raised, not by the cash its operations generated in FY26.
Sunteck Realty Limited Balance Sheet Strength
Total Borrowings (FY26)
₹774.17 cr
Up ~100% from ₹386.94 cr in FY25
Cash & Bank Balances
₹94.98 cr
₹54.42 cr cash + ₹40.57 cr other bank
Net Debt (approx)
₹679 cr
Debt-to-equity ~0.21x
Book Value / Share
~₹246
P/B ~1.15x at CMP ₹282
Sunteck Realty still runs a relatively conservative balance sheet for a developer — net debt-to-equity of about 0.21x is comfortable, and shareholder equity attributable to owners stands at roughly ₹3,611 crore against a large ₹7,896 crore inventory (land bank and projects under construction). The concern is direction, not level: borrowings doubled year-on-year even as the company maintained its dividend and stepped up land buying. The leverage is being taken on deliberately to fund growth, but it is a metric to watch closely alongside the dividend.
Sunteck Realty Limited Dividend Sustainability Analysis
| Test | Result | Reading |
|---|---|---|
| Earnings coverage | 9.29x | Strong (EPS ₹13.94 vs DPS ₹1.50) |
| Payout ratio | 10.8% | Very low — easily affordable |
| OCF coverage | Negative | OCF –₹432 cr in FY26 |
| FCF coverage | Negative | FCF ~–₹589 cr in FY26 |
| Cash coverage | 4.31x | ₹94.98 cr cash vs ₹22 cr outflow |
Verdict: Moderately Sustainable. The dividend is tiny relative to profit (only 10.8% of earnings) and comfortably covered by the cash on the balance sheet, so there is little near-term risk of a cut. The company has also paid without interruption for over a decade.
The qualifier: the dividend is not currently funded by operating or free cash flow, both of which were negative in FY26, and the holding company posted a standalone loss. As long as Sunteck keeps reinvesting aggressively and funding it with debt and equity raises, the ₹1.50 payout is more a signalling gesture from reserves than a distribution of surplus cash. Sustainable in size, dependent on continued balance-sheet and capital-market support in substance.
Sunteck Realty Limited Peer Comparison
| Company | Dividend Yield | Dividend Character |
|---|---|---|
| Sunteck Realty | ~0.53% | Steady ₹1.50/yr, low payout |
| Oberoi Realty | ~0.2–0.3% | Modest, growth-focused |
| DLF | ~0.5–0.6% | Regular payer, larger scale |
| Macrotech (Lodha) | ~0.2% | Small dividend, reinvests |
| Godrej Properties | ~0% (nil) | Typically retains all earnings |
Peer yields are indicative and move with share prices; confirm live figures before publication. Indian residential developers are structurally low-yield.
The peer takeaway: Indian real-estate developers are not dividend plays. They reinvest cash into land and construction, so yields across the sector sit far below the ~3% you might see in FMCG or utilities. Sunteck’s ~0.53% is actually middle-of-the-pack to slightly above for a residential developer — but the entire peer set confirms that anyone buying these stocks for income is looking in the wrong place. The investment case here is presales growth and NAV, not the dividend cheque.
Sunteck Realty Limited Promoter Impact Analysis
Promoter Holding
63.14%
Promoter dividend income: ~₹13.91 cr
Public + Institutions
36.86%
Their share of dividend: ~₹8.12 cr
Of the ₹22.03 crore total dividend, the promoter group (63.14%) receives about ₹13.91 crore. Foreign institutional investors (18.12%) collect around ₹3.99 crore, domestic institutions (5.30%) about ₹1.17 crore, and the public (13.42%) roughly ₹2.96 crore.
Governance note: promoter holding has drifted down over three years (from ~67% to 63.14%), while public and FII holding has risen. The dividend is proportional to shareholding, so there is no preferential treatment — but with a low payout ratio, promoters clearly favour reinvesting for capital appreciation over pulling cash out through dividends.
Sunteck Realty Limited Dividend Taxation Analysis
Since April 2020, dividends in India are taxable in the hands of the shareholder at their applicable income-tax slab rate. The company does not pay Dividend Distribution Tax anymore; instead:
- Dividend is added to your total income and taxed at your slab rate (5%, 20%, 30%, etc.).
- TDS of 10% is deducted by the company if your total dividend from that company in a financial year exceeds ₹5,000 (20% if PAN is not provided).
- If your income is below the taxable limit, you can submit Form 15G/15H to avoid TDS.
Worked Example — investor holding 1,000 Sunteck Realty shares (30% slab)
| Gross dividend (1,000 × ₹1.50) | ₹1,500 |
| TDS @10% (only if > ₹5,000/yr) | ₹0 (below threshold) |
| Tax @30% slab | ₹450 |
| Net dividend in hand | ₹1,050 |
| Effective post-tax yield (at CMP ₹282) | ~0.37% |
Illustrative only; your actual tax depends on your total income and slab. Consult a tax adviser.
Key Risks for Sunteck Realty Limited Investors
- Negative operating cash flow: FY26 OCF was –₹432.50 crore. If presales collections slow, the gap between book profit and cash could widen further.
- Rising leverage: total borrowings doubled to ₹774 crore and finance costs rose ~65%. Higher interest rates or slower project monetisation would pressure returns.
- Standalone loss at holding-company level: the dividend leans on reserves and consolidated value, not standalone current-year profit.
- Concentration in MMR luxury: Sunteck is heavily exposed to the Mumbai Metropolitan Region premium/luxury segment; a slowdown there hits both sales and NAV.
- Auditor Emphasis of Matter items: recoverability of ₹14.03 crore from a partnership firm and a CIDCO lease-premium dispute at JV PSRPL remain open.
- Negligible income return: at ~0.53% yield, this is not an income stock; the thesis depends entirely on capital appreciation.
What to Monitor in Sunteck Realty Limited
- Operating cash flow trend: watch whether OCF turns positive as projects are delivered and collections come in — the key test of dividend quality.
- Presales and collections growth: management has guided to 25–30% presales growth in FY27; track quarterly delivery against that.
- Debt trajectory: monitor whether borrowings stabilise or keep climbing, and the direction of finance costs.
- Dividend per share: any move above the long-frozen ₹1.50 would signal genuine surplus-cash generation.
- New project launches and GDV additions: the FY26 pipeline additions (₹5,000 crore GDV) and the Dubai project are the growth engines to validate.
- Promoter holding: continued decline versus stabilisation is worth tracking for governance signals.
Should You Consider Sunteck Realty Limited for Dividend Income? — Conclusion
Sunteck Realty’s FY26 final dividend of ₹1.50 per share is best understood as a consistency signal rather than an income opportunity. The “150%” headline is a face-value artefact; the real yield is about 0.53%. The payout is tiny (10.8% of profit), amply covered by earnings and cash reserves, and has held steady for nearly a decade without a single cut.
The forensic picture is more nuanced than the profit headline. Reported profit rose 36%, but operating and free cash flow were both sharply negative, borrowings doubled, and the standalone holding company booked a loss — so this dividend is funded from reserves and fresh capital, not FY26 operating cash. None of that makes the dividend fragile in the short term, but it does mean Sunteck is unambiguously a growth-and-reinvestment story, not a dividend story.
For investors, the honest framing is: the positives are a clean audit, strong presales momentum, a large land bank and an uninterrupted payout record; the negatives are negative cash flows, rising debt and a negligible yield. We present the evidence — the decision is yours.
Frequently Asked Questions About Sunteck Realty Limited Dividend
What dividend has Sunteck Realty announced for FY26?
What is the real dividend yield on Sunteck Realty?
What is the record date for the Sunteck Realty dividend?
What is the ex-dividend date for Sunteck Realty?
When will Sunteck Realty pay the dividend?
Who is eligible for the Sunteck Realty dividend?
How is the Sunteck Realty dividend taxed?
Is the Sunteck Realty dividend sustainable?
What is Sunteck Realty’s dividend history?
Why is Sunteck’s operating cash flow negative if profit rose?
Is Sunteck Realty a good dividend income stock?
How much dividend does the promoter group receive?
What should investors monitor going forward?
Disclaimer — Sunteck Realty Limited Dividend Analysis
This article is for informational and educational purposes only and does not constitute investment, financial, legal or tax advice. ShareBazaar Online is not a SEBI-registered investment adviser, and nothing here is a recommendation to buy, sell or hold any security. Financial figures are drawn from Sunteck Realty Limited’s audited FY26 results, exchange filings and third-party data aggregators, and may contain errors or be superseded by later disclosures; the announcement-date share price and certain peer figures are flagged for independent verification. Dividend payment remains subject to shareholder approval at the AGM. Please verify all data from official sources and consult a qualified financial adviser before making any investment decision. Investments in securities are subject to market risks.