
Dividend Snapshot
Mazagon Dock Shipbuilders Limited (NSE: MAZDOCK | BSE: 543237), India's flagship defence shipyard, declared a final dividend of ₹4.62 per equity share for the financial year ended 31 March 2026 (FY26). On the ₹5 face value, that headline reads as a striking 92.4% — but on the market price the real yield is a fraction of a percent. This is the gap every retail investor should understand before the number impresses them.
CMP reference: ₹2,236 (NSE close, 15 Sep 2026). Real-yield maths is explained in the Yield Analysis section below.
Dividend Announcement Summary
At its board meeting held on 30 April 2026 (1530–1830 hrs IST), the Board of Directors of Mazagon Dock Shipbuilders recommended a final dividend of ₹4.62 per equity share of ₹5 each for FY26, alongside its Q4 and full-year results. The recommendation was subject to shareholder approval at the Annual General Meeting.
Shareholders approved the payout at the company's 93rd AGM held on 27 August 2026 (via video conferencing). The company had fixed 20 August 2026 as the record date, and the dividend was scheduled to be paid on or before 26 September 2026, subject to Tax Deducted at Source (TDS).
This final dividend is the third and closing tranche of the FY26 payout. The company had already paid a first interim dividend of ₹6.00 and a second interim of ₹7.50 earlier in the year, taking the full-year total to ₹18.12 per share.
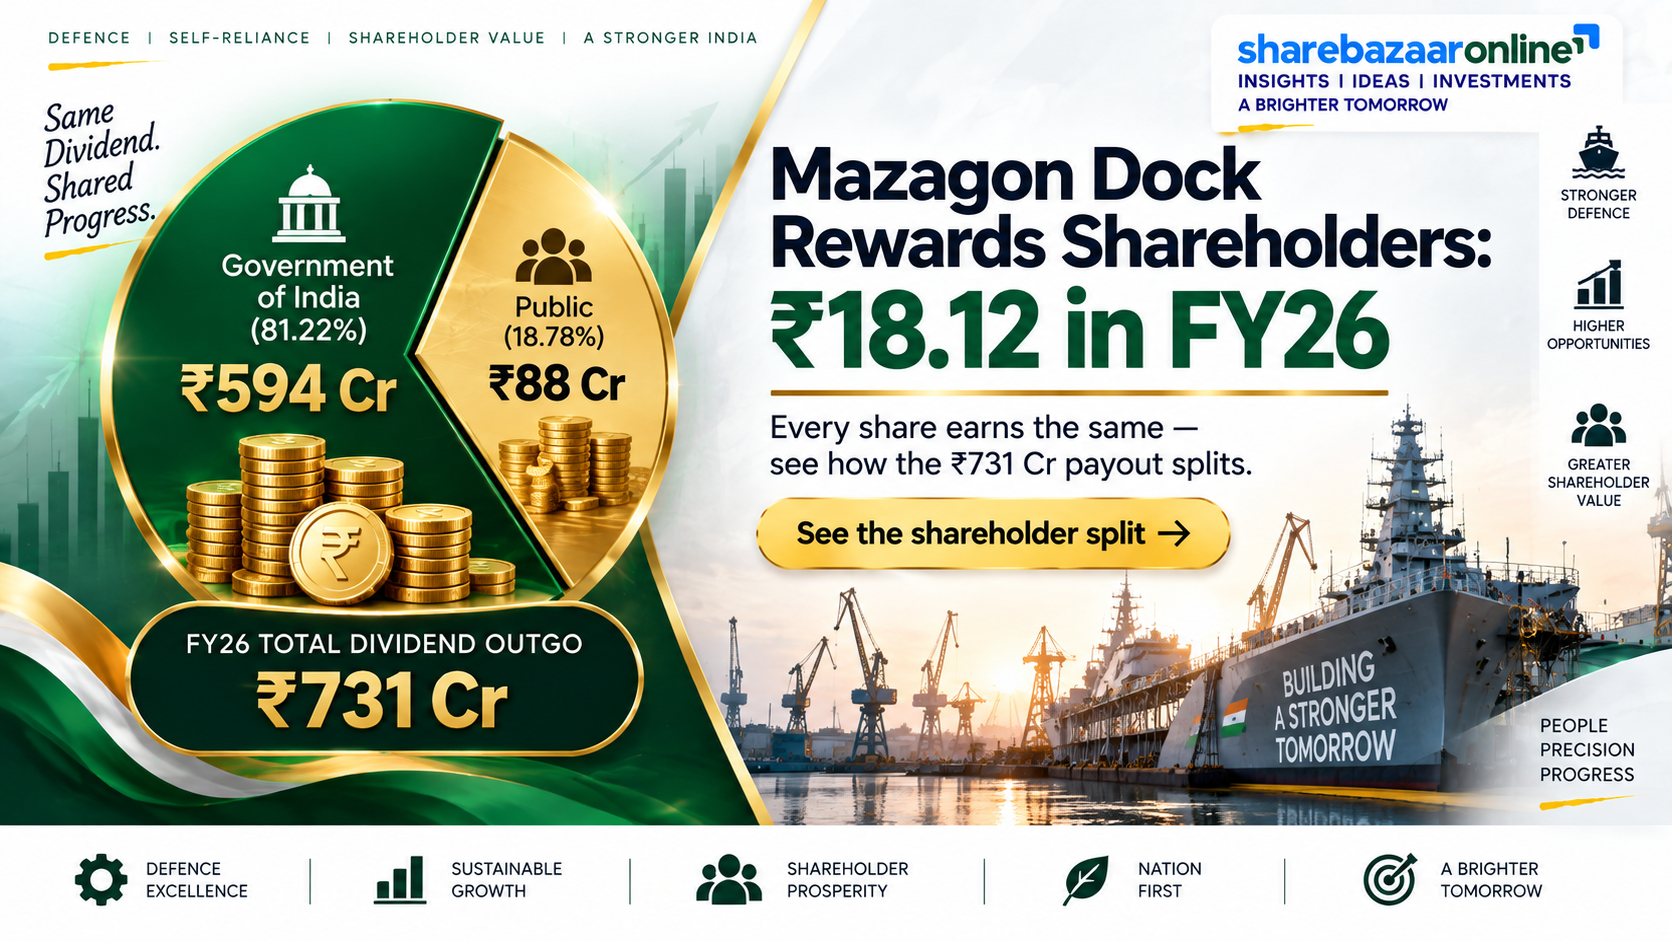
Why it matters: Mazagon Dock is a Government of India undertaking under the Ministry of Defence. As the majority owner (81.22%), the government is the single largest beneficiary of this payout — a recurring feature of dividend-paying defence PSUs that we quantify later in this report.
Key Dates Timeline
Under India's T+1 settlement cycle, the ex-date and record date now fall on the same day. Investors who held shares as of the record date of 20 August 2026 were eligible for this final dividend; anyone buying on or after that date was not.
Dividend Yield Analysis
The face-value illusion. The "92.4%" figure is calculated on the ₹5 face value, not on the price you actually pay. It tells you nothing about your income return. Here is the honest maths:
Yield reality check. Even counting the entire year's ₹18.12, MAZDOCK yields only 0.81% — well below a fixed deposit or government bond. That is not because the dividend is small in rupee terms (it has grown strongly), but because the share has re-rated so heavily. MAZDOCK is a growth-and-capital-appreciation stock that happens to pay a modest, rising dividend — not an income stock. Buying it for yield would be a category error.
Dividend History Analysis
| Financial Year | EPS (₹) | Payout Ratio | Total DPS (₹) |
|---|---|---|---|
| FY22 | 15.14 | 29% | ~4.39 |
| FY23 | 27.74 | 29% | ~8.04 |
| FY24 | 48.02 | 29% | ~13.93 |
| FY25 | 59.83 | 29% | ~17.35 |
| FY26 | 64.04 | 28% | 18.12 |
DPS for FY22–FY25 is derived from the company's disclosed dividend payout ratio and EPS (consolidated). FY26 total of ₹18.12 is the confirmed sum of ₹6.00 + ₹7.50 (interims) + ₹4.62 (final). All per-share figures on ₹5 face value.
Classification: Consistent & Growing Payer. Since listing in October 2020, MAZDOCK has paid a dividend every year, with the per-share payout rising from a low single-digit figure to ₹18.12 in FY26 — roughly a 4x increase over four years. Crucially, this growth was driven by earnings growth, not payout-ratio expansion: the payout ratio has held steady in a disciplined 28–29% band throughout. There have been no dividend cuts, suspensions, or one-off special dividends in the listed history — a clean, policy-driven record.
Financial Performance Analysis
Operating leverage has been the real story. Revenue grew from ₹5,733 Cr (FY22) to ₹13,006 Cr (FY26), while net profit surged from ₹611 Cr to ₹2,578 Cr over the same period. As shipbuilding and submarine projects moved into higher-margin delivery phases, operating margins expanded from single digits to the mid-teens. This is genuine operating leverage, not financial engineering.
One honest caveat — the "other income" cushion. Of FY26's ₹3,237 Cr profit before tax, roughly ₹1,139 Cr (about 35%) came from "other income" — largely treasury/interest earned on the company's very large cash pile, not from building ships. Investors should mentally separate the operating engine from the treasury engine: a chunk of MAZDOCK's reported profit is a function of parked customer advances, and can move with interest rates and cash levels.
Cash Flow Analysis
This is the most important section of the report. Reported profit is an accounting opinion; cash is fact. And in FY26, the two told very different stories:
What is going on — and why it is not distress. MAZDOCK runs a negative-working-capital model: the Indian Navy pays large advances up front, which the company parks in cash and then consumes as vessels are built and delivered. In FY25, advances were flowing in and operating cash flow was a healthy +₹2,102 Cr. In FY26, as several projects moved into their final delivery phase, that advance pool unwound, producing a large negative operating cash flow of –₹2,654 Cr. This is the natural rhythm of milestone-funded shipbuilding, not a sign of the business breaking.
The honest implication for the dividend: the FY26 payout was not funded from FY26's own cash generation — it was paid out of the enormous cash reserves accumulated from prior-year advances. Earnings coverage is comfortable; current-year cash coverage was negative. Both facts are true at once, and a serious analysis states both.
Balance Sheet Strength
Fortress liquidity underpins the dividend. MAZDOCK is essentially debt-free and sits on a very large cash-and-investments position built from customer advances. Against this, the entire FY26 dividend of ~₹731 Cr is a rounding error — cash coverage of the payout is many times over. This is precisely why a single year of negative operating cash flow does not threaten the dividend.
Two items to keep on the radar: contingent liabilities of ₹28,181 Cr (large, though typical for a defence contractor with performance guarantees and disputed claims), and debtor days rising from 34 to 73, worth monitoring as commercial-shipbuilding and overseas exposure grows.
Dividend Sustainability Analysis
We score sustainability across four independent tests:
Verdict: Sustainable. Three of four tests pass comfortably — low payout ratio, high earnings cover, and a fortress cash balance. The single amber flag is FY26's negative free cash flow, which reflects the lumpy, advance-driven cash cycle of shipbuilding rather than an inability to fund the dividend. As long as the order book keeps converting into fresh advances and the payout ratio stays disciplined near 28–29%, the dividend is well supported. The risk to watch is not affordability but earnings cyclicality: because the DPS is set as a fixed share of profit, a weak profit year would mechanically shrink the rupee dividend.
Peer Comparison
| Company | FY26 Total DPS | Div Yield | ROE | Govt Holding |
|---|---|---|---|---|
| Mazagon Dock | ₹18.12 | ~0.7% | 29–37% | 81.22% |
| GRSE | ₹19.60 | ~0.5% | ~41% | ~75% |
| Cochin Shipyard | ₹9.00 | ~0.7% | ~12% | 67.92% |
| Bharat Electronics | ₹2.50 | ~0.6% | ~28% | ~51% |
Peer figures compiled from exchange filings and market data (FY26). Yields on respective mid-2026 prices. BEL DPS on ₹1 face value; others on ₹5 (BEL). Figures approximate and for context only.
Read-across. Across defence PSUs, dividend yields cluster in a 0.5–0.7% band — the whole sector has re-rated, so none is an income play. On rupee payout and return quality, MAZDOCK and GRSE lead; GRSE posts the highest ROE (~41%) and the largest total DPS, while Cochin Shipyard's ROE (~12%) is materially lower. MAZDOCK's edge is scale (the largest order book and market cap in the pack) and a debt-free, cash-rich balance sheet.
Promoter Impact Analysis
Who benefits, and how it is shared. Because the Government of India owns 81.22%, roughly ₹594 Cr of the full-year FY26 dividend flows to the exchequer, versus ~₹88 Cr to the entire public float. Importantly, the dividend is uniform per share — every shareholder, promoter or retail, receives the same ₹4.62 per share. There is no preferential treatment; the government simply receives more because it owns more.
A structural nuance: the government's dividend-hungry ownership generally supports a steady, policy-driven payout from defence PSUs — a positive for minority holders seeking predictability. The flip side is that capital-allocation choices (dividend vs buyback vs reinvestment) are influenced by the majority owner's fiscal needs. Note the promoter stake fell from 84.83% to 81.22% during FY26 following a government offer-for-sale, marginally widening the public float.
Taxation Analysis
How dividends are taxed in India (post-2020 rules). Since the abolition of the Dividend Distribution Tax, dividends are taxed in the hands of the investor at their applicable income-tax slab rate. The company deducts TDS at 10% under Section 194 if a resident shareholder's total dividend from that company in a financial year exceeds ₹5,000 (20% if PAN is not furnished). The TDS is not an extra cost — it is adjustable against your final tax liability.
Worked example — investor holding 1,000 shares, 30% tax slab:
On the final dividend (₹4.62)
On FY26 total (₹18.12)
Retail nuance worth knowing: because the standalone final dividend of ₹4,620 is below the ₹5,000 TDS threshold, no tax is deducted at source on it — but the income is still fully taxable and must be declared. Across the full year, MAZDOCK's total per this holding (₹18,120) crosses the threshold, so TDS applies on the aggregate. Investors in lower slabs pay proportionately less; those in the 0% bracket can reclaim TDS via their return.
Key Risks
1. Customer concentration. The Indian Navy and Ministry of Defence are the overwhelming source of revenue. Order timing, budget cycles and project delays can swing quarterly numbers sharply — and because the dividend is a fixed share of profit, they swing the payout too.
2. Lumpy, negative cash-flow cycle. As FY26 showed, operating cash flow can turn deeply negative (–₹2,654 Cr) when advance pools unwind during delivery phases. This is structural, not one-off, and can recur.
3. Earnings cyclicality & margin volatility. Onerous-contract provisions, project mix and cost inflation have caused visible margin swings (Q4 FY25 OPM fell to ~4%). A weak profit year mechanically shrinks the rupee dividend.
4. Reliance on treasury income. About 35% of PBT came from other income. Falling interest rates or a shrinking cash pile (as advances are consumed) would pressure this cushion.
5. Valuation & policy risk. The stock trades at over 9x book value with contingent liabilities of ₹28,181 Cr; as a government-controlled entity, further offers-for-sale, pricing controls, or shifts in defence procurement policy are outside minority shareholders' control.
What To Monitor
1. Fresh order inflows & advances. New submarine (P-75I/P-76) and warship contracts refill the advance pool that funds both operations and dividends — watch order-book additions and the pace of advance receipts.
2. Operating cash flow trajectory. Whether OCF returns to positive in FY27 as new advances arrive is the single most important cash-quality signal for the dividend.
3. Payout-ratio discipline. The 28–29% payout band has been the anchor of the dividend's growth. Any deviation — up or down — changes the income profile.
4. Margin & provisioning trends. Track operating margins and any onerous-contract provisions, especially at overseas units like Colombo Dockyard, which management flagged as under margin pressure.
5. Debtor days & commercial-shipbuilding push. As MDL re-enters commercial shipbuilding, monitor whether receivables (up from 34 to 73 days) and working capital stay under control.
Conclusion
Mazagon Dock's ₹4.62 final dividend caps a FY26 total of ₹18.12 per share — the culmination of a multi-year run of strong, earnings-led dividend growth from a debt-free, cash-rich defence PSU. The payout is conservative (28% of profit), well covered by earnings, and backed by a fortress balance sheet.
The two facts to hold together: First, the "92.4%" headline is a face-value artefact — the real income yield is just 0.21% on the final dividend and 0.81% for the full year. MAZDOCK is a capital-appreciation stock, not an income stock. Second, FY26's dividend was funded from accumulated cash, not from current-year cash flow, which was negative (–₹2,654 Cr) as advance pools unwound — a structural feature of shipbuilding, not a red flag, but one competitors' coverage omits.
Positives: consistent growing payout, 33.5% five-year profit CAGR, debt-free, high ROCE/ROE, large order book. Negatives / watch-items: low absolute yield, negative FY26 free cash flow, ~35% reliance on treasury income, rich valuation, and earnings cyclicality that flows straight through to the rupee dividend. We present the evidence; the decision is yours.
Frequently Asked Questions
What dividend has Mazagon Dock announced for FY26?
What is the Mazagon Dock dividend yield?
What was the record date for the Mazagon Dock final dividend?
What was the ex-dividend date?
When was the dividend paid?
Who was eligible for the dividend?
How is the Mazagon Dock dividend taxed?
Is the Mazagon Dock dividend sustainable?
What is Mazagon Dock's dividend history?
Why was Mazagon Dock's operating cash flow negative in FY26?
How much dividend does the Government of India receive?
How does Mazagon Dock's dividend compare with peers?
What should investors monitor going forward?
Should I buy Mazagon Dock for its dividend?
Disclaimer
This article is for informational and educational purposes only and does not constitute investment advice, a recommendation, or an offer to buy or sell any security. ShareBazaar Online is not a SEBI-registered investment adviser. Mazagon Dock Shipbuilders is a Government of India undertaking; all financial figures are drawn from company filings, exchange disclosures and third-party data sources (including Screener.in and public market data) believed to be reliable but not independently audited by us, and are consolidated unless stated otherwise. Market prices, yields and dates are as referenced and may change. Dividend taxation depends on individual circumstances. Please conduct your own research and consult a SEBI-registered financial adviser before making any investment decision. Investments in securities are subject to market risks.