
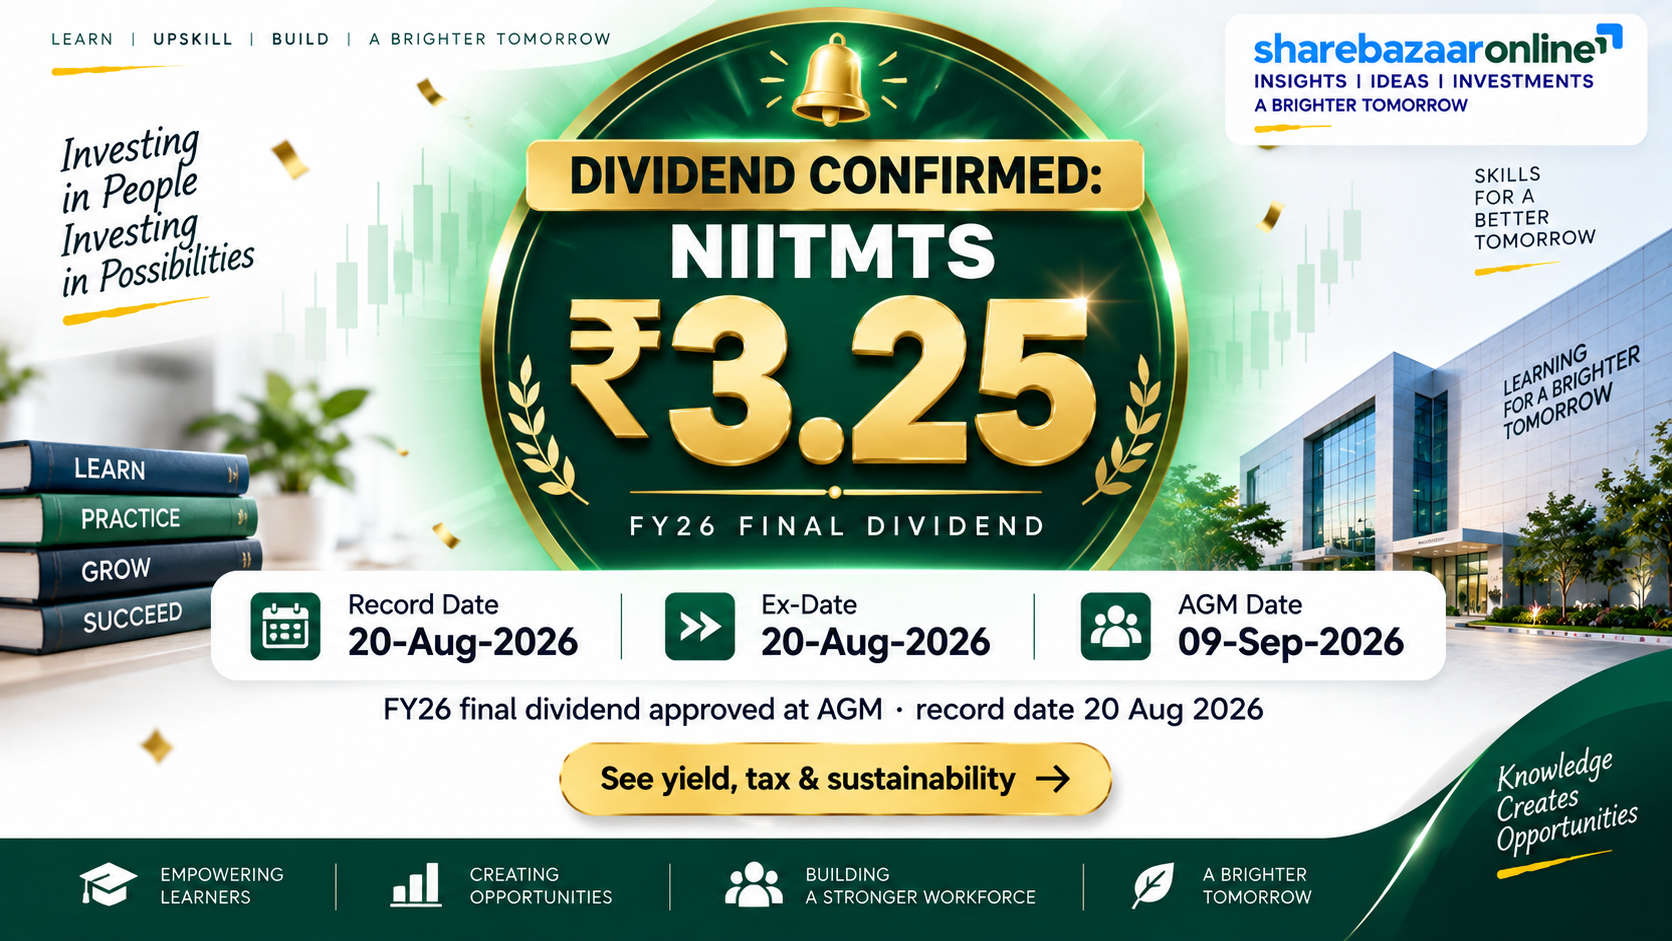
Dividend Snapshot
NIIT Learning Systems Limited (NSE: NIITMTS | BSE: 543952) declared a final dividend of ₹3.25 per equity share for FY 2025-26 on a face value of ₹2. The headline "162.5%" you may see quoted is calculated on that ₹2 face value — it is not your return. At the current market price of about ₹227, the real cash yield works out to roughly 1.43%. This is the single most important number to understand before anything else.
Dividend Details
Dividend Per Share: ₹3.25
Dividend Type: Final Dividend
Dividend on Face Value: 162.5%
Face Value: ₹2
Financial Year: FY 2025-26
Yield & Coverage
Real Yield (at ₹227): ~1.43%
Dividend Payout Ratio: ~18%
Earnings Coverage: 5.57x
Free Cash Flow Coverage: 5.45x
Total Payout: ~₹44.7 Crore
The one-line verdict: A comfortably-covered, cash-funded dividend from a net-cash company — but the payout ratio has settled near half of its FY24 level, and the reported profit growth this year is flattered by one-time gains that mask a small decline in core operating profit.
Dividend Announcement Summary
On 12 May 2026, the Board of Directors of NIIT Learning Systems, at a meeting held in Gurugram, approved the audited consolidated and standalone results for the year ended 31 March 2026 and recommended a final dividend of ₹3.25 per share. The statutory auditors, S.R. Batliboi & Associates LLP, issued an unmodified (clean) audit opinion on the results.
The dividend was proposed subject to shareholder approval and was approved by members at the 24th Annual General Meeting held on 9 September 2026. The company fixed 20 August 2026 as the record date. Being a single final dividend for the year, it is paid once (there was no interim dividend in FY26).
Company Identifiers
NSE Symbol: NIITMTS | BSE Code: 543952 | ISIN: INE342G01023 | CIN: L72200HR2001PLC099478 | Sector: Managed Training / Education Services | Registered Office: Gurugram, Haryana
Key Dates Timeline
Board Announcement
12 May 2026
Board recommended the final dividend along with FY26 audited results.
Record Date
20 August 2026 (Thursday)
Shareholders on the register as beneficial owners at close of business were entitled to the dividend.
Ex-Dividend Date
20 August 2026
Under India's T+1 settlement cycle, the ex-date and record date fall on the same day, consistent with the company's own past dividend actions.
AGM Approval
9 September 2026
Dividend formally approved by shareholders at the 24th AGM.
Payment Date
Not separately disclosed by the company — payable within 30 days of AGM approval (i.e. by early October 2026). In prior years the company paid on 24 October.
A Note on Timing
Because the record date of 20 August 2026 has already passed, eligibility for this payout is now settled. This article is a post-event analysis, not a "how to qualify" guide.
Dividend Yield Analysis
This is where most first-time readers get tripped up. A dividend is quoted two very different ways:
The Headline (Face-Value) Number
₹3.25 ÷ ₹2 face value = 162.5%. This sounds enormous, but it is only a legal/accounting convention. Nobody buys the share at ₹2.
The Real (Market) Yield
₹3.25 ÷ ₹227 market price = ~1.43%. This is the actual cash return on money you would invest today. Screener.in independently lists the yield at 1.42%.
Yield at Announcement vs Now
Around the 12 May 2026 announcement the stock traded near ₹250 (the 20 May 2026 close was ₹233.85, per market data), implying an announcement-window yield of roughly 1.30%. The yield has edged up to ~1.43% mainly because the share price has drifted lower — the stock is down about 30% over the past year and sits near its 52-week low of ₹203 (52-week high: ₹444). A rising yield here is driven more by a falling price than by a bigger dividend — a distinction covered in the Yield Reality Check below.
Dividend History Analysis
NIIT Learning Systems began paying dividends only after its demerger and listing; there was no payout in FY22 or FY23. The record since then:
| Financial Year | Dividend Per Share | Ex / Record Date | Payout Ratio |
|---|---|---|---|
| FY26 | ₹3.25 (final) | 20 Aug 2026 | ~18% |
| FY25 | ₹3.00 (final) | 04 Sep 2025 | ~18% |
| FY24 | ₹5.25 total (₹2.50 + ₹2.75) | Nov 2023 & Sep 2024 | ~33% |
| FY22 & FY23 | Nil | — | 0% |
What the History Actually Tells You
The per-share dividend looks like it has grown steadily (₹3.00 → ₹3.25), but the payout ratio tells a different story. FY24 saw an elevated ~33% payout (two tranches totalling ₹5.25), after which the company reset its payout to a steadier ~18% of profits in both FY25 and FY26. So the modest ₹0.25 increase this year is really the company holding its payout ratio flat while profits grew. Classification: a short-but-consistent payer since FY24, with a deliberately conservative and stable payout policy. Note per-share figures before FY24 are not comparable due to the company's capital restructuring around its demerger.
Financial Performance Analysis
All figures below are consolidated (the group as a whole), which is the right lens for a company that earns most of its revenue overseas through subsidiaries in the US and Europe.
Headline Numbers (FY26)
Revenue from Operations: ₹1,951.98 Cr (up 18.1% YoY)
EBITDA: ₹395.7 Cr (margin ~20.3%)
Reported PAT: ₹247.72 Cr (up ~8.9%)
EPS (Basic): ₹18.09 | Diluted: ₹17.66
Operating Leverage Warning
Revenue grew 18% but core profit did not follow. Operating margin (OPM) slipped from 22% to 19%, and by Q1 FY27 it had fallen further to ~16%. Growth is being bought, not compounded.
The Non-Obvious Finding: Core Profit Actually Fell
Reported PAT rose to ₹247.72 Cr, which looks like healthy growth. But look one line up. Profit before exceptional items and tax fell to ₹303.96 Cr in FY26 from ₹317.47 Cr in FY25 — a decline of about 4.3%, even as revenue jumped 18%. The reported profit rose partly because FY26 carried a net one-time gain of ₹27.2 Cr in exceptional items (largely an earnout reversal on an earlier acquisition), whereas FY25 had a ₹11.1 Cr exceptional loss. Strip out the one-offs and the underlying operating engine went slightly backwards this year.
Why Margins Compressed
The pressure is visible in two cost lines. Professional & technical outsourcing expenses jumped 51.3% (₹330.1 Cr → ₹499.3 Cr) and employee costs rose 9.7% (₹795.7 Cr → ₹873.2 Cr). Much of this reflects the two big overseas acquisitions completed during the year (MST Group in Europe from July 2025 and SweetRush in the US from January 2026), which added revenue and headcount but diluted group margins during integration.
Cash Flow Analysis
Reported profit is an accounting opinion; cash is a fact. Here the news is reassuring — the company converts profit into cash well.
Operating Cash Flow vs Profit
Operating Cash Flow: ₹288.44 Cr
Reported PAT: ₹247.72 Cr
OCF is 116% of PAT — genuine cash is being generated, not just paper profit.
Free Cash Flow & Dividend Funding
Capex: ₹44.69 Cr | Free Cash Flow: ₹243.75 Cr.
The ₹44.7 Cr dividend is comfortably funded from current-year free cash flow, not from reserves or borrowings.
The Watch-Item: Receivables Are Stretching
One yellow flag sits inside the working capital. Trade receivables rose about 50% (₹251.5 Cr → ₹377.8 Cr) — almost three times the pace of revenue growth — and debtor days rose from 56 to 71. Some of this comes with the acquisitions, but if collections keep lagging billings, future operating cash flow can weaken even when profits look fine. For now, OCF stayed strong, so this is a "monitor," not a "warning."
Balance Sheet Strength
Liquidity
Cash & equivalents: ₹394.32 Cr
Investments (current + non-current): ₹531.35 Cr
Total liquid resources: ~₹926 Cr
That is 20.7x the annual dividend outflow.
Debt Position
Borrowings (ex-lease): ₹267.39 Cr
Net position: net cash of ~₹659 Cr
Book Value: ₹112/share | ROE: 15.5% | ROCE: 20.9%
The Debt Nuance
The company remains firmly net cash, so the dividend is not being funded by leverage. That said, gross borrowings tripled from ~₹103 Cr to ~₹318 Cr during the year (Screener figure, including lease-related items) to help fund the overseas acquisitions. It is worth watching whether this rises further. Separately, ROCE has trended down from 36% (FY23) to ~21% (FY26) as the capital base expanded through acquisitions — returns are still good, but no longer exceptional.
Dividend Sustainability Analysis
We run four independent tests. A dividend is only as safe as its weakest test.
1. Earnings Coverage
EPS ₹18.09 vs DPS ₹3.25 = 5.57x cover (payout ~18%). Very comfortable. Strong.
2. Operating Cash Flow Coverage
OCF ₹288.4 Cr vs outflow ₹44.7 Cr = 6.45x. Strong.
3. Free Cash Flow Coverage
FCF ₹243.8 Cr vs outflow ₹44.7 Cr = 5.45x. Paid from surplus cash. Strong.
4. Liquidity / Balance Sheet
~₹926 Cr liquid, net cash of ~₹659 Cr = 20.7x the dividend. Strong.
Verdict: Sustainable
On every one of the four tests, this dividend is well covered. The realistic risk is not that the dividend gets cut, but that dividend growth stalls if margin compression continues and acquisition integration keeps absorbing cash. The payout itself is safe; its future growth rate depends on core earnings recovering.
Peer Comparison
| Company | Latest DPS | Dividend Yield | ROE | P/E |
|---|---|---|---|---|
| NIIT Learning Systems | ₹3.25 | ~1.43% | 15.5% | ~13.6 |
| Aptech Ltd | ₹4.50 | ~5.0% | ~9-10% | ~21 |
| NIIT Ltd (sibling) | ₹1.00 | ~1.0% | Low | n/a |
| CL Educate | Nil | — | Negative | n/a |
Two things stand out. First, NIIT Learning is a lower-yield but higher-quality payer in its niche — it offers the best ROE of the group (15.5%) but only a ~1.4% yield, while Aptech offers a much fatter ~5% yield on a smaller, lower-return business. Second, the peer set is genuinely thin: most Indian listed education/training companies either do not pay dividends (CL Educate, Veranda) or are structurally different. NIIT Learning is best understood as a global managed-training/IT-services business rather than a domestic coaching company, so its low yield reflects a growth-and-services valuation, not a classic dividend stock. Peer figures are drawn from market data and should be treated as approximate.
Promoter Impact Analysis
Who Holds the Shares
Promoters: ~34.1% (among the lower promoter stakes in the market)
DIIs: ~24.5% (steadily rising)
FIIs: ~16.8% (declining; ~14.4% by Jun 2026)
Public: ~24.7%
Where the ₹44.7 Cr Goes
Promoters' share (~34.1%): ~₹15.24 Cr
Public + institutions (~65.9%): ~₹29.46 Cr
Nearly two-thirds of the payout flows to non-promoter shareholders.
Because the promoter stake is relatively low (~34%), this dividend is not a promoter-tilted payout — unlike many family-controlled Indian companies where 60-70% of the dividend cheque returns to the promoter group. The steady rise in domestic institutional (DII) ownership, alongside a falling FII stake, is a notable ownership shift worth tracking on its own.
Taxation Analysis
How Dividends Are Taxed in India
Since April 2020, dividends are taxed in the hands of the investor at their applicable income-tax slab rate — there is no separate dividend distribution tax and no exemption. The company also deducts TDS at 10% before paying, but only if your total dividend from that company in the financial year exceeds ₹10,000 (raised from the earlier ₹5,000 threshold). If your PAN is not updated, TDS is 20%. You can claim credit for any TDS when filing your return.
Worked Example
Suppose you own 1,000 shares and receive ₹3.25 each, and you are in the 30% tax slab:
Gross dividend: ₹3,250
TDS at 10%: ₹0 (dividend is below the ₹10,000 threshold)
Income tax at 30% slab: ₹975
Net dividend in hand: ₹2,275
Post-tax yield (on ~₹227 price): ~1.0%
The lesson: a headline "162.5% dividend" becomes a ~1.0% post-tax yield for a top-slab investor. For someone in a lower slab (say 5-10%), the net yield is naturally higher. Always evaluate a dividend on an after-tax, market-price basis.
Key Risks
1. Margin Compression
Operating margin fell from 22% to 19% (and ~16% by Q1 FY27). If outsourcing and integration costs stay elevated, core profit and future dividend growth are pressured.
2. Acquisition Integration
Two large overseas buys (MST Group, SweetRush) were completed in FY26, funded partly by fresh borrowings. Integration risk, goodwill (now ~₹843 Cr) and earnout adjustments could surprise either way.
3. Currency & Global Exposure
Most revenue is earned in the US and Europe, so results swing with USD/EUR movements and with corporate training budgets, which are discretionary and cyclical.
4. Receivables & Working Capital
Receivables grew ~50% and debtor days rose to 71. Sustained slippage in collections could erode the strong cash conversion that currently underpins the dividend.
5. One-Time Earnings Support
FY26 profit growth leaned on a ~₹27 Cr net exceptional gain. Such items do not repeat, so headline PAT growth may look weaker next year unless core margins recover.
6. AI Disruption to Training Demand
The managed-learning industry is itself being reshaped by AI. The company is repositioning toward AI-led offerings, but the transition adds both opportunity and execution risk.
What To Monitor
1. Operating Margin Trajectory
Watch whether OPM stabilises above the current ~16-19% band as acquisitions integrate. This is the single biggest driver of future dividend growth.
2. Core (Pre-Exceptional) PBT
Track profit before exceptional items, not just reported PAT, to see whether the underlying business is genuinely growing again.
3. Debtor Days & Cash Conversion
Keep an eye on whether debtor days ease back below 71 and whether OCF stays above reported PAT.
4. Payout Policy
Note whether the ~18% payout ratio holds, rises back toward FY24's 33%, or the company shifts toward buybacks with its large cash pile.
5. Borrowings & Net-Cash Position
Gross debt tripled this year. Watch whether the balance sheet stays net cash or leverage creeps up to fund more deals.
6. Ownership Shift
FIIs have been trimming while DIIs add. A continued institutional rotation can affect both liquidity and share-price behaviour.
Conclusion
NIIT Learning Systems' FY26 final dividend of ₹3.25 per share is a well-covered, cash-funded payout from a debt-light, net-cash company — it clears all four sustainability tests with room to spare. The dividend itself is not in question.
The Balanced Picture
On the positive side: 18% revenue growth, 20%+ EBITDA margins, strong cash conversion (OCF at 116% of PAT), a fortress liquidity position, and a conservative ~18% payout that leaves ample headroom.
On the cautious side: the "real" yield is only ~1.43% (not 162.5%), core pre-exceptional profit actually dipped 4.3% while revenue surged, margins are compressing, receivables are stretching, and this year's reported profit growth was helped by one-time gains. This is a growth-oriented global services business that happens to pay a modest, reliable dividend — not a high-yield income stock.
For income-focused readers, the takeaway is simple: a dependable but small dividend, safe today, with growth that hinges on a margin recovery. Weigh the positives against the risks and monitoring points above, and decide for yourself.
Frequently Asked Questions
What dividend has NIIT Learning Systems announced for FY26?
What is the actual dividend yield of NIITMTS?
What was the record date for the NIIT Learning Systems dividend?
What was the ex-dividend date?
When will the dividend be paid?
Who was eligible to receive the dividend?
How is this dividend taxed?
Is the NIIT Learning Systems dividend sustainable?
What is NIIT Learning Systems' dividend history?
Why did reported profit rise but core profit fall?
Is NIITMTS a good dividend stock?
What should investors monitor going forward?
Does the promoter benefit most from this dividend?
Disclaimer
This article is for informational and educational purposes only and does not constitute investment, financial, legal or tax advice. ShareBazaar Online is not a SEBI-registered investment adviser. It does not offer any buy, sell or hold recommendation on any security mentioned. Figures are sourced from the company's audited filings, Screener.in, exchange disclosures and public market data; market prices, yields and ratios change constantly and should be independently verified before use. Dividend approval, record date and payment are subject to statutory and corporate processes. Investments in securities are subject to market risks; please read all related documents carefully and consult a qualified, SEBI-registered financial adviser before making any investment decision. The author and publisher accept no liability for any loss arising from the use of this information.