
Dividend Snapshot
Dynamatic Technologies Limited (NSE: DYNAMATECH | BSE: 505242 | ISIN: INE221B01012) has declared an interim dividend of ₹3.00 per equity share for the financial year 2026-27. On a face value of ₹10, that headline works out to a 30% dividend — a number that sounds large until you measure it against the share price. At the announcement-window price of roughly ₹10,050 and the latest market price of about ₹12,071, the real cash yield is only about 0.03%. This is a precision-engineering and aerospace company whose stock has re-rated sharply; the dividend is a token shareholder gesture, not an income stream.
Dividend Details
- Dividend Type: Interim Dividend
- Dividend Per Share: ₹3.00
- Dividend Percentage (on face value): 30%
- Face Value: ₹10
- Financial Year: FY 2026-27
- Announcement Date: 07 August 2026
- Record Date: 14 August 2026
Market Context
- Latest Market Price: ~₹12,071 (NSE, 15 Sep 2026)
- Real Dividend Yield: ~0.03%
- Market Capitalisation: ~₹8,198 Cr
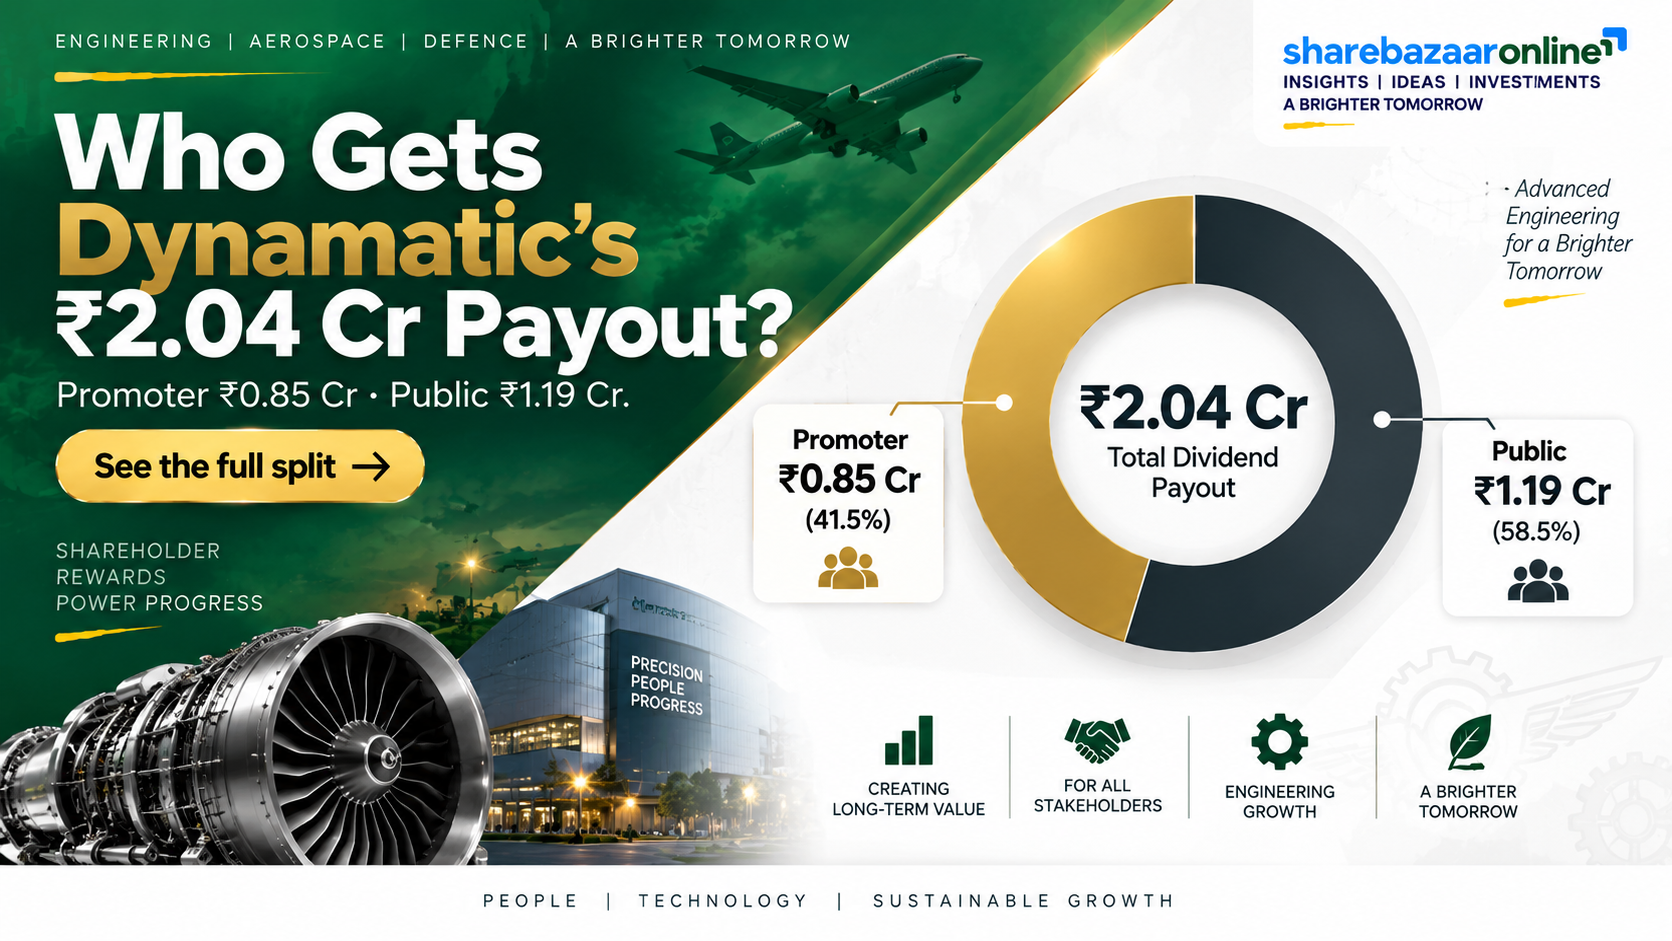
- Total Dividend Outflow: ~₹2.04 Cr
- Promoter Holding: 41.50%
- Shares Outstanding: ~67.90 lakh
The one-line takeaway: The "30%" label is calculated on the ₹10 face value. On the price a real investor actually pays, the yield rounds to almost nothing. Dynamatic is a capital-appreciation story with a symbolic payout attached — and it is a leveraged one, which makes the capital-allocation question the more interesting part of this announcement.
Dividend Announcement Summary
At its board meeting held on 07 August 2026 (conducted at Eisenwerk Erla GmbH, Schwarzenberg, Germany), the Board of Directors of Dynamatic Technologies approved the un-audited standalone and consolidated financial results for the quarter ended 30 June 2026 and declared an interim dividend of ₹3.00 per equity share (30% on ₹10 face value) for FY 2026-27. The record date for determining eligible shareholders was fixed as 14 August 2026, and the company stated the dividend would be paid within the statutory timelines.
What the Board Approved
- Interim dividend of ₹3/share for FY27 (an interim payout does not require prior AGM approval)
- Un-audited Q1 FY27 standalone & consolidated results
- Deloitte Haskins & Sells LLP issued an unmodified limited-review conclusion
Context From the Filing
- This is a second distribution in play: a separate ₹5 final dividend (50%) for FY26 was also recommended and subsequently approved at the AGM
- FY26 total dividend therefore stood at ₹10/share (₹5 interim + ₹5 final)
- The ₹3 interim is the first payout of the new FY27 cycle
Key Dates Timeline
| Event | Date | Status |
|---|---|---|
| Board Meeting / Announcement | 07 August 2026 | Concluded |
| Ex-Date | ~13 August 2026 (inferred) | Passed |
| Record Date | 14 August 2026 | Passed |
| Payment Date | Within statutory timelines | Not separately disclosed |
Note: The company disclosed the record date (14 August 2026) but did not state a specific ex-date or payment date in the board-meeting outcome. Under India's T+1 settlement, the ex-date typically falls one trading day before the record date, so ~13 August 2026 is an inferred figure pending confirmation against the official NSE/BSE corporate-action circular. The interim dividend must be paid within 30 days of declaration under the Companies Act, 2013. Shareholders who held the stock on the record date were eligible.
Dividend Yield Analysis
This is where the "30% dividend" headline collapses. A dividend percentage in India is quoted on face value, not market price. Dynamatic's face value is ₹10, so ₹3 per share is 30% of ₹10. But nobody buys the share at ₹10 — it trades north of ₹12,000. The yield that matters is the dividend divided by the price you actually pay.
The Face-Value Illusion
- Headline yield (on ₹10 face value): 30.0%
- Real yield at announcement price ~₹10,050: ~0.030%
- Real yield at latest price ~₹12,071: ~0.025%
- Trailing yield on FY26 total ₹10/share: ~0.08%
Why the Yield Is So Low
The low yield is not a sign of a weak dividend so much as a sign of a very high share price relative to earnings and dividends. Dynamatic trades at a trailing P/E in the region of 200+, reflecting an aerospace/defence re-rating rather than dividend logic. For every ₹100 invested at the current price, the interim dividend returns roughly 2.5 paise. Anyone buying DYNAMATECH for income is buying the wrong stock; the thesis here is capital appreciation.
Dividend History Analysis
| Declared / Ex Period | Dividend Per Share | Type |
|---|---|---|
| Aug 2026 (FY27) | ₹3.00 | Interim |
| May 2026 (FY26 final) | ₹5.00 | Final (AGM-approved) |
| Feb 2026 (FY26 interim) | ₹5.00 | Interim |
| Nov 2024 (FY25) | ₹2.00 | Interim |
| Aug 2024 (FY24) | ₹5.00 | Final |
| Feb 2024 (FY24) | ₹5.00 | Interim |
| Jun 2023 (FY23) | ₹7.00 | Final |
| Aug 2022 (FY22) | ₹3.00 | Final |
Source: exchange filings and public dividend records. Dates shown are declaration/ex periods; figures are per share on ₹10 face value. Verify each line against the official NSE/BSE corporate-action history before publication.
Pattern Read
- Dynamatic is a consistent but modest payer — it has paid something in most recent years
- Payout has stepped up in the last two years: ₹10/share in both FY24 and FY26, versus ₹2–7 in earlier years
- The company switched to a twin interim + final rhythm rather than a single annual dividend
Classification
On the record above, Dynamatic reads as a Consistent (but low-yield) Payer. Screener data shows the dividend payout has averaged only about 9.9% of profit over the last three years — the company keeps the vast majority of its earnings to fund capex and service debt, which is consistent with a growth-and-deleverage posture rather than a distribution one.
Financial Performance Analysis
Q1 FY27 (quarter ended 30 June 2026) was a strong quarter on the surface. On a consolidated basis, revenue from operations rose to ₹424.8 Cr (₹42,481 lakhs), up ~14.5% year-on-year, and net profit jumped to ₹20.79 Cr (₹2,079 lakhs), up ~93% YoY. Consolidated EPS for the quarter was ₹30.62.
Q1 FY27 — Consolidated
- Revenue: ₹424.8 Cr (+14.5% YoY)
- Total income: ₹430.7 Cr
- PAT: ₹20.79 Cr (+93% YoY)
- EPS: ₹30.62
- Finance cost: ₹14.9 Cr in the quarter alone
Q1 FY27 — Standalone
- Revenue: ₹200.3 Cr
- PAT: ₹9.88 Cr
- EPS: ₹14.55
- Segment mix: Hydraulics ₹107.8 Cr, Aerospace ₹92.3 Cr
The Forensic Point: Consolidated vs Standalone Flips Sign
Here is what aggregators gloss over. In Q1 FY27, consolidated PAT (₹20.79 Cr) was more than double standalone PAT (₹9.88 Cr) — the overseas and subsidiary operations added heavily. But look at the full year FY26: standalone PAT was ₹44.47 Cr while consolidated PAT was only ₹32.41 Cr. The subsidiaries subtracted roughly ₹12 Cr from group profit over FY26. In other words, the same group structure that flattered Q1 dragged the prior full year. This is a business whose group earnings are lumpy and swing on subsidiary performance (notably the UK Hydraulic operations undergoing restructuring), so one strong quarter should not be extrapolated.
Operating Leverage & the Exceptional Item
FY26 profit was also depressed by a one-time non-cash exceptional charge tied to India's new Labour Codes — ₹10.95 Cr (standalone) / ₹14.27 Cr (consolidated) — relating to a revised definition of "wages" affecting gratuity and compensated absences, booked in Q3 FY26. A separate non-cash tax charge of ₹5.62 Cr arose in the UK subsidiary (DLUK) from an intra-group IP transfer, inflating the group's effective tax rate. Both are non-cash and non-recurring, but they are the reason reported consolidated FY26 PAT looks weak against a growing top line.
Cash Flow Analysis
Reported profit is an opinion; cash is a fact — and Dynamatic's cash picture is the reason this dividend deserves scrutiny even though the rupee amount is tiny. The interim outflow is only about ₹2.04 Cr, which the company can obviously afford. The real story is where the cash goes before it reaches shareholders: a large chunk is consumed by interest.
What We Can Confirm
- Consolidated finance cost was ₹14.9 Cr in Q1 FY27 alone and ₹58.0 Cr for FY26
- The interim dividend (₹2.04 Cr) equals only about 14% of a single quarter's interest bill
- Third-party analysis flags that debt is poorly covered by operating cash flow (OCF around 17% of total debt)
What To Verify
- Exact FY26 Operating Cash Flow: Not independently retrieved this session — confirm from the FY26 annual report cash-flow statement
- Exact Free Cash Flow after capex: Not independently retrieved this session
- Working-capital swings from inventory build (finished goods rose in Q1)
How the dividend is funded: Given cash and short-term investments of only about ₹45.8 Cr against total debt of roughly ₹594 Cr, the ₹2.04 Cr interim is best read as being paid out of current operating earnings rather than from a large cash pile — the company simply does not hold a large cash pile. It is a small, self-funding gesture layered on top of a balance sheet that is still carrying meaningful borrowings.
Balance Sheet Strength
Leverage Profile (external market data)
- Total debt: ~₹594 Cr
- Long-term debt (Jun 2026): ~₹330 Cr (up ~24% YoY)
- Cash & short-term investments: ~₹45.8 Cr
- Net debt: ~₹548 Cr
- Debt-to-equity: ~0.78x (≈78%)
- Interest coverage (EBIT/interest): ~1.8x
What This Means
An interest coverage of only ~1.8x is thin — it means operating profit covers the interest bill less than twice over. Long-term debt grew ~24% over the past year even as the company kept paying dividends. The equity base (~₹760 Cr net worth, book value in the ~₹1,100–1,250 range per share) is solid, and segment assets are large, but this is emphatically not a debt-free, cash-rich balance sheet. The dividend is affordable; the debt servicing is the constraint.
Balance-sheet leverage figures are drawn from third-party market data providers (trailing basis) and should be reconciled against the FY26 audited balance sheet and the Q1 FY27 filing before publication. The Q1 FY27 filing confirms consolidated total segment liabilities of ₹1,094.7 Cr against total segment assets of ₹1,913.2 Cr.
Dividend Sustainability Analysis
Because the payout is so small relative to the business, sustainability here is about willingness and consistency, not affordability. We run four tests.
1. Earnings Coverage
Very strong. The ₹3 interim is covered ~4.9x by Q1 standalone EPS (₹14.55) and ~10.2x by consolidated EPS (₹30.62). The interim payout ratio is just ~10–21% of quarterly earnings.
2. Operating Cash Flow Coverage
Adequate but not verified precisely. The outflow is a fraction of even one quarter's operating flows, but OCF is weak relative to the debt load, so the group has limited surplus cash after interest and capex.
3. Free Cash Flow Coverage
To be confirmed. With rising long-term debt and ongoing aerospace capex, FCF is likely modest. The dividend is tiny enough to be covered, but the group is not generating large distributable surplus.
4. Liquidity / Cash Coverage
Thin cash, ample coverage of a tiny payout. Cash of ~₹45.8 Cr covers the ~₹2.04 Cr outflow roughly 22x over — but that same cash is small versus ~₹594 Cr of debt.
Verdict: Sustainable (as a token payout)
The ₹3 interim is comfortably Sustainable on earnings and cash. The nuance investors should hold on to: sustainability of a small dividend is almost guaranteed, but it tells you nothing positive about yield. The more relevant risk is not a dividend cut — it is that a leveraged group in a lumpy, subsidiary-driven business may prioritise debt reduction and capex over dividend growth, which is arguably the right call.
Peer Comparison
| Metric | Dynamatic Technologies |
|---|---|
| Sector | Aerospace & Defence / Precision Engineering |
| Dividend Yield | ~0.03% (well below broad industrial average ~1.3%) |
| 3-yr Dividend Payout | ~9.9% of profit (low) |
| ROE | ~6.2% (3-yr avg ~7.6%) |
| ROCE | ~8.7% |
| Debt-to-Equity | ~0.78x |
Against the aerospace-and-defence and precision-engineering peer set, Dynamatic screens as a high-multiple, low-yield, moderately-leveraged name. Its ROE (~6%) and ROCE (~9%) are on the softer side for the sector, which is one reason the dividend payout stays low — capital is needed inside the business. Investors comparing DYNAMATECH to genuine dividend payers in capital goods will find the yield gap stark: most industrial dividend stocks yield around 1%+, while Dynamatic yields a rounding error. A precise peer table (specific competitor yields, payout ratios and ROCE) should be built from live Screener/Semrush peer data before publication.
Promoter Impact Analysis
Who Gets the Cash
- Total interim outflow: ~₹2.04 Cr
- Promoter holding: 41.50%
- Promoter share of the payout: ~₹0.85 Cr
- Public / minority share: ~₹1.19 Cr
Reading It
With a 41.5% stake, the promoter family (Malhoutra group) receives roughly ₹85 lakh from this interim. That is immaterial in absolute terms — not the kind of number that suggests dividends are being used as a promoter cash-extraction tool. Worth noting: promoter holding edged down from 41.87% (Dec 2025) to 41.50% (Mar 2026), and there was a disclosed promoter-group sale of 25,000 shares in March 2026. The dividend is not the promoter story here; the small stake trims are.
Taxation Analysis
Since FY 2020-21, Dividend Distribution Tax (DDT) has been abolished. Dividends are now fully taxable in the shareholder's hands at their applicable income-tax slab rate and reported under "Income from Other Sources" (Schedule OS).
The Rules (FY 2025-26 onward)
- Taxed at your slab rate — no special flat rate, no exemption
- TDS under Section 194: 10% deducted only if total dividend from one company exceeds ₹10,000 in a financial year (threshold raised from ₹5,000, effective 01 April 2025)
- No PAN / inoperative PAN → TDS at 20%
- NRIs: 20% under Section 195 (or lower DTAA rate with Form 10F + TRC)
- Section 57: interest on money borrowed to buy the shares is deductible, capped at 20% of dividend income
Worked Example
An investor holds 1,000 shares, receives a dividend of ₹10/share, and is in the 30% slab:
- Gross dividend: ₹10,000
- TDS u/s 194: ₹0 (at exactly ₹10,000 the threshold is not exceeded; one rupee more triggers 10%)
- Tax at 30% slab: ₹3,000 (plus applicable cess)
- Net in hand after tax: ₹7,000
- Effective post-tax yield falls to roughly 70% of the gross yield
Applied to this specific interim (₹3/share): a holder of 1,000 shares receives ₹3,000 gross — below the ₹10,000 TDS threshold, so no tax is deducted at source, but the ₹3,000 is still added to total income and taxed at the investor's slab. For a 30%-slab investor, that is ₹900 of tax, leaving ₹2,100 net.
Key Risks
- Leverage & thin interest cover: Total debt ~₹594 Cr with interest coverage of only ~1.8x. Rising long-term debt (up ~24% YoY) leaves limited cushion if profitability wobbles.
- Lumpy, subsidiary-driven earnings: FY26 subsidiaries subtracted ~₹12 Cr from group profit while Q1 FY27 they added heavily. Group PAT can swing sharply quarter to quarter.
- UK / European exposure: The Dynamatic Limited UK (DLUK) Hydraulic division has faced European supply-chain disruption, financial losses, redundancy provisions and an ongoing transfer of production to India — a restructuring that carries execution risk.
- Extreme valuation: A trailing P/E well above 200 leaves the stock highly sensitive to any earnings disappointment; the dividend offers essentially no downside cushion at ~0.03% yield.
- Customer / OEM concentration: Revenue depends on a small set of global aerospace and automotive OEMs (Airbus, Boeing, Dassault, Bell, Daimler, etc.); order deferrals or pricing pressure would hit hard.
- Regulatory / cost overhang: The new Labour Codes have already forced a one-time gratuity/compensated-absence charge; final rules could bring further cost adjustments.
What To Monitor
- Debt trajectory & interest coverage: Watch whether long-term debt keeps rising and whether interest coverage improves above 2x as aerospace revenue scales.
- Aerospace order execution: Ramp-up of Airbus A220 doors, Dassault Falcon 6X rear-fuselage work and other OEM programmes — the segment anchoring group profitability.
- DLUK restructuring outcome: Whether the transfer of UK Hydraulic production to India stabilises subsidiary losses and lifts consolidated margins.
- Operating cash flow vs capex: Confirm from each quarterly and annual report whether OCF is comfortably funding capex, interest and the (small) dividend.
- Promoter holding trend: Any further promoter-group share sales after the Mar 2026 trim from 41.87% to 41.50%.
- Payout policy: Whether management lifts the dividend as deleveraging progresses, or continues to retain earnings for growth.
Conclusion
Dynamatic Technologies' ₹3 interim dividend for FY27 is a textbook example of the face-value illusion: a "30%" headline that translates into a real yield of about 0.03% once measured against the ₹12,000+ share price. The payout is small (~₹2.04 Cr total), comfortably covered by earnings, and clearly sustainable as a token distribution — but it is not, and was never meant to be, an income proposition.
Positives
- Strong Q1 FY27 (consolidated PAT +93% YoY)
- Aerospace segment scaling with marquee OEM programmes
- Consistent dividend record; comfortable earnings coverage
- Exceptional charges dragging FY26 were non-cash and non-recurring
Negatives
- Negligible real yield (~0.03%)
- Leveraged balance sheet; interest coverage ~1.8x
- Lumpy, subsidiary-dependent earnings; FY26 group PAT below standalone
- Very rich valuation offering no dividend downside cushion
The signal in this announcement is not the dividend itself — it is the reminder that DYNAMATECH is a growth-and-deleverage aerospace story where the payout is symbolic and the capital-allocation discipline (debt versus dividends versus capex) is what actually matters. We present the evidence; the decision is yours.
Frequently Asked Questions
What dividend has Dynamatic Technologies announced?
What is the dividend yield on Dynamatic Technologies shares?
What was the record date for the Dynamatic Technologies dividend?
What was the ex-dividend date?
When will the dividend be paid?
Who was eligible for the dividend?
How is this dividend taxed?
Is the Dynamatic Technologies dividend sustainable?
What is Dynamatic Technologies' dividend history?
Why is the consolidated profit sometimes lower than standalone?
How much debt does Dynamatic Technologies carry?
How much does the promoter receive from this dividend?
What should investors monitor going forward?
Is Dynamatic Technologies a good stock for dividend income?
Disclaimer
This article is for informational and educational purposes only and does not constitute investment advice, a research report, or any recommendation to buy, sell or hold any security. ShareBazaar Online is not a SEBI-registered investment adviser or research analyst. Dividend figures, dates and per-share data are based on the company's exchange filing dated 07 August 2026; market prices, financial ratios, shareholding, debt and peer figures are drawn from third-party public sources and are indicative, subject to revision, and should be independently verified against the company's audited financial statements and official NSE/BSE corporate-action disclosures. Share prices and yields fluctuate. Keyword and search-demand metrics referenced in the publishing package were not independently verified this session. Please consult a qualified, SEBI-registered financial adviser and conduct your own due diligence before making any investment decision. ShareBazaar Online accepts no liability for any loss arising from the use of this content.