
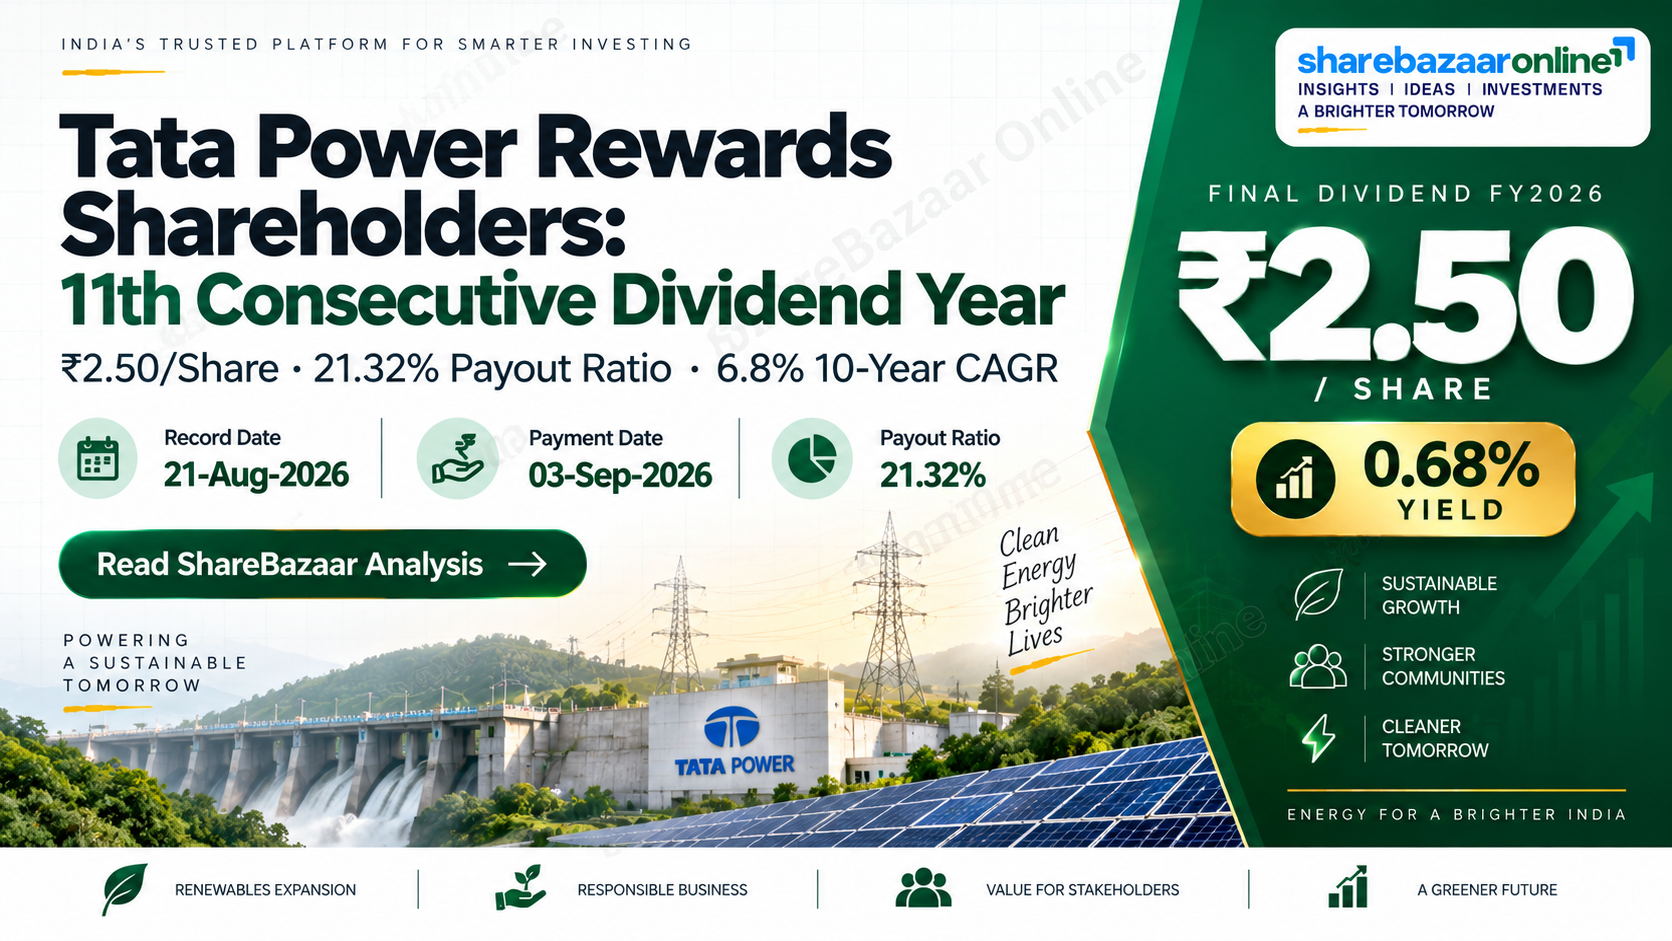
Company Overview – The Tata Power Company Limited
The Tata Power Company Limited (NSE: TATAPOWER | BSE: 500400 | ISIN: INE245A01021) is India’s largest integrated power utility, operating across the entire electricity value chain — generation, transmission, distribution and renewable energy. The company commands an installed capacity exceeding 14 GW across thermal, hydro, solar and wind assets. As a flagship Tata Group entity with a 110+ year legacy, Tata Power is aggressively pivoting towards clean energy, targeting 80% renewable capacity by 2030. In FY2026, consolidated revenue stood at ₹62,429 Crore with a PAT of ₹3,747 Crore (attributable to owners). Promoter holding stands at 46.86%.
Tata Power Financial Analysis – FY2026 Consolidated
Revenue & Profitability
- Revenue: ₹62,429 Crore (down 4.8% YoY)
- EBITDA: ₹12,516 Crore
- PAT (Owners): ₹3,747 Crore (down 15.2% YoY)
- EPS: ₹11.72
Return Ratios & Leverage
- ROE: 10.2%
- ROCE: 10.5%
- Total Borrowings: ₹76,141 Crore
- Net Debt: ₹73,116 Crore
Key Observation: Revenue declined 4.8% while PAT fell a sharper 15.2%, signalling operating leverage working in reverse. Heavy capital expenditure of ₹13,695 Crore for the renewable energy transition is straining near-term profitability. Both revenue and profit declines deserve close monitoring in coming quarters. Sources: Company filings, Screener.in.
Tata Power Dividend History – Last 11 Years
| Financial Year | DPS (₹) | Dividend % | YoY Growth |
|---|---|---|---|
| FY2026 | ₹2.50 | 250% | +11.1% |
| FY2025 | ₹2.25 | 225% | +12.5% |
| FY2024 | ₹2.00 | 200% | 0.0% |
| FY2023 | ₹2.00 | 200% | +14.3% |
| FY2022 | ₹1.75 | 175% | +12.9% |
| FY2021 | ₹1.55 | 155% | 0.0% |
| FY2020 | ₹1.55 | 155% | +19.2% |
| FY2019 | ₹1.30 | 130% | 0.0% |
| FY2018 | ₹1.30 | 130% | 0.0% |
| FY2017 | ₹1.30 | 130% | 0.0% |
| FY2016 | ₹1.30 | 130% | — |
Classification: Consistent Payer. Tata Power has paid dividends every year for the past 11 years without a single cut or suspension. The 10-year CAGR stands at 6.8%. Notably, dividends remained flat during FY2017–FY2019 and FY2020–FY2021, followed by a re-acceleration from FY2022 onwards as profitability improved. Source: Company annual reports.
Expert Commentary – Tata Power Dividend FY2026
The Face-Value Yield Illusion. The headline “250% dividend” sounds spectacular. In reality, 250% is calculated on Tata Power’s ₹1 face value — translating to just ₹2.50 per share. Against a market price of ~₹367, the actual dividend yield is a modest 0.68%. This is well below typical fixed-deposit rates and even the sector average. Investors chasing the “250%” headline without understanding the face-value arithmetic risk overpaying for yield that barely exists in real terms. The 250% figure is a marketing artefact of the ₹1 face value, not a measure of shareholder return. Always evaluate dividends in absolute rupees per share and percentage yield against market price.
Tata Power Future Outlook & Capital Allocation
Tata Power is in the middle of a multi-year capital expenditure cycle targeting renewable energy dominance. Capex of ₹13,695 Crore in FY2026 dwarfs operating cash flow of ₹5,993 Crore, creating deeply negative free cash flow of ₹−7,702 Crore. Management could have reduced the ₹799 Crore dividend outflow and redirected towards debt reduction (total borrowings: ₹76,141 Crore) or funded more capex internally. However, the Tata Group’s reputation for consistent dividend payments makes a cut unlikely. With the USD 490.32 million arbitration contingent liability flagged by auditors, investors should watch whether the green transition can generate sufficient returns to justify this leveraged growth strategy.
Dividend Snapshot – Tata Power Company Limited
Company Details
- Company: The Tata Power Company Limited
- NSE Symbol: TATAPOWER
- BSE Code: 500400
- ISIN: INE245A01021
- Face Value: ₹1.00
- Equity Capital: ₹319.56 Crore
- Shares Outstanding: 319.56 Crore
Dividend Details
- Dividend Type: Final Dividend
- Dividend Per Share: ₹2.50
- Dividend %: 250%
- Total Outflow: ₹798.90 Crore
- Financial Year: FY2025–26
- AGM Approval: July 7, 2026
- Payout Ratio: 21.32%
Tata Power Dividend Announcement Summary
On May 12, 2026, the Board of Directors of The Tata Power Company Limited recommended a final dividend of ₹2.50 per equity share (250% on face value of ₹1) for the financial year ended March 31, 2026. This represents an 11.1% increase over the FY2025 dividend of ₹2.25. The dividend is subject to approval by shareholders at the 106th Annual General Meeting scheduled for July 7, 2026. On the announcement date, Tata Power’s stock closed at ₹418.40 on NSE, implying an announcement-date yield of 0.60%. The total dividend outflow is estimated at ₹798.90 Crore.
Key Dates Timeline – Tata Power Dividend FY2026
Announcement
12 May 2026
Ex-Date (Inferred)
22 Jun 2026
Record Date
23 Jun 2026
Payment Date
10 Jul 2026
* Ex-date is inferred as one trading day prior to the record date under India’s T+1 settlement cycle. The record date of June 23, 2026 has already passed. Only shareholders who held shares on or before the ex-date (June 22, 2026) were eligible for this dividend.
Tata Power Dividend Yield Analysis
Yield at Current Price
0.68%
CMP: ₹367 | DPS: ₹2.50
Yield at Announcement Price
0.60%
CMP (May 12): ₹418.40 | DPS: ₹2.50
Yield Reality Check
Tata Power’s current yield of 0.68% is notably higher than the 0.60% at announcement — but this increase is driven by a 12.3% decline in share price (from ₹418.40 to ~₹367), not an improvement in dividend income. A rising yield on a falling stock price is a warning signal, not a buying signal. This yield sits significantly below bank fixed deposit rates of 6–7% and the sector peer average of 2–3%. Tata Power is a growth-oriented utility, not an income stock. Source: NSE price data.
Tata Power Dividend History Analysis
Tata Power has demonstrated consistent dividend payments over the past 11 years, with zero cuts or suspensions. The dividend has grown from ₹1.30 (FY2016) to ₹2.50 (FY2026) at a 10-year CAGR of 6.8%. However, the growth has been uneven — dividends remained stagnant during FY2016–FY2019 (four consecutive years at ₹1.30) before resuming an upward trajectory in FY2020. The recent acceleration from ₹1.75 (FY2022) to ₹2.50 (FY2026) represents a 43% cumulative increase over four years. No special dividends have been paid. The company’s low payout ratio of 21.32% leaves significant headroom for future increases if management chooses. Source: Company annual reports.
Tata Power Financial Performance Analysis
Operating Leverage — FY2026
- Revenue Growth: −4.8%
- PAT Growth (Owners): −15.2%
- FY2026 Revenue: ₹62,429 Cr (vs ₹65,545 Cr in FY25)
- FY2026 PAT: ₹3,747 Cr (vs ₹4,418 Cr in FY25)
Earnings Quality Concern
Revenue declined 4.8% but PAT fell a steeper 15.2%, indicating negative operating leverage. When profits fall faster than revenue, fixed costs are amplifying the decline. This typically signals rising interest costs (₹76,141 Cr borrowings), employee expenses, or project-level inefficiencies. This divergence must be monitored closely. Source: Audited financial results.
Tata Power Cash Flow Analysis – FY2026
Cash Flow Breakdown
- Operating Cash Flow (OCF): ₹5,993 Crore
- Capital Expenditure: ₹13,695 Crore
- Free Cash Flow: ₹−7,702 Crore
- Dividend Outflow: ₹799 Crore
OCF Deterioration
- FY2025 OCF: ~₹10,654 Crore
- FY2026 OCF: ₹5,993 Crore
- YoY OCF Decline: −44%
Critical Finding: Free cash flow is deeply negative at ₹−7,702 Crore because capital expenditure (₹13,695 Crore) is 2.3x the operating cash flow. The dividend of ₹799 Crore is being funded from existing cash reserves and borrowings, not from surplus free cash flow. Additionally, OCF itself has fallen 44% year-over-year, a significant deterioration in cash generation quality. This is the most important red flag in Tata Power’s dividend story — reported profits look healthy, but cash flows tell a different story. Sources: Audited cash flow statement, Screener.in.
Tata Power Balance Sheet Strength
Debt Position
- Total Borrowings: ₹76,141 Crore
- Cash & Equivalents: ₹3,025 Crore
- Net Debt: ₹73,116 Crore
Contingent Liability
The statutory auditors (S R B C & CO LLP) flagged an Emphasis of Matter regarding a USD 490.32 million (~₹4,150 Crore) arbitration award. This is a material contingent liability equal to 110% of annual PAT. If crystallised, it could significantly impact the balance sheet and future dividend capacity.
Tata Power carries substantial leverage with net debt of ₹73,116 Crore against annual PAT of ₹3,747 Crore — a net debt-to-PAT ratio of roughly 19.5x. While this is typical for infrastructure utilities funding large projects, it limits financial flexibility. Cash on hand covers just 3.79x the annual dividend, providing a modest but not excessive buffer. Source: Balance sheet filings.
Tata Power Dividend Sustainability Analysis
Four-Test Sustainability Scorecard
Earnings Coverage
4.69x (EPS ₹11.72 / DPS ₹2.50)
OCF Coverage
7.50x (OCF ₹5,993 Cr / Div ₹799 Cr)
Positive Free Cash Flow
FAIL: FCF ₹−7,702 Crore
Cash Coverage
3.79x (Cash ₹3,025 Cr / Div ₹799 Cr)
Verdict: Sustainable (3/4 tests passed). Tata Power’s dividend is comfortably covered by earnings and operating cash flow. The low payout ratio of 21.32% provides significant headroom. However, the critical failure on the FCF test is a structural concern — the company is investing far more than it earns in cash, funding the gap through borrowings. As long as the capex cycle continues, dividends are effectively being paid from borrowed money at the consolidated level. This is sustainable in the near term given Tata Group backing, but long-term sustainability hinges on the renewable energy projects generating adequate returns.
Tata Power Peer Comparison – Power Sector Dividends
| Company | CMP (₹) | Dividend Yield | Payout Ratio | ROE | ROCE |
|---|---|---|---|---|---|
| Tata Power | 367 | 0.68% | 21.3% | 10.2% | 10.5% |
| NTPC | 324 | 2.78% | 32.0% | 15.1% | 8.9% |
| Power Grid Corp | 268 | 3.36% | 53.0% | 15.3% | 9.1% |
| JSW Energy | 526 | 0.38% | 16.0% | 8.0% | 8.2% |
Tata Power’s 0.68% yield sits between two extremes: significantly below pure-play utilities NTPC (2.78%) and Power Grid (3.36%), but above growth-focused JSW Energy (0.38%). The established PSU utilities offer 4–5x higher yields with higher payout ratios. Tata Power’s lower payout reflects its growth reinvestment strategy. For income-seeking investors, NTPC and Power Grid are far superior choices; Tata Power is better positioned as a growth play where dividends are incidental. Sources: Screener.in (data as of Sep 2026).
Tata Power Promoter Impact Analysis
Shareholding Pattern
- Promoter (Tata Sons): 46.86%
- FII: 10.04%
- DII: 17.98%
- Public & Others: 24.81%
Promoter Dividend Income
- Total Dividend Outflow: ₹798.90 Crore
- Promoter Share (46.86%): ₹374.36 Crore
- Minority Share (53.14%): ₹424.54 Crore
Tata Sons, as the promoter with 46.86% holding, receives approximately ₹374.36 Crore from this dividend. This income likely flows to Tata Sons’ broader investment corpus. The moderate payout ratio (21.32%) suggests management is balancing promoter income expectations with the company’s massive capex requirements. Minority shareholders proportionally benefit from the consistent dividend growth track record. Source: BSE shareholding filings.
Tata Power Dividend Taxation Analysis
Indian Dividend Tax Rules (FY2026–27)
Under the current Indian tax regime, dividends are taxable in the hands of shareholders at their applicable income tax slab rate. Companies deduct TDS at 10% on dividend payments exceeding ₹5,000 per financial year per shareholder. Investors must report dividend income under “Income from Other Sources” in their ITR. A standard deduction on dividend income is not available; however, interest expense up to 20% of dividend income may be claimed as deduction under Section 57.
Worked Example: 1,000 Shares at 30% Tax Slab
| Shares Held | 1,000 |
| Dividend Per Share | ₹2.50 |
| Gross Dividend | ₹2,500 |
| TDS @10% (applicable if > ₹5,000) | ₹0 (below threshold) |
| Income Tax @30% Slab | ₹750 |
| Net Dividend After Tax | ₹1,750 |
| Effective Post-Tax Yield | 0.48% |
Note: Cess and surcharge excluded for simplicity. Effective yield at 30% slab drops to just 0.48%, which is negligible as income.
Key Risks – Tata Power Dividend Investors
- Negative Free Cash Flow: FCF of ₹−7,702 Crore means the dividend is not funded by surplus cash generation. Sustained negative FCF could force a dividend cut if borrowing capacity is constrained.
- USD 490.32 Million Arbitration Liability: The auditor-flagged contingent liability (~₹4,150 Crore) is 110% of annual PAT. An adverse outcome could severely impact financials and dividend capacity.
- High Leverage: Total borrowings of ₹76,141 Crore create significant interest burden. Rising interest rates would squeeze profitability and cash flows further.
- Revenue and Profit Decline: FY2026 saw revenue drop 4.8% and PAT (owners) drop 15.2%. Continued decline could pressure management to redirect cash towards operations rather than dividends.
- Execution Risk on Renewable Transition: The massive capex programme depends on timely project commissioning and adequate power purchase agreements. Delays or unfavourable tariffs could impair returns.
- Regulatory Risk: Electricity distribution tariffs are government-regulated. Adverse tariff orders could compress margins across the regulated business.
- Share Price Erosion: The stock has fallen ~12% from the announcement date, eroding total shareholder returns despite the dividend increase.
What To Monitor – Tata Power Shareholders
- Quarterly OCF Trend: Watch whether operating cash flow recovers from the 44% YoY decline. Sustained low OCF would undermine dividend sustainability.
- Capex-to-OCF Ratio: Currently at 2.3x. Needs to trend below 1.0x for FCF to turn positive and dividends to be self-funded.
- Arbitration Outcome: Track the USD 490.32 million arbitration proceedings. Resolution (favourable or adverse) will materially impact financial outlook.
- Debt Trajectory: Monitor whether borrowings stabilise or continue rising. A rising debt trend alongside negative FCF is a compounding risk.
- Renewable Capacity Commissioning: Track progress against the 80% renewable target by 2030. Timely commissioning with viable tariffs is critical for future cash generation.
- Revenue Recovery: FY2026’s 4.8% revenue decline needs reversal. Monitor Q1 FY2027 results for signs of demand recovery or continued weakness.
- Promoter Holding Changes: Any change in Tata Sons’ 46.86% stake could signal shifting capital allocation priorities.
Conclusion – Tata Power FY2026 Dividend Assessment
Tata Power’s ₹2.50 final dividend for FY2026 represents a consistent 11th consecutive year of payments and a 6.8% 10-year CAGR — a track record few power sector peers match. The low payout ratio (21.32%) and strong earnings coverage (4.69x) provide near-term safety. However, the headline “250% dividend” obscures a market yield of just 0.68%, far below income-oriented alternatives. More concerning is the deeply negative free cash flow (₹−7,702 Crore), 44% OCF decline, a revenue contraction, falling profits, ₹76,141 Crore debt load, and a USD 490.32 million arbitration risk. This is a growth-stage utility funding an ambitious energy transition through leverage, not an income stock. The dividend is a token of consistency, not a meaningful income stream. Investors should evaluate Tata Power on its capital appreciation and renewable energy execution potential, not its dividend yield.
Frequently Asked Questions – Tata Power FY2026 Dividend
What dividend has Tata Power announced for FY2026?
What is the dividend yield of Tata Power?
What was the record date for Tata Power dividend?
What was the ex-date for Tata Power FY2026 dividend?
When will Tata Power pay the FY2026 dividend?
Who was eligible for the Tata Power FY2026 dividend?
How is Tata Power dividend taxed in India?
Is the Tata Power dividend sustainable?
What is Tata Power’s dividend history over the last 10 years?
What should investors monitor after Tata Power’s FY2026 dividend?
Why does Tata Power show 250% dividend but low yield?
How does Tata Power dividend yield compare to sector peers?
Disclaimer
This article is published by ShareBazaar Online for educational and informational purposes only. It does not constitute investment advice, a recommendation, or a solicitation to buy, sell, or hold any security. All financial data is sourced from company filings, BSE/NSE disclosures, and publicly available databases. While every effort has been made to ensure accuracy, ShareBazaar Online does not guarantee the completeness or timeliness of any information. Investors should consult a SEBI-registered investment advisor before making any investment decisions. Past dividend performance does not guarantee future payments. Keyword metrics marked “NIV” (Not Independently Verified) are editorial estimates. Market prices are indicative and may have changed since publication. ShareBazaar Online and its authors may or may not hold positions in the securities discussed.