
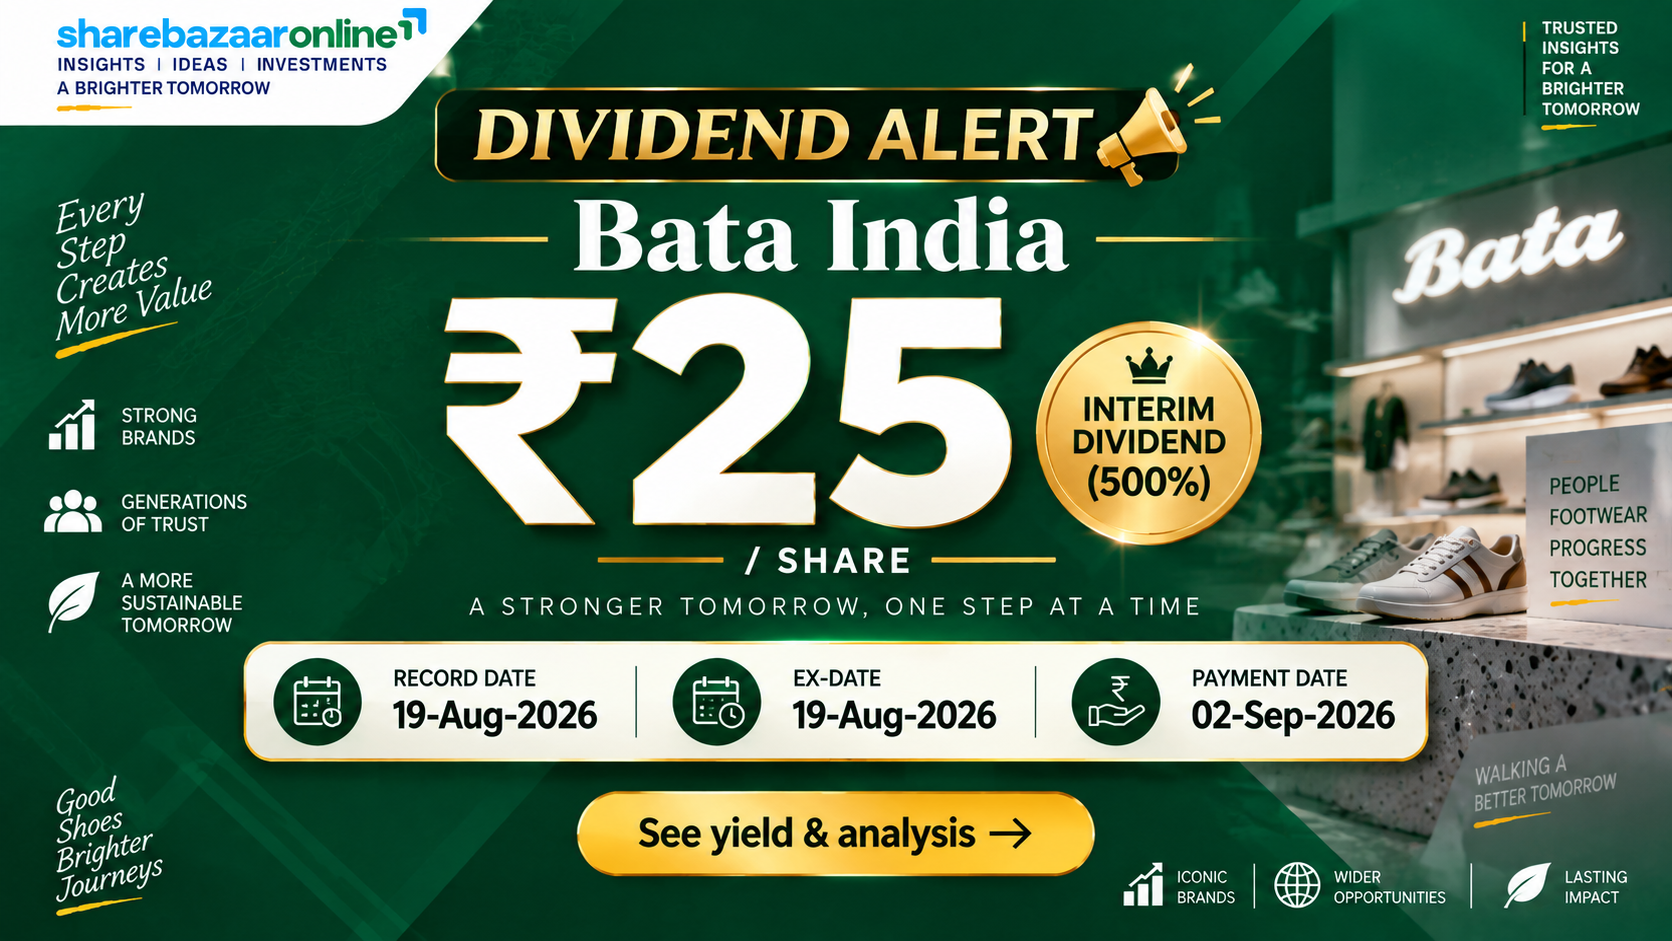
Dividend Snapshot – Bata India Limited
Bata India Limited (NSE: BATAINDIA | BSE: 500043 | ISIN: INE176A01028), India’s largest footwear retailer, declared an Interim Dividend of ₹25 per share on 11 August 2026 for the financial year ending 31 March 2027. The headline reads “500%”, but that percentage is calculated on the ₹5 face value — the real cash you receive is ₹25 per share, translating to a market-price dividend yield of roughly 3.97% at the current price of ₹629. This single interim payout is unusually large: it equals about 220% of the company’s entire trailing twelve-month profit.
Face value ₹5 | Estimated dividend outflow ~₹321 crore | Shares outstanding ~12.85 crore. Market price and yield figures sourced from Screener.in and exchange data as of 16 September 2026.
Bata India Limited Interim Dividend Announcement Summary
At its board meeting held on 11 August 2026, the Board of Directors of Bata India Limited declared an interim dividend of ₹25 per equity share (500%) on the fully paid-up equity shares of ₹5 each, for the current financial year ending 31 March 2027. The same meeting approved the unaudited standalone and consolidated financial results for the quarter ended 30 June 2026 (Q1 FY27).
What the company disclosed:
- Interim dividend: ₹25.00 per share on face value of ₹5 (declared under the FY2026-27 financial year).
- Record date fixed as Wednesday, 19 August 2026 to determine eligible members.
- Dividend payable from Wednesday, 02 September 2026 onwards to entitled shareholders.
- Being an interim dividend, board declaration is sufficient — no AGM approval is required for the payout to proceed.
The most striking feature of this announcement is scale. Bata India Limited reported a consolidated net profit of only ₹134 crore for the full year FY26 and ₹64 crore for Q1 FY27. Yet the interim dividend commits an estimated ₹321 crore of cash. In other words, the company is distributing more than twice its most recent annual profit in one interim payout — a signal that this is a deliberate return of accumulated cash and reserves, not a routine share of current earnings.
Bata India Limited Dividend Record Date and Payment Timeline
Announcement Date — 11 Aug 2026
Board declared the ₹25 interim dividend alongside Q1 FY27 results.
Ex-Dividend Date — 19 Aug 2026
Under T+1 settlement the ex-date and record date fell on the same day; buyers on this day were not entitled to the dividend.
Record Date — 19 Aug 2026
Shareholders on the register at the end of this date qualified for the payout.
Payment Date — from 02 Sep 2026
Dividend credited to eligible members from this date onwards.
The record date of 19 August 2026 was disclosed directly by Bata India Limited in its exchange filing. The ex-date of 19 August 2026 is consistent with India’s T+1 settlement cycle, in which the ex-date and record date typically coincide, and matches the dates reported by market data providers. Because the record date has already passed, this analysis is written for readers evaluating the payout and the company after the event rather than for eligibility planning.
Bata India Limited Dividend Yield Analysis
The “500%” label is the single most misunderstood number in any Indian dividend announcement. It does not mean a 500% return. It means 500% of the ₹5 face value, which is simply ₹25 in cash per share. What matters to an investor is the yield on the price actually paid for the stock.
Yield on this ₹25 interim dividend
Trailing 12-month yield
Yield reality check: Bata India Limited’s trailing yield of over 5% is genuinely high for a consumer/footwear stock — but part of that yield is manufactured by a falling share price, not just a generous dividend. The stock has dropped from a 52-week high of ₹1,281 to ₹629, a fall of roughly 50% over the past year. A yield that rises mainly because the price collapsed is not the same as a yield backed by rising profits. The other driver is the one-off scale of the ₹25 interim itself. On a normalised regular payout of around ₹9–12, the yield would be closer to 1.5–2%.
Bata India Limited Dividend History and Payout Trend
Bata India Limited has paid a dividend every year for well over a decade, including through the loss-making COVID year of FY21. The table below shows the total dividend by financial year (per share), alongside the consolidated payout ratio. Figures are approximate where reconstructed from reported payout ratios and earnings per share.
| Financial Year | Total Dividend / Share | Consolidated EPS | Payout Ratio |
|---|---|---|---|
| FY2021-22 | ~₹54.50 (incl. special) | ₹8.01 | ~680% |
| FY2022-23 | ~₹13.50 | ₹25.13 | ~54% |
| FY2023-24 | ~₹12.00 | ₹20.42 | ~59% |
| FY2024-25 | ~₹19.00 | ₹25.73 | ~74% |
| FY2025-26 | ~₹9.00 (final) | ₹10.44 | ~86% |
| FY2026-27 | ₹25.00 (interim so far) | ₹4.98 (Q1) | See note |
Two patterns stand out. First, Bata India Limited has a clear precedent for large one-off distributions — the FY22 payout of roughly ₹54.50 included a big special dividend, so a jumbo interim is not unprecedented. Second, the regular annual dividend has been erratic (₹13.50, then ₹12, then ₹19, then just ₹9 as FY26 profit collapsed). The ₹9 FY26 payout combined with the ₹25 FY27 interim confirms a company managing distributions from its balance sheet, not from a steady, growing earnings stream. On the ShareBazaar Online classification, Bata India Limited is best described as a consistent payer with irregular amounts — reliable in frequency, volatile in size.
Bata India Limited Financial Performance Analysis
To judge whether the dividend is affordable, start with the earnings that back it. Bata India Limited operates in a single segment — footwear and accessories — and its recent financials show a business with steady revenue but sharply compressed profitability.
Q1 FY27 (consolidated, qtr ended Jun 2026)
Full year FY26 (consolidated)
Operating leverage — the profit squeeze: Bata India Limited’s revenue has been broadly flat (₹3,452 cr in FY23 to ₹3,516 cr in FY26, a 3-year sales CAGR of roughly 1%), but net profit fell from ₹331 crore in FY25 to ₹134 crore in FY26 — a drop of nearly 60%. The pressure is below the operating line: higher depreciation (up to ~₹420 crore as leased store assets are amortised) and finance costs (~₹147 crore, largely lease interest under Ind AS 116) have eaten into a still-healthy ~21% operating margin. The Q1 FY27 profit recovery of about 23% year-on-year, driven by stronger premium demand, is encouraging but leaves annualised earnings far below the size of the interim dividend.
Bata India Limited Cash Flow Analysis
Reported profit is an opinion; cash is a fact. This is exactly where the Bata India Limited dividend story turns more favourable. Although FY26 net profit was only ₹134 crore, the company’s cash generation was far stronger.
The gap between profit and cash is explained by heavy non-cash depreciation on right-of-use (leased) store assets, which depresses accounting profit but not cash. Operating cash flow of ₹595 crore was 4.4 times reported net profit in FY26, and free cash flow of ₹530 crore was more than 1.6 times the ₹321 crore interim dividend. On this basis, the dividend is being funded from current cash generation and accumulated reserves — not from fresh borrowing or asset sales. That is a materially healthier funding story than the bare earnings coverage suggests, and it is the key reason the payout is affordable despite depressed profit.
Bata India Limited Balance Sheet Strength
Bata India Limited is fundamentally an asset-light, lease-heavy retailer. The ~₹1,387 crore of “borrowings” on the consolidated balance sheet is predominantly lease liabilities recognised under Ind AS 116 for its store network, not conventional bank debt; the company carries negligible interest-bearing term debt. The ₹321 crore interim dividend consumes about 21% of accumulated reserves in a single stroke. That is comfortably absorbable once, but it is not a level the company could repeat every quarter without eroding its net worth — reinforcing that this is a one-time capital return rather than a new run-rate.
Is the Bata India Limited Dividend Sustainable?
We score the payout on four independent coverage tests. A dividend that passes on cash but fails on earnings is telling you something important about how it is being funded.
Verdict: Conditionally Sustainable. The ₹25 interim dividend of Bata India Limited is not covered by current earnings (it exceeds trailing profit by more than 2x) but is covered by cash flow and reserves. This means the regular payout is affordable, but the ₹25 level itself is a one-time-elevated distribution that should be read as a return of accumulated cash. It is sustainable as a periodic special-style gesture and not as a repeatable quarterly run-rate. Continuation at this size depends squarely on the profit recovery seen in Q1 FY27 broadening into the full year.
Bata India Limited Dividend vs Footwear Peers
| Company | Dividend Yield | Payout Ratio | ROE | P/E |
|---|---|---|---|---|
| Bata India Limited | ~4.0% (5.4% TTM) | ~86% | 10.6% | ~46–54x |
| Metro Brands | ~0.6–2.2% | ~36% | ~21.7% | ~70x |
| Relaxo Footwears | ~1.0% | ~42% | ~8.0% | ~45x |
| Campus Activewear | ~0.4% | ~25% | Low | ~52x |
Bata India Limited stands out as by far the highest-yielding name in the listed footwear pack — peers such as Metro Brands, Relaxo and Campus Activewear yield roughly 0.4–2%. But the comparison must be read with care. Bata’s yield is elevated by its unusually high payout ratio (~86%) and by a share price that has roughly halved, while Metro Brands earns a far superior ~21.7% return on equity yet chooses to retain more and yield less. In footwear, a high yield is currently a signal of a mature, cash-returning business under earnings pressure, not of superior profitability. Peer metrics are sourced from Screener.in, Simply Wall St and Investing.com as of August–September 2026 and are approximate.
Bata India Limited Promoter and Shareholder Impact
Because dividends are paid on every share, the largest single beneficiary of the ₹321 crore payout is the promoter, Bata Corporation, which holds 50.16% of Bata India Limited. Here is how the estimated ₹321 crore outflow splits by shareholder category (based on the June 2026 shareholding pattern).
The promoter receiving roughly ₹161 crore is not, by itself, a red flag — every shareholder receives the same ₹25 per share, so the distribution is proportionate and fair to minority holders. However, a very large interim dividend that draws on reserves is a classic way for a majority foreign parent to repatriate accumulated Indian cash. Retail investors benefit equally per share, but should recognise that a reserve-funded payout of this size subtly favours cash extraction over reinvestment in growth — a trade-off worth weighing for a company whose revenue has barely grown in three years.
Bata India Limited Dividend Taxation Explained
Since the Dividend Distribution Tax was abolished in FY2020-21, dividends are taxable in the hands of the shareholder at their applicable income-tax slab rate. Two rules matter for the Bata India Limited dividend:
- TDS under Section 194: the company deducts 10% TDS if your total dividend from Bata India in the financial year exceeds ₹10,000 (this threshold was raised from ₹5,000 in Budget 2025, effective FY2025-26). Without a valid PAN, TDS is 20%.
- Slab-rate tax: the gross dividend is added to your total income and taxed at your slab. TDS is only a credit — you reconcile the balance when filing your return. A deduction for interest on money borrowed to buy the shares is allowed under Section 57, capped at 20% of the dividend.
Worked example — investor holding 1,000 Bata India shares (30% slab)
Note: exactly ₹10,000 of dividend does not trigger TDS — the amount must exceed ₹10,000. Tax outcomes vary by individual slab; consult a tax adviser for your situation.
Key Risks for Bata India Limited Dividend Investors
1. Dividend far exceeds earnings. At ~220% of trailing profit, the ₹25 interim cannot be repeated at current earnings without steadily drawing down reserves.
2. Earnings pressure. FY26 net profit fell nearly 60% year-on-year; a recovery is early and unproven beyond one quarter.
3. Stagnant topline. Revenue has grown at only ~1% CAGR over three years, limiting the earnings base that funds future dividends.
4. Yield flattered by a falling stock. The high yield partly reflects a ~50% price decline over the past year, not rising distributions.
5. Competitive and demand risk. Intense competition from Relaxo, Metro Brands, Campus and value/online players, plus discretionary-spending softness, pressures margins.
6. Foreign-exchange drag. The company has flagged forex losses on a USD-linked licence-rights liability from currency volatility.
What to Monitor in Bata India Limited
1. Profit recovery. Whether the ~23% Q1 FY27 profit growth sustains across full-year FY27 and rebuilds earnings toward the dividend.
2. Same-store sales & premiumisation. Growth in like-for-like sales, premium/sneaker mix and average selling prices.
3. Operating & net margins. Whether the ~21% operating margin translates into higher net profit as depreciation and finance costs stabilise.
4. Free cash flow trend. Continued FCF above ₹500 crore is what keeps any large dividend affordable.
5. Store network & e-commerce. Store additions/closures, franchise mix and online penetration as growth levers.
6. Future dividend cadence. Whether FY27 sees a normal final dividend on top of this interim, or whether the interim substitutes for it.
Should You Consider Bata India Limited for Dividend Income?
The Bata India Limited ₹25 interim dividend is a genuinely large cash return — a real market-price yield of around 4%, rising to roughly 5.4% on a trailing-twelve-month basis, which is exceptional for the footwear sector. Beneath the “500%” headline, the substance is a mature, cash-generative retailer choosing to hand accumulated cash back to shareholders.
Positives
- High real yield versus footwear peers.
- Free cash flow covers the dividend ~1.65x.
- Uninterrupted dividend track record, even in the FY21 loss year.
- Strong brand, dominant footwear retail footprint, low conventional debt.
Negatives
- Dividend is ~2x current earnings — not earnings-funded.
- Profit down ~60% in FY26; recovery unproven.
- Flat revenue and declining return ratios.
- Yield partly a function of a halved share price.
In line with ShareBazaar Online policy, this analysis does not offer a buy, sell or hold view. The picture is a high-yield, cash-backed but earnings-light interim dividend from a company in a profit-recovery phase. Weigh the positives, negatives, risks and monitoring points above against your own objectives and decide for yourself.
Frequently Asked Questions About Bata India Limited Dividend
What dividend has Bata India Limited announced?
What is the Bata India dividend yield?
Does “500%” mean a 500% return?
What was the record date for the Bata India dividend?
What was the ex-dividend date?
When will the Bata India dividend be paid?
Who was eligible for the dividend?
How is the Bata India dividend taxed?
Is the Bata India dividend sustainable?
How large is the total dividend payout?
What is Bata India Limited’s dividend history?
How does Bata’s dividend compare with footwear peers?
What should investors monitor going forward?
Disclaimer – Bata India Limited Dividend Analysis
This article is published by ShareBazaar Online for informational and educational purposes only and does not constitute investment advice, a recommendation, or an offer to buy or sell any security. ShareBazaar Online is not a SEBI-registered investment adviser. Dividend figures, dates and the ₹25 per share interim dividend are taken from Bata India Limited’s stock-exchange filing dated 11 August 2026; market price, financial, cash flow, shareholding and peer figures are sourced from Screener.in, exchange data and other public providers as of 16 September 2026 and are approximate. Computed ratios (dividend outflow, coverage, yields, promoter income) are estimates based on these inputs and may differ from company-reported figures. Securities markets are subject to risk; past dividends do not guarantee future payouts. Please verify all data independently and consult a qualified financial adviser before making any investment decision.