
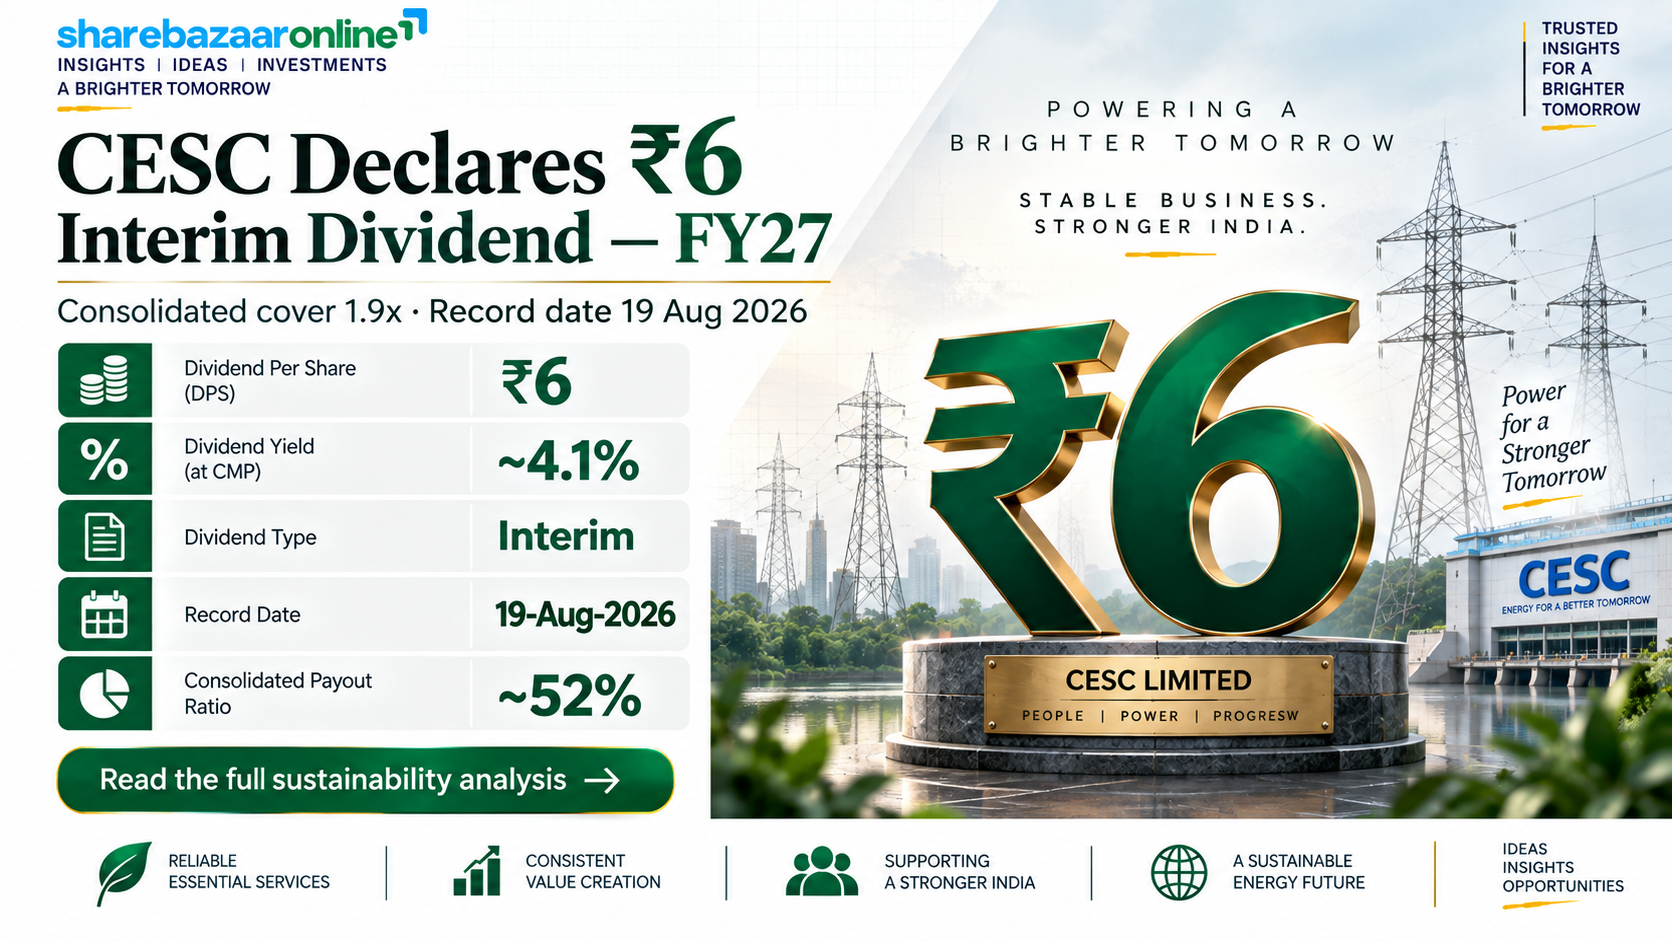
Dividend Snapshot – CESC Limited
~4.1%
Yield on this ₹6 interim (latest price)
~₹798 Cr
Estimated Dividend Outflow
1.9x
Consolidated EPS Cover (FY26)
~₹416 Cr
Promoter Dividend Income (52.11%)
CESC Limited Dividend Announcement Summary
At its board meeting held on 13 August 2026, the Board of Directors of CESC Limited approved the unaudited standalone and consolidated financial results for the first quarter (ended 30 June 2026) of FY 2026-27 and declared an interim dividend of ₹6.00 per equity share of face value Re 1 each — equivalent to 600% of face value.
The dividend is payable to shareholders whose names appear in the Register of Members (or as beneficial owners with NSDL and CDSL) at the close of business on the record date of 19 August 2026. The company's board meeting commenced at 10:45 a.m. and concluded at 12:45 p.m. IST. The results carried an unmodified (clean) limited review report from statutory auditors S.R. Batliboi & Co. LLP.
A notable point for readers: CESC has historically paid a single annual dividend, but in FY26 it moved to a higher ₹6 payout and has now declared a ₹6 interim early in FY27 (from Q1 itself). This signals a shift toward a larger and more frequent distribution policy, though the full-year FY27 payout is not yet known.
CESC Limited Dividend Record Date and Key Dates Timeline
Announcement Date
13 August 2026 (Board Meeting)
Ex-Dividend Date
19 August 2026 (under T+1 settlement)
Record Date
19 August 2026
Payment Date
Not Disclosed by Company (statutorily payable within 30 days of the record date)
To be eligible for the CESC Limited dividend, you must have held the shares before the ex-date of 19 August 2026. Under India's T+1 settlement cycle, the ex-date and record date fall on the same day, and buying the stock on the ex-date does not make you eligible.
The specific payment/credit date was not stated in the board outcome filing. As a rule, listed companies must dispatch or credit dividends within 30 days of the record date, so eligible shareholders can expect the credit by around mid-September 2026. (External: general SEBI/Companies Act norm; exact date not in the company filing.)
CESC Limited Dividend Yield Analysis
Why some websites show ~8% yield. Over the trailing twelve months CESC paid ₹6 (Oct 2025) + ₹6 (Aug 2026) = ₹12. On a ~₹145 price, that trailing figure works out to ~8.3%, which is what many aggregators quote. For this single interim of ₹6, the yield is closer to 4.1%. Investors should not assume ₹12 is a fixed annual rate — that depends on whether CESC declares a further FY27 dividend.
Even on the conservative single-dividend basis, ~4.1% is above the electric-utilities industry average of ~2.4%. (External: Simply Wall St industry benchmark.)
Yield reality check: Part of CESC's high headline yield reflects a genuinely larger payout, but part reflects a weak share price — the stock is down roughly 7-9% over the last year and trades near its 52-week low (52-week range ~₹138-₹204). A high yield driven partly by a falling price is not the same as a high yield driven by business strength. (External: NSE/aggregator price data.)
CESC Limited Dividend History (Last 10 Years)
Split-adjusted dividend per share (CESC executed a 10-for-1 stock split effective September 2021; earlier per-share figures below are adjusted to the current Re 1 face value for comparability). (External: exchange/aggregator dividend records.)
| Financial Year | Dividend/Share (₹) | Trend |
|---|---|---|
| FY27 (interim, so far) | 6.00 | Maintained / earlier in year |
| FY26 | 6.00 | Step-up ↑ |
| FY25 | 4.50 | Stable |
| FY24 | 4.50 | Stable |
| FY23 | 4.50 | Stable |
| FY22 | 4.50 | Stable |
| FY21 | 4.50 | Step-up ↑ |
| FY20 | 2.00 | Rising |
| FY19 | 1.75 | Rising |
| FY18 | 1.20 | Rising |
| FY17 | 1.00 | Base |
Consistency & Growth
Over the last decade CESC has shown a steadily rising, uninterrupted dividend — from ₹1.00 (FY17) to ₹6.00 (FY26), with no cuts or suspensions. Independent trackers report ~12% long-run dividend growth and a roughly 167% rise in dividend per share over five years. (External: Simply Wall St / Alpha Spread.)
Classification
Based on this record, CESC Limited screens as a Consistent Dividend Payer with a growing trend, typical of a regulated utility with stable, tariff-linked cash flows. The FY26-FY27 step-up to ₹6 marks its most generous phase yet.
CESC Limited Financial Performance Analysis (Q1 FY27)
Consolidated results for the quarter ended 30 June 2026 vs the same quarter last year (₹ crore). Consolidated figures capture the full group including distribution franchises and the renewable arm.
| Particulars (Consolidated) | Q1 FY27 | Q1 FY26 | Change |
|---|---|---|---|
| Revenue from operations | 5,485 | 5,202 | +5.4% |
| Total income | 5,559 | 5,285 | +5.2% |
| Profit before tax | 546 | 512 | +6.6% |
| Net profit (total) | 419 | 407 | +2.9% |
| Profit — owners of parent | 402 | 390 | +3.1% |
| EPS (₹, not annualised) | 3.03 | 2.94 | +3.1% |
Operating Leverage: revenue up, profit up less
Consolidated revenue rose +5.4% but net profit grew only +2.9%. The gap is explained mainly by (a) a lower "regulatory income" contribution (₹180 cr vs ₹233 cr a year ago) and (b) employee cost up ~13% (₹407 cr vs ₹359 cr) and cost of energy purchased up ~7%. This was partly cushioned by lower finance costs (₹312 cr vs ₹363 cr). Standalone operating profit margin eased to 15.0% from 15.8% — mild margin compression rather than a collapse.
Sequential dip & FY26 base
Consolidated net profit fell from ₹459 cr (Q4 FY26) to ₹419 cr (Q1 FY27), largely a swing in regulatory income (which was unusually high in Q4). For the full year FY26, the group posted revenue of ₹18,570 cr, net profit of ₹1,618 cr (₹1,542 cr to owners) and EPS of ₹11.63. Standalone FY26 net profit was ₹852 cr (EPS ₹6.43).
CESC Limited Cash Flow & Dividend Funding Analysis
How is the ₹798 crore dividend funded?
The Q1 results filing does not include a cash flow statement, so operating cash flow (OCF) and free cash flow (FCF) for the quarter are Not Disclosed by Company. What we can say: the full FY27 interim outflow of ~₹798 crore is roughly 1.9x the group's single-quarter profit of ₹419 cr — so it is clearly funded from full-year earnings plus accumulated reserves, not a single quarter.
Reserve & cash-flow cushion
Consolidated "Other Equity" (reserves) stood at ₹12,397 crore at FY26-end — ample cover for an ~₹798 cr distribution. Independent data pegs CESC's cash payout ratio at ~73%, i.e. the dividend is covered by cash flows but with a moderate margin. (External: Simply Wall St.)
Watch-point: For a capital-intensive utility funding a large renewable build-out, a ~73% cash payout leaves less internally-generated cash for capex and debt reduction. Actual OCF and FCF cover should be verified from the FY27 annual cash flow statement when published. Cash & investments, FCF and net debt (precise) are Not Disclosed by Company in this filing.
CESC Limited Balance Sheet Strength
What the numbers say
CESC carries moderate-to-high leverage (D/E ~1.0), and independent sources note total debt of roughly ₹11,565 cr, up materially year-on-year as the group invests in renewables and distribution. Interest coverage of 2.9x is adequate but not comfortable. The filing also flags that net working capital is negative (current ratio ~0.4) — common for utilities that bill consumers monthly, but a factor to monitor. As on 30 June 2026 the company had ₹600 cr of listed commercial paper outstanding. (Debt figure external: Orunodoi; other figures from company filing.)
CESC Limited Dividend Sustainability Analysis
Coverage: consolidated vs standalone
This is the crucial distinction. On a consolidated basis, FY26 EPS of ₹11.63 covers the ₹6 payout 1.9x (payout ~52%) — healthy. But the dividend is legally paid by the parent (standalone), whose FY26 EPS was only ₹6.43 — a coverage of just ~1.07x and a standalone payout near 93%. In other words, the parent leans on dividends/cash from subsidiaries and reserves to fund the payout.
Verdict
Weighing regulated, predictable cash flows and deep reserves (positive) against high standalone payout, rising debt and a heavy capex cycle (cautionary), we classify the CESC Limited dividend as Moderately Sustainable — well-supported at the group level, but with limited standalone headroom if subsidiary cash flows or regulatory income weaken.
~52%
Payout (consolidated)
~93%
Payout (standalone)
1.9x
EPS cover (consol.)
~73%
Cash payout ratio
CESC Limited Dividend vs Power-Sector Peers
Approximate 2026 dividend yields across listed power utilities. Figures are indicative and move with price. (External: aggregator data — wisesheets / univest / Simply Wall St.)
| Company | Approx. Dividend Yield | Character |
|---|---|---|
| CESC Limited | ~4.1% (single) / ~8% TTM | High yield, higher leverage |
| Power Grid | ~3.1-4.2% | Regulated T&D, high ROE |
| NTPC | ~2.2-2.7% | Govt-backed, largest generator |
| Torrent Power | ~1.5% | Integrated utility |
| Tata Power | ~0.7% | Growth/renewables premium |
| JSW Energy | ~0.4% | Capacity-expansion play |
| Sector average (Electric Utilities) | ~2.4% | Benchmark |
CESC screens as the highest-yielding name in this peer set. That reflects both a genuinely larger payout policy and a soft share price. However, on return ratios — ROE ~8-12% and ROCE ~10% — CESC trails higher-quality regulated peers like Power Grid (ROE ~16%). So it is an income name first, a quality-compounder second. (External: aggregator ROE/ROCE data.)
CESC Limited Promoter & Shareholder Impact Analysis
Estimated distribution of the ~₹798 cr outflow by shareholder group (June 2026 pattern). (External: shareholding data — Dhan/Kotak, June 2026.)
Reading the distribution
The single largest beneficiary is the promoter group, which collects an estimated ₹416 crore from this interim. High promoter ownership (a stable 52.11%) means dividends are a meaningful cash-return channel for the controlling group — this can align interests (promoters want steady payouts) but also means minority holders should watch that dividends are funded from genuine surplus, not by starving growth or adding debt. Retail investors, at ~10.3%, share ~₹82 crore of the pool.
CESC Limited Dividend Taxation Analysis
How dividends are taxed in India
Since FY2020-21, dividends are taxable in the hands of investors at their applicable income-tax slab rate (no Dividend Distribution Tax). For resident individuals, the company deducts TDS at 10% under Section 194 if the total dividend from that company exceeds ₹10,000 in a financial year (threshold raised by the Finance Act 2025); TDS is 20% if PAN is not provided. For NRIs, TDS is generally 20% (plus surcharge and cess) under Section 195, subject to DTAA. TDS is a credit against final tax, not an extra cost.
Worked example (₹6 dividend)
Investor holds 2,000 CESC shares; income-tax slab = 30%.
Pre-tax yield on this ₹6 interim was ~4.1%. A holder in a lower slab (e.g. 5-20%) keeps more; those below the ₹10,000 threshold face no TDS.
Key Risks for CESC Limited Dividend Investors
1. Regulatory / tariff risk
Revenue and "regulatory income" depend on West Bengal Electricity Regulatory Commission (WBERC) tariff orders and FPPAS pass-throughs. The filing notes several APR/true-up matters under appeal — adverse rulings could dent earnings and payout capacity.
2. High and rising leverage
Consolidated debt of ~₹11,565 cr and D/E ~1.0, rising with capex. Interest coverage of 2.9x leaves limited room if rates rise or cash flows slip.
3. Thin standalone payout headroom
Standalone payout near 93% means the parent depends on subsidiary cash and reserves; a slowdown there pressures dividends.
4. Renewable capex execution
The group is scaling a large solar/wind pipeline via Purvah Green Power and recent ReNew asset acquisitions — heavy investment competes with cash available for dividends.
5. Fuel cost & input inflation
Cost of energy purchased and fuel are large line items; coal/power-price spikes not fully passed through can compress margins.
What to Monitor in CESC Limited Going Forward
1. Full-year FY27 dividend
Whether CESC declares a further FY27 dividend after this ₹6 interim — this decides the true annual yield (₹6 vs ₹12+).
2. Operating cash flow & FCF cover
Track OCF vs net profit and FCF in the FY27 annual report to confirm dividends are paid from cash, not just reserves.
3. Net debt trajectory
Whether debt keeps rising with capex, and interest coverage direction.
4. Regulatory income & WBERC orders
The size and consistency of regulatory income, and outcomes of pending APR/true-up appeals.
5. Renewable commissioning & distribution wins
MW commissioned vs planned (Purvah Green Power) and new distribution circles — the growth engine behind future payouts.
Conclusion – CESC Limited Dividend Outlook
CESC Limited's ₹6 interim dividend for FY27 continues a clear, decade-long trend of rising, uninterrupted payouts and cements its status as one of the highest-yielding names in the Indian power sector. The distribution is well-covered at the consolidated level (1.9x) and backed by ~₹12,400 cr of reserves and stable regulated cash flows.
The honest caveats: the headline yield is flattered by a weak share price; standalone payout headroom is thin (~93%); and leverage is rising during a heavy renewable capex cycle. That is why we rate the dividend Moderately Sustainable rather than bullet-proof. Income investors get an attractive, consistent yield; growth-focused investors should weigh the modest ROE and debt. We present the positives, negatives and risks — the decision is yours.
Frequently Asked Questions About CESC Limited Dividend
What dividend has CESC Limited announced in 2026?
What is the CESC Limited dividend yield?
What is the record date for the CESC Limited dividend?
What is the CESC Limited ex-dividend date?
When will the CESC Limited dividend be paid?
Who is eligible for the CESC Limited dividend?
How is the CESC Limited dividend taxed?
Is the CESC Limited dividend sustainable?
What is the CESC Limited dividend history?
How much dividend income will CESC's promoters receive?
What should investors monitor after the CESC Limited dividend?
What was CESC's Q1 FY27 profit?
Disclaimer
This article is for informational and educational purposes only and does not constitute investment, financial, legal or tax advice, nor a recommendation to buy, sell or hold any security. Figures marked as external are sourced from publicly available third-party data (exchange filings, aggregators) and may differ from live values; company figures are from CESC Limited's 13 August 2026 board outcome and Q1 FY27 results. Share prices, yields and ratios change continuously — verify all data on nseindia.com, bseindia.com or the company's filings before acting. Dividend amounts, dates and eligibility are subject to statutory and corporate processes. ShareBazaar Online and the author are not liable for any loss arising from reliance on this content. Please consult a SEBI-registered investment adviser and a qualified tax professional for guidance specific to your situation.