
Dividend Snapshot – Jullundur Motor Agency (Delhi) Limited
Yield computed on latest available NSE price of ~₹90.56 (indmoney, 2 Sep 2026). Dividend outflow and payout ratio computed by ShareBazaar Online from the company's audited FY26 results and 22,84,10,00... share base (see calculations below).
Jullundur Motor Agency Dividend Announcement Summary
At its board meeting on 28 May 2026 (Serial No. 1 for FY 2026-27), the Board of Directors of Jullundur Motor Agency (Delhi) Limited recommended a final dividend of ₹3 per equity share of ₹2 each — including a special dividend of ₹1 per share — i.e. 150% (100% normal + 50% special) for the financial year ended 31 March 2026. The same meeting approved the audited standalone and consolidated results for Q4 and FY26 (unmodified audit opinion from Aiyar & Co., Chartered Accountants), recommended the appointment of Shri Varoon Malik as Managing Director for five years from 1 September 2026, and resolved to convene the 77th AGM on 25 August 2026 via video conferencing.
The special dividend is the standout feature. Jullundur Motor Agency has paid a steady ₹2 final dividend for five consecutive years (FY22–FY26); the extra ₹1 special dividend is the first top-up in that run and lifts the FY26 payout by 50% over the recent norm. Payment, if declared at the AGM, will be made on or before 23 September 2026, within 30 days of the conclusion of the AGM.
Jullundur Motor Agency Dividend Record Date and Ex-Dividend Date
Ex-date and record date sourced from exchange/registrar data (INDmoney, Groww). To be eligible for the Jullundur Motor Agency dividend, shares must have been held before the ex-date of 18 Aug 2026; under T+1 settlement, buying on the ex-date itself does not qualify.
Jullundur Motor Agency Dividend Yield
Yield at Latest Price
Yield at Announcement
Yield Reality Check
The ~3.3% Jullundur Motor Agency dividend yield is genuinely dividend-driven, not a distress signal. It is not the product of a collapsing share price — the stock has traded in a fairly narrow ₹70–104 band over the past year. Instead, roughly one-third of the yield (the ₹1 special dividend, ~1.1 percentage points) is a one-time top-up. Stripping out the special dividend, the recurring yield on the ₹2 final dividend is closer to ~2.2%. Investors should therefore treat 3.3% as an FY26-specific figure that may not repeat unless the company continues special dividends. Prices: NSE via indmoney/Groww/BusinessToday.
Jullundur Motor Agency Dividend History
| Financial Year | Type | ₹/Share (as paid) | Face Value | Split-Adjusted (₹2 base) |
|---|---|---|---|---|
| FY 2025-26 | Final + Special | ₹3.00 | ₹2 | ₹3.00 |
| FY 2024-25 | Final | ₹2.00 | ₹2 | ₹2.00 |
| FY 2023-24 | Final | ₹2.00 | ₹2 | ₹2.00 |
| FY 2022-23 | Final | ₹2.00 | ₹2 | ₹2.00 |
| FY 2021-22 | Final | ₹2.00 | ₹2 | ₹2.00 |
| FY 2020-21 | Final | ₹1.00 | ₹2 | ₹1.00 |
| FY 2019-20 | Final | ₹1.00 | ₹2 | ₹1.00 |
| FY 2018-19 | Interim | ₹4.00 | ₹10* | ~₹0.80 |
| FY 2017-18 | Final | ₹4.00 | ₹10* | ~₹0.80 |
| FY 2016-17 | Interim | ₹4.00 | ₹10* | ~₹0.80 |
| FY 2015-16 | Interim | ₹4.00 | ₹10* | ~₹0.80 |
*Shares carried a ₹10 face value until the 2019 voluntary sub-division into five ₹2 shares (5:1). Split-adjusted column restates older dividends onto the current ₹2 base for like-for-like comparison. History sourced from INDmoney / Simply Wall St / TipRanks.
Consistency Verdict: Consistent Payer
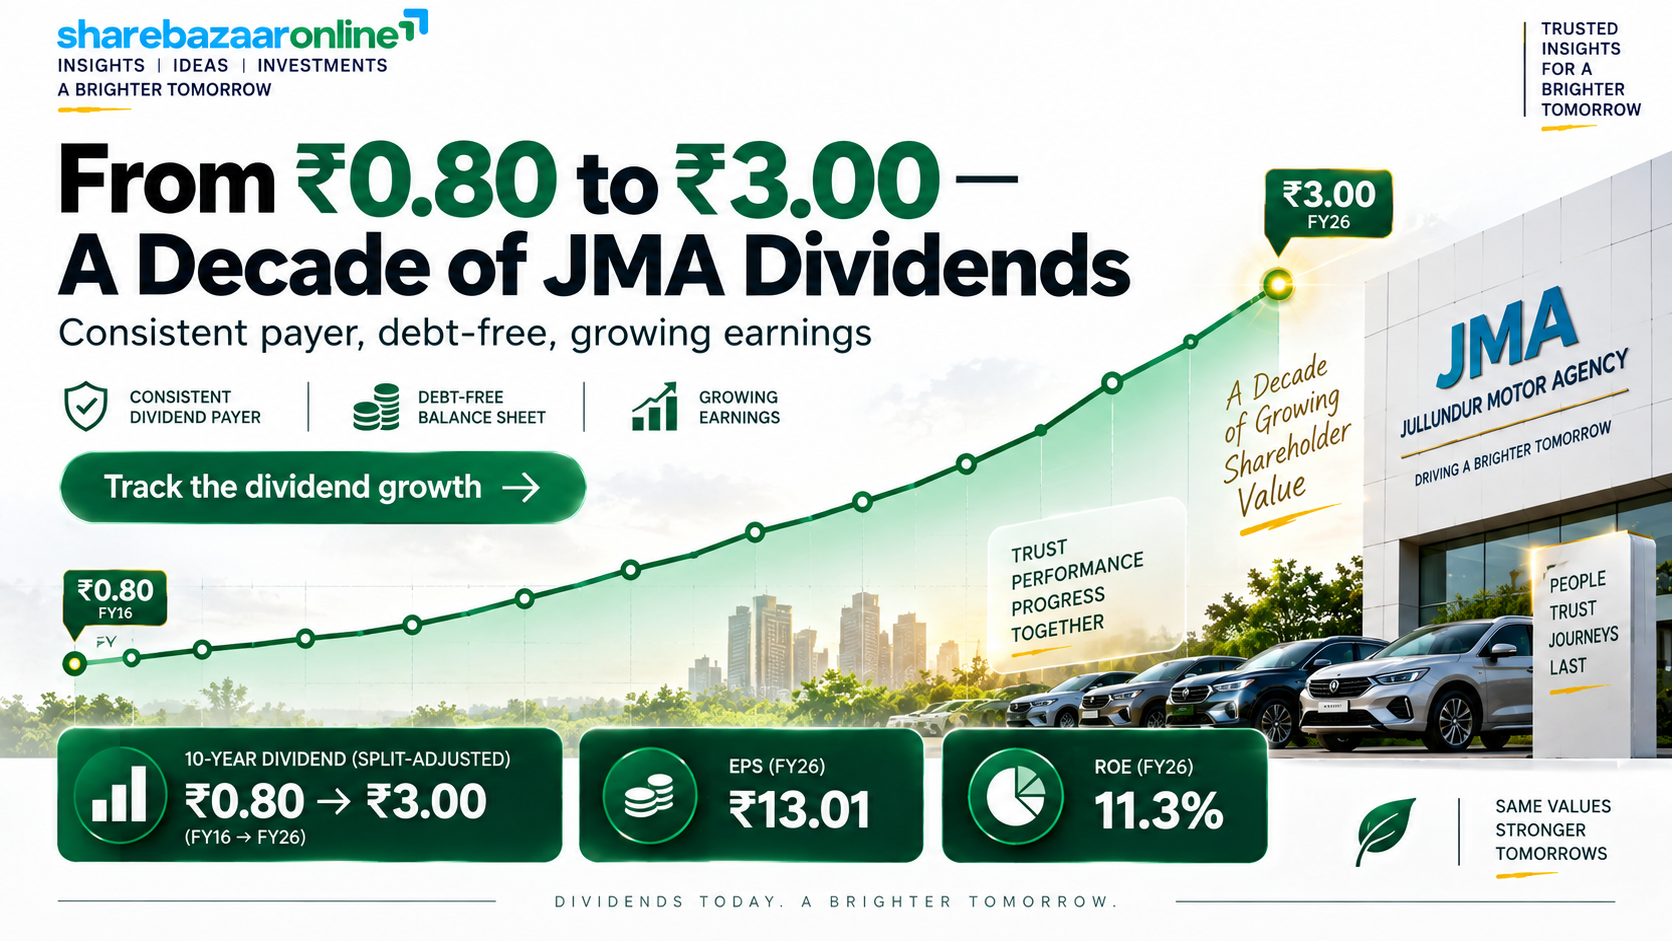
On a split-adjusted basis, the Jullundur Motor Agency dividend has grown from ~₹0.80 (FY16) to ₹3.00 (FY26) — an uninterrupted record with no cuts and no suspensions across at least 10 years, including through the FY20–FY21 pandemic period (when it still paid ₹1). The pattern shifted from occasional interim dividends (pre-2019) to a predictable annual final dividend, now topped up by a special dividend in FY26. This qualifies JMA as a consistent dividend payer, though the FY26 special dividend is not yet an established recurring feature.
Jullundur Motor Agency Dividend vs Profit Growth
Consolidated Operating Leverage (FY26 vs FY25)
| Metric | FY26 | FY25 | Growth |
|---|---|---|---|
| Revenue from Operations | ₹621.90 cr | ₹555.72 cr | +11.91% |
| EBITDA (PBT + Depreciation) | ₹41.40 cr | ₹36.65 cr | +12.95% |
| Profit Before Tax | ₹40.41 cr | ₹35.61 cr | +13.46% |
| Net Profit (Owners) | ₹29.71 cr | ₹25.75 cr | +15.38% |
| EPS (Basic, Consolidated) | ₹13.01 | ₹11.27 | +15.44% |
Healthy Operating Leverage
Jullundur Motor Agency shows positive operating leverage: profit is growing faster than revenue at every level. Revenue rose +11.91%, but PBT rose +13.46% and net profit to owners rose +15.38% — the opposite of margin compression. As a low-margin auto-parts distributor (net margin ~4.8%), JMA runs a high-volume, thin-spread model, so even a small margin gain amplifies profit. On a standalone basis the effect is stronger still: revenue +11.51% drove net profit up +20.51% (to ₹24.51 cr; EPS ₹10.73). There is no revenue-up-profit-down problem here.
Jullundur Motor Agency Cash Flow & Dividend Funding
Consolidated Cash Flow
Dividend Funding Test
Cash Is Fact: The FY25 Warning, and the FY26 Recovery
This is where Jullundur Motor Agency needs a close read. In FY25, consolidated operating cash flow was negative (–₹2.01 cr) even though the company reported a ₹25.75 cr profit — cash was trapped in working capital (inventory and receivables). That is exactly the kind of profit-vs-cash gap that reporting-only sites skip over. In FY26 the picture reversed sharply: a ₹19.86 cr reduction in trade payables was more than offset by cash released from receivables (₹2.40 cr) and inventory (₹4.07 cr), lifting cash generated from operations to ₹21.80 cr and operating cash flow (after ₹10.38 cr tax) to ₹11.42 cr.
With capex of just ₹0.68 cr (JMA is asset-light — it distributes, it doesn't manufacture at scale), free cash flow was ₹10.74 cr, comfortably covering the ₹6.85 cr dividend 1.57 times over from current-year cash alone. The FY26 dividend is therefore funded by current earnings and operating cash — not by borrowings or asset sales. The one caveat: FY25's negative OCF shows this cash generation can be lumpy year to year because working capital swings are large in a distribution business.
Receivables vs Revenue — A Positive Signal
Encouragingly, trade receivables fell 2.48% (to ₹94.37 cr) even as revenue grew 11.91%, and inventory fell 3.93%. Growing sales while shrinking receivables and stock is a sign of improving working-capital discipline — the collections engine is keeping pace with, and slightly ahead of, the top line.
Jullundur Motor Agency Balance Sheet Strength
Jullundur Motor Agency runs a debt-free balance sheet — the audited FY26 statements show no borrowings at all, only trade payables and a small deferred-tax liability. Against the ₹6.85 cr dividend, the company holds ₹22.89 cr in immediately liquid assets (cash, bank balances and current investments), rising to roughly ₹82 cr once longer-dated bank deposits and non-current investments are included. That is cash coverage of 3.3x on a narrow basis and ~12x on a broad basis. Return ratios are moderate — ROE ~11.3% and ROCE ~12% (Screener) — reflecting the thin margins of distribution, but the near-zero financial risk is a genuine strength for a dividend investor.
Net debt: the company is net-cash positive; borrowings are "Not Disclosed" because none exist on the balance sheet. ROE/ROCE cited from Screener.in.
Jullundur Motor Agency Dividend Sustainability
Sustainability Scorecard
Verdict
The recurring ₹2 final dividend is well protected. The ₹1 special dividend is moderately sustainable — affordable, but discretionary and not guaranteed to repeat.
On the four sustainability tests, Jullundur Motor Agency scores well. Earnings cover: consolidated EPS of ₹13.01 covers the ₹3 dividend 4.3 times. Cash cover: FCF covers it 1.57x. Payout ratio: a conservative ~23% of consolidated profit (~28% of standalone profit) leaves ample room. Debt: none — the company is not paying dividends while leverage rises. The only amber flag is the lumpy cash generation (negative OCF in FY25) and the fact that the headline 150% payout leans partly on a one-off special dividend. Base case: the ₹2 recurring dividend looks firmly sustainable; the special dividend should be treated as a bonus, not a baseline.
Jullundur Motor Agency vs Auto-Component Peers
| Company | Div. Yield | ROE | Notes |
|---|---|---|---|
| Jullundur Motor Agency | ~3.3% | ~11.3% | Debt-free distributor; incl. special div |
| India Nippon Electricals | ~1.3% | ~13.5% | Higher ROE, lower yield |
| Bosch India | ~1.2% | high | Large-cap OEM supplier |
| GNA Axles | ~0.6% | ~11.6% | Manufacturer, reinvests more |
| Rico Auto | ~0.3% | ~6.5% | Low yield |
| Talbros Automotive | ~0.2% | ~14.0% | Growth-focused, minimal payout |
Peer figures from Motilal Oswal / TipRanks peer screens (Sep 2026); approximate and subject to price moves.
On dividend yield, Jullundur Motor Agency stands out clearly. Most listed auto-component names yield well under 1.5%, because manufacturers plough cash back into capacity. JMA's ~3.3% (helped by the special dividend) is roughly 2–3x the sector norm. The trade-off is visible in the return ratios: JMA's ROE of ~11.3% is middling — peers like Talbros (~14%) and India Nippon (~13.5%) earn more on equity but return far less of it. In short, JMA is a higher-payout, lower-growth profile: attractive for income, less so for capital compounding.
Jullundur Motor Agency Promoter Impact Analysis
With promoters holding 51%, roughly ₹3.49 crore of the ₹6.85 crore Jullundur Motor Agency dividend flows to the promoter family, and about ₹3.36 crore to public and minority shareholders. Institutional ownership is negligible (FII 0.05%, DII 0.01%), so this is essentially a promoter-and-retail register. Because dividends are shared pro-rata and equally per share, minority holders receive exactly the same ₹3 per share as promoters — there is no structural disadvantage. It is worth noting, however, that a debt-free, cash-rich company with a controlling family and near-zero institutional oversight has a natural incentive toward generous dividends (including special dividends) as a tax-efficient route to distribute surplus cash to insiders.
Jullundur Motor Agency Dividend Taxation
Since April 2020, dividends in India are taxed in the hands of the shareholder at their applicable income-tax slab rate (added to "Income from Other Sources"). The company deducts TDS at 10% under Section 194 only if a resident shareholder's total dividend from the company exceeds ₹10,000 in a financial year (20% if PAN is not provided). NRIs face 20% TDS, subject to DTAA relief. TDS is a credit, adjustable against final tax liability at filing.
Worked Example — 1,000 Shares of Jullundur Motor Agency
| Item | 5% Slab | 20% Slab | 30% Slab |
|---|---|---|---|
| Gross Dividend (1,000 × ₹3) | ₹3,000 | ₹3,000 | ₹3,000 |
| TDS (Sec 194) | Nil* | Nil* | Nil* |
| Tax at Slab | ₹150 | ₹600 | ₹900 |
| Net Dividend | ₹2,850 | ₹2,400 | ₹2,100 |
| Effective Post-Tax Yield | ~3.15% | ~2.65% | ~2.32% |
*TDS is nil because ₹3,000 is below the ₹10,000 Section 194 threshold. Effective yield computed on CMP ~₹90.56. Illustration only — consult a tax advisor; surcharge/cess may apply at higher incomes.
Key Risks for Jullundur Motor Agency Shareholders
1. Special Dividend May Not Repeat
Roughly a third of the FY26 yield is the one-off ₹1 special dividend. If it is not repeated, the forward yield drops toward ~2.2%.
2. Thin Distribution Margins
Net margin is only ~4.8%. As a spare-parts distributor, JMA has limited pricing power; input-cost or competitive pressure can squeeze already-thin profits quickly.
3. Lumpy Operating Cash Flow
Consolidated OCF was negative (–₹2.01 cr) in FY25 before recovering in FY26. Large working-capital swings make cash generation unpredictable year to year.
4. Auto-Sector Cyclicality
Demand for aftermarket parts tracks vehicle usage and the economy. A slowdown in the auto cycle would directly hit volumes and dividend capacity.
5. Low Liquidity & No Institutional Cover
FII+DII holding is ~0.06% and daily volumes are small. Thin liquidity means volatile pricing and little independent analyst scrutiny.
6. EV Transition & Modest ROE
A long-term shift to EVs (fewer moving parts) could reshape the ICE-parts aftermarket, while ROE of ~11% offers limited capital-compounding cushion.
What to Monitor in Jullundur Motor Agency
1. Repeat of Special Dividend
Watch FY27 to see whether the ₹1 special dividend becomes a recurring feature or was a one-time distribution of surplus cash.
2. Operating Cash Flow Trend
Track whether OCF stays positive and converges toward reported profit — the single best test of dividend durability here.
3. Working-Capital Cycle
Monitor receivable days and inventory days; the FY26 improvement must hold for cash generation to remain healthy.
4. Revenue & Margin Direction
Watch whether double-digit revenue growth and the positive operating leverage (profit growing faster than sales) continue.
5. Payout Ratio Discipline
A payout climbing well above ~40% of profit without matching cash flow would be an early warning; today's ~23% is comfortable.
6. New MD Capital Allocation
Track how incoming MD Varoon Malik deploys the large cash pile — between dividends, growth capex, and any buyback.
Jullundur Motor Agency Dividend Outlook
Positives
The FY26 Jullundur Motor Agency dividend of ₹3 per share is backed by cash, not just accounting profit: free cash flow of ₹10.74 cr covers the ₹6.85 cr outflow 1.57x, the payout ratio is a conservative ~23%, earnings cover the dividend 4.3x, and the company is completely debt-free with ~₹82 cr of liquid resources. Profit is growing faster than revenue (positive operating leverage), receivables are shrinking while sales rise, and the ~3.3% yield is well above the sub-1.5% auto-component sector norm. The dividend record is unbroken for a decade.
Negatives & Watch-outs
Against that, about one-third of the headline yield is a one-off special dividend that may not recur; cash flow is lumpy (negative OCF as recently as FY25); margins are thin (~4.8%) and ROE modest (~11%); and the stock is illiquid with almost no institutional coverage. This is an income-oriented, low-growth profile rather than a compounder. Readers should weigh the reliable ₹2 base dividend separately from the discretionary special top-up, and decide for themselves based on the positives, negatives, risks and monitoring factors set out above.
Frequently Asked Questions About Jullundur Motor Agency Dividend
What dividend has Jullundur Motor Agency announced for FY26?
What is the Jullundur Motor Agency dividend yield?
What is the record date for the Jullundur Motor Agency dividend?
What is the ex-dividend date for JMA?
When will the Jullundur Motor Agency dividend be paid?
Who is eligible for the Jullundur Motor Agency dividend?
How is the Jullundur Motor Agency dividend taxed?
Is the Jullundur Motor Agency dividend sustainable?
What is the Jullundur Motor Agency dividend history?
What is the total dividend outflow and how is it funded?
How much dividend do promoters receive?
Why is the FY26 yield higher than usual?
What should investors monitor going forward?
Is Jullundur Motor Agency debt-free?
Disclaimer
This article is prepared by ShareBazaar Online for informational and educational purposes only and does not constitute investment, financial, or tax advice, nor any buy, sell or hold recommendation. Dividend figures, dates, share capital and financial data are drawn from Jullundur Motor Agency (Delhi) Limited's board outcome dated 28 May 2026 and its audited FY26 results; market prices, yields, shareholding, ROE/ROCE and peer data are sourced from public providers (NSE, Screener, INDmoney, Groww, Motilal Oswal, TipRanks, Simply Wall St) as cited and are approximate and subject to change. All ratios (yield, payout, coverage, outflow) are ShareBazaar Online's own calculations and may differ from other sources depending on the profit base used. Share prices and dividends are subject to market and business risk. Please verify all details independently and consult a SEBI-registered adviser and a qualified tax professional before making any investment decision. ShareBazaar Online accepts no liability for actions taken based on this content.