
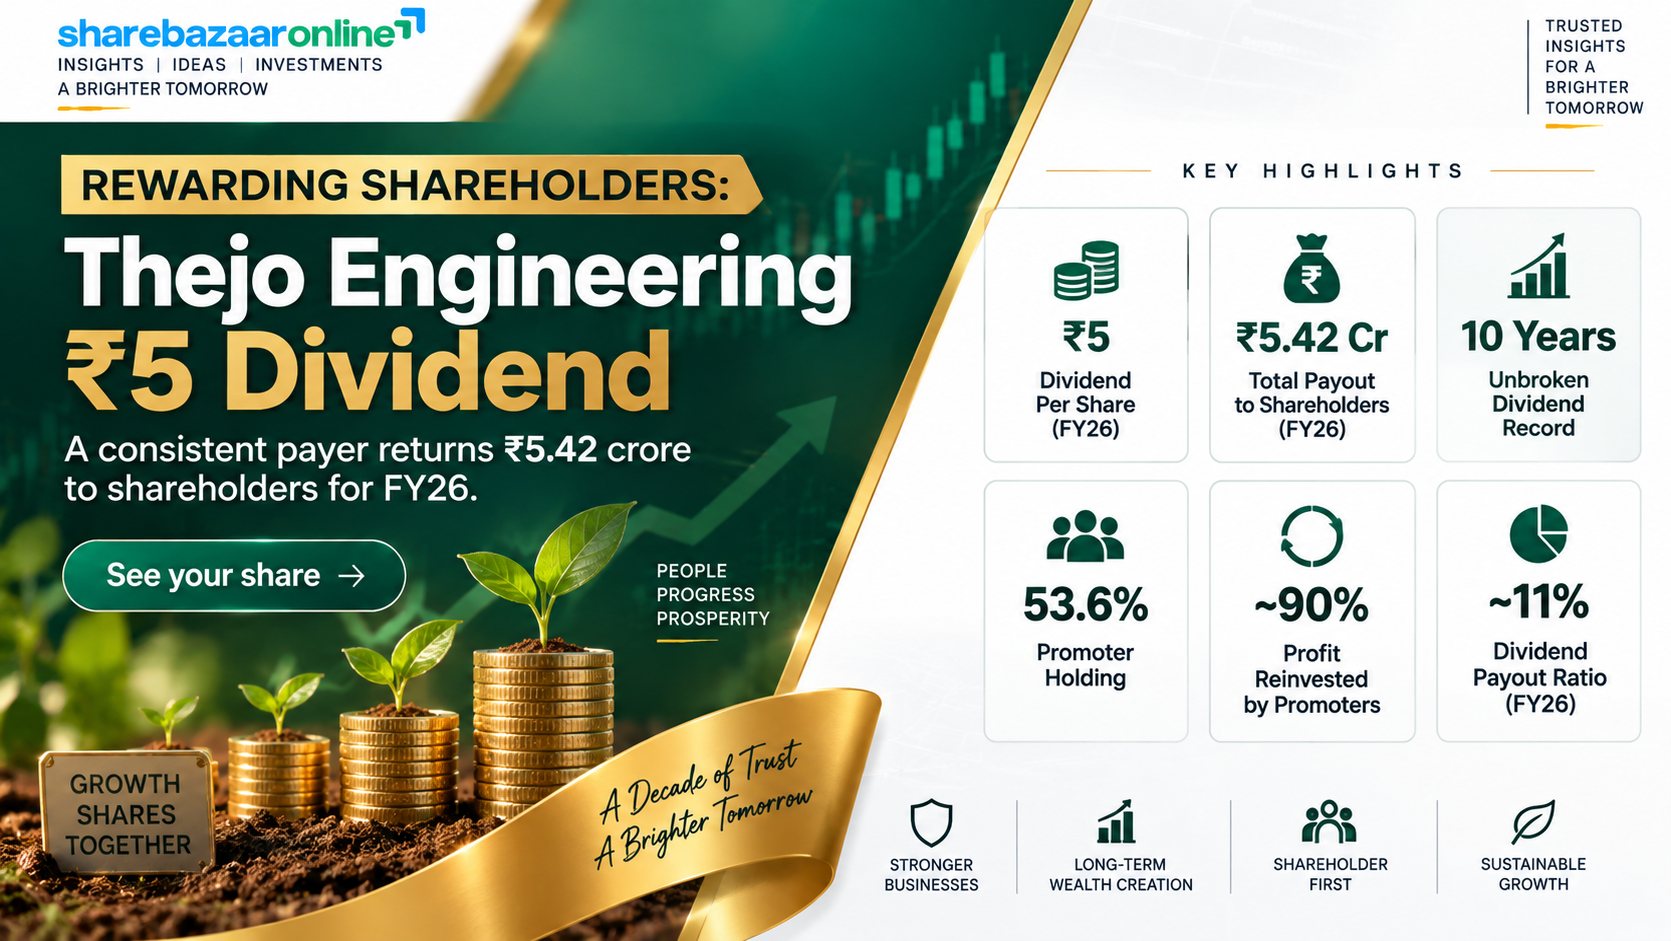
Dividend Snapshot – Thejo Engineering Limited
The Board of Thejo Engineering Limited (NSE: THEJO | ISIN: INE121N01019) has recommended a final dividend of ₹5 per equity share (a dividend of 50% on the face value of ₹10) for the financial year ended 31 March 2026 (FY26). The Thejo Engineering dividend was announced on 27 May 2026 and is subject to shareholder approval at the Annual General Meeting. This dividend snapshot for Thejo Engineering Limited summarises every number an investor needs before the record date.
Dividend Details
- Dividend Per Share: ₹5.00
- Dividend Rate: 50% of face value
- Face Value: ₹10 per share
- Dividend Type: Final Dividend
- Financial Year: FY2025–26
Yield & Payout
- Dividend Yield (latest): 0.23%
- Yield on Announcement Date: 0.31%
- Dividend Payout Ratio: ~11% (consolidated)
- Total Dividend Outflow: ₹5.42 crore
- Dividend Coverage: 9.1x (consolidated EPS)
Market data: NSE / Screener.in as on 15 September 2026. Dividend yield = Dividend Per Share ÷ Current Market Price.
Dividend Announcement Summary – Thejo Engineering Limited
At its meeting held on 27 May 2026, the Board of Directors of Thejo Engineering Limited approved the audited standalone and consolidated financial results for FY26 and recommended a final dividend of ₹5 per share. The company’s statutory auditors, M/s Brahmayya & Co., issued an unmodified (clean) opinion on the results.
Because this is a final dividend, it must be approved by members at the 40th Annual General Meeting before it becomes payable. Thejo Engineering fixed 18 August 2026 as the record date and a book-closure period of 19–25 August 2026. The company is listed only on the NSE (symbol THEJO); it does not have a separate BSE scrip code. CIN: L27209TN1986PLC012833.
Management context: Thejo Engineering is a 40-year-old engineering solutions provider for bulk material handling, mineral processing and corrosion protection, serving mining, steel, cement, power and ports. It runs a “Products, Services and O&M” model with 2,300+ employees and 600+ customers. The FY26 dividend continues a modest but rising payout that the company has maintained through its transition from an SME-listed firm to a mainboard small-cap.
Key Dates Timeline – Thejo Engineering Limited
Announcement Date
27 May 2026 — Board recommended the dividend along with FY26 audited results.
Record Date
18 August 2026 — shareholders on the register on this date are eligible.
Ex-Dividend Date
18 August 2026 — buy before this date to qualify for the Thejo Engineering dividend.
Book Closure & AGM
Book closure 19–25 Aug 2026; 40th AGM held 25 August 2026.
Payment Date
Not Disclosed by Company in the filing. Statutorily, an approved dividend is paid within 30 days of the AGM (i.e., by late September 2026).
Cut-off Date (AGM voting)
18 August 2026 — eligibility for e-voting at the 40th AGM.
Thejo Engineering Limited Dividend Yield Analysis
The Thejo Engineering dividend yield is deliberately low. At the latest market price of ₹2,186 (Screener.in, 15 Sep 2026), a ₹5 dividend gives a yield of just 0.23%. On the announcement-date price of ₹1,615.50 (NSE, 27 May 2026), the yield was 0.31%.
Yield reality check: The low yield is not a warning sign of a weak dividend. It is the mathematical result of a high share price relative to a small, conservative payout. Thejo trades at a P/E of roughly 41x (Screener.in) — a growth-stock valuation — while paying out only about 11% of profit. In other words, the market values Thejo for capital appreciation and reinvestment, not for dividend income. A rising share price mechanically pushes the yield down even when the rupee dividend is growing.
Yield at Different Prices
- At ₹1,615.50 (announcement): 0.31%
- At ₹2,186 (latest): 0.23%
- At 52-week low ₹1,443.60: 0.35%
- At 52-week high ₹2,286.60: 0.22%
What the Yield Signals
Thejo is a growth-and-reinvestment stock, not a high-yield income stock. Investors are rewarded primarily through share-price appreciation; the dividend is a small, symbolic top-up rather than a core reason to own the stock.
Thejo Engineering Limited Dividend History
Thejo Engineering has a consistent, growing dividend record. The dividend has risen from around ₹1 per share in the FY17 era to ₹5 in FY25 and FY26. The company pays once a year (a single final dividend) and has not skipped a payment or declared a special dividend in recent years.
| Financial Year | Dividend Per Share | Payout Ratio* |
|---|---|---|
| FY2025–26 | ₹5.00 | ~11% |
| FY2024–25 | ₹5.00 | ~11% |
| FY2023–24 | ₹3.00 | ~6% |
| FY2022–23 | ₹2.00 | ~7% |
| FY2021–22 | ~₹2.00 (est.) | ~6% |
| FY2020–21 | ~₹2.00 (est.) | ~8% |
| FY2019–20 | ~₹1.50 (est.) | ~7% |
| FY2018–19 | ~₹1.50 (est.) | ~13% |
| FY2017–18 | ~₹1.25 (est.) | ~12% |
| FY2016–17 | ~₹1.00 (est.) | ~21% |
*Payout ratios sourced from Screener.in (consolidated). Dividend-per-share figures for FY24–FY26 are confirmed; SME-era figures marked “est.” are approximated from the reported payout ratio and should be verified against the respective annual reports. Per-share values are adjusted to the current ₹10 face value.
Payer Classification
Consistent Payer. Thejo has paid an uninterrupted annual dividend that has grown broadly in line with profits — from ~₹1 to ₹5 over roughly a decade. No cuts, no suspensions, no one-off special dividends.
Growth Trend
Dividend held flat at ₹5 for two straight years (FY25 and FY26) after a jump from ₹3 in FY24. The pause in growth mirrors FY26’s flat profit — a sign the payout tracks earnings rather than outrunning them.
Thejo Engineering Limited Financial Performance Analysis
Revenue grew, but profit did not. This is the single most important operating story in Thejo Engineering’s FY26 results, and it directly affects the dividend’s room to grow.
| Metric | FY26 | FY25 | Change |
|---|---|---|---|
| Revenue from Operations | ₹632.09 cr | ₹552.74 cr | +14.4% |
| Operating Profit (EBITDA)* | ~₹80 cr | ~₹88 cr | −9% |
| Operating Margin (OPM)* | ~13% | ~16% | −3 pts |
| Net Profit (owners) | ₹49.26 cr | ₹49.89 cr | −1.3% |
| Net Profit (total) | ₹48.85 cr | ₹52.31 cr | −6.6% |
| Diluted EPS (consolidated) | ₹45.40 | ₹46.04 | −1.4% |
Source: Company filing (NSE, 27 May 2026). *EBITDA/OPM from Screener.in (consolidated).
Operating Leverage: Why Profit Fell While Sales Rose
Thejo saw negative operating leverage in FY26. Costs grew faster than the top line:
- Revenue: +14.4%
- Employee costs: +18.4% (₹205.6 cr)
- Other expenses: +26.0% (₹221.8 cr)
- Material costs: +9.8%
Because employee and other expenses outran revenue, the operating margin compressed from ~16% to ~13%, and EBITDA fell ~9% even as sales rose.
Two Accounting Items to Note
Highlighted: FY26 profit was shaped by two non-operating items that investors should strip out mentally:
- −₹2.73 cr one-time exceptional charge from the new Labour Codes (higher gratuity/leave-encashment past-service cost).
- +₹5.52 cr non-cash PAT boost (standalone) from switching depreciation from WDV to SLM effective 1 Apr 2025 — lower depreciation, not better operations.
Adjusting for the depreciation change, underlying profit was weaker than the headline suggests.
Standalone vs Consolidated — The Subsidiary Drag
Thejo Engineering’s standalone (parent-only) net profit was ₹55.14 cr, but the consolidated net profit (which includes overseas subsidiaries in Australia, Brazil, Chile and the UAE) was lower at ₹48.85 cr. The gap of about ₹6.3 crore reflects losses at the overseas subsidiaries. Notably, non-controlling (minority) interests bore a net loss for the year, which is why owners’ profit (₹49.26 cr) was slightly higher than total consolidated profit (₹48.85 cr). The dividend, however, is paid by the profitable parent, so this drag does not threaten the payout directly — but it is a genuine profitability headwind worth watching.
Thejo Engineering Limited Cash Flow Analysis
Reported profit is an opinion; cash is a fact. On this test, Thejo Engineering’s FY26 shows some strain worth flagging.
- Operating Cash Flow (OCF): ₹38.94 cr
- Net Profit (total): ₹48.85 cr → OCF/PAT = 0.80x
- Capex (PP&E + intangibles): ₹34.79 cr
- Free Cash Flow (FCF): ₹4.15 cr
- Dividend Outflow: ₹5.42 cr
OCF Below Net Profit — Receivables Are the Reason
Highlighted concern: OCF (₹38.94 cr) converted only 0.80x of net profit into cash. The main culprit is trade receivables, which jumped +29% (to ₹173.4 cr) — twice the pace of the +14.4% revenue growth. Cash generated before working-capital changes was a healthy ₹89.5 cr, but rising debtors and inventory absorbed a large chunk of it. Slower collections are tying up cash.
How Is the Dividend Funded?
Highlighted: In FY26, free cash flow (₹4.15 cr) did not fully cover the dividend (₹5.42 cr) — an FCF coverage of just 0.77x. This was a heavy-capex year. The shortfall is comfortably bridged by the company’s large cash reserves of ₹66.5 cr, so the dividend is funded from a mix of current earnings and existing cash, not from borrowings or asset sales. It is affordable today, but a repeat of sub-1x FCF coverage would be worth watching.
Thejo Engineering Limited Balance Sheet Strength
Thejo Engineering’s balance sheet is a clear strength and the primary reason the dividend is safe. The company is effectively net cash.
- Cash & bank balances (consolidated): ₹66.52 cr
- Total borrowings (ex-lease): ₹5.30 cr
- Lease liabilities: ₹35.53 cr
- Net cash (ex-lease): ₹61.2 cr
- Net cash even after leases: ₹25.7 cr
Returns & Quality
- ROE (FY26): 15.7%
- ROCE (FY26): 19.4%
- 5-year average ROE: ~20%
- Book Value: ₹327 per share
Source: Screener.in. Returns are solid though FY26 dipped from the multi-year average.
Debt vs Dividend
The company is not paying its dividend out of debt. Borrowings are trivial (₹5.3 cr) against ₹66.5 cr of cash. This is the healthiest possible backdrop for a dividend — a net-cash company with strong returns, distributing only a small share of profit.
Thejo Engineering Limited Dividend Sustainability
Verdict: Sustainable
On balance, the Thejo Engineering dividend is Sustainable. The payout is tiny relative to the company’s capacity, and the balance sheet provides a deep buffer.
Supports Sustainability
- Low payout ratio: ~11% of profit
- High earnings cover: 9.1x (consolidated EPS)
- Deep cash cover: 12.3x the annual dividend
- Net-cash balance sheet: ₹61 cr
- Consistent 10-year payment record
Watch-Points (Why Not “Rock-Solid”)
- FY26 FCF coverage below 1x (0.77x)
- OCF only 0.80x of net profit (receivables)
- Profit flat/down despite +14.4% revenue
- Margin compression (16% → 13%)
- Loss-making overseas subsidiaries
The dividend is safe because it is small, not because cash generation is strong. If working-capital pressure and margin compression persist, dividend growth (not the dividend itself) is what will stall — exactly as it did this year, with the payout held flat at ₹5.
Peer Comparison – Thejo Engineering Limited
| Company | Div. Yield | Payout | ROE | ROCE | Balance Sheet |
|---|---|---|---|---|---|
| Thejo Engineering | 0.23% | ~11% | 15.7% | 19.4% | Net cash |
| Tega Industries | 0.12% | ~11% | 5.9% | 8.1% | Net cash |
| AIA Engineering | 0.41% | ~12% | 17.0% | 21.1% | Net cash |
Source: Screener.in, September 2026. Peers chosen for business overlap (mining/mineral-processing consumables and engineering).
Where Thejo Stands
Low yields are the industry norm here — all three peers yield well under 0.5% and pay out ~11–12% of profit. Thejo’s 0.23% yield sits mid-pack. On returns, Thejo (ROE 15.7%, ROCE 19.4%) comfortably beats direct competitor Tega Industries (ROE 5.9%, ROCE 8.1%) and trails only the much larger AIA Engineering.
Takeaway
Judged as a dividend stock, Thejo is average for its sector — a small yield backed by good returns and a clean balance sheet. None of these companies are income plays; they are chosen for growth and quality, with the dividend a minor extra.
Promoter Impact Analysis – Thejo Engineering Limited
Promoters hold 53.61% of Thejo Engineering (as of June 2026), so they receive the majority of every dividend rupee. Of the total ₹5.42 crore outflow:
| Shareholder Group | Holding | Dividend Received |
|---|---|---|
| Promoters | 53.61% | ₹2.91 cr |
| Public / Retail | 42.17% | ₹2.29 cr |
| DIIs | 3.38% | ₹0.18 cr |
| FIIs | 0.85% | ₹0.05 cr |
Alignment, Not Extraction
A ~11% payout means promoters are reinvesting nearly 90% of profit back into the business rather than paying themselves large dividends. Promoter holding has drifted down gently (from ~57% in FY16 to 53.6%) but remains a strong majority with no shares pledged — a sign of alignment with minority holders.
Minority Shareholder View
Retail investors collectively receive ₹2.29 cr. The dividend is distributed equally per share, so there is no structural disadvantage to minorities — but income-focused retail investors gain little here, since the real return proposition is capital growth.
Thejo Engineering Limited Dividend Taxation
Since April 2020, dividends in India are taxed in the hands of the investor, not the company. Key rules for the Thejo Engineering dividend:
- The dividend is added to your total income and taxed at your income-tax slab rate.
- TDS of 10% is deducted by the company if your total dividend from it exceeds ₹5,000 in a financial year (20% if PAN is not provided).
- Resident investors can submit Form 15G/15H to avoid TDS if their income is below the taxable limit.
Worked Example
An investor owns 1,000 shares of Thejo Engineering and receives the ₹5 dividend, in the 30% tax slab:
- Gross dividend: 1,000 × ₹5 = ₹5,000
- TDS deducted (10%, as it just reaches ₹5,000): ₹500 (adjustable against final tax)
- Tax at 30% slab: ₹1,500
- Net in-hand dividend: ₹3,500
- Effective post-tax yield (at ₹2,186): ~0.16%
For a 30%-slab investor, the already-small yield shrinks further after tax — reinforcing that Thejo is not an income stock.
Key Risks – Thejo Engineering Limited
1. Margin Compression
Operating margin fell from ~16% to ~13% as employee (+18.4%) and other expenses (+26%) outpaced revenue. If cost inflation persists, profit and dividend growth stay capped.
2. Rising Receivables / Working Capital
Trade receivables grew +29% vs +14.4% revenue, pulling OCF to 0.80x of profit. Stretched collections from large industrial clients tie up cash.
3. Loss-Making Overseas Subsidiaries
Subsidiaries in Australia, Brazil, Chile and the UAE dragged consolidated profit ~₹6.3 cr below standalone. Continued losses would weigh on group returns.
4. Cyclical End-Markets
Thejo depends on mining, steel, cement and power capex cycles. A downturn in these core sectors directly hits volumes and pricing.
5. Earnings Quality
FY26 PAT was flattered by a ₹5.52 cr non-cash depreciation-method boost. Underlying profit growth was weaker than the reported number implies.
6. Valuation Risk
At a P/E of ~41x with flat profit, the stock prices in strong growth. Any earnings disappointment could de-rate the shares sharply.
What To Monitor – Thejo Engineering Limited
1. Operating Margin Recovery
Watch whether OPM rebuilds toward 16%+ in FY27 quarters, or stays stuck near 13%. This decides future dividend growth.
2. Debtor Days & Cash Conversion
Track whether receivables growth re-aligns with revenue and OCF/PAT climbs back above 1.0x.
3. Free Cash Flow Coverage
FY26 FCF covered only 0.77x of the dividend. Watch for FCF coverage returning above 1x as the capex cycle normalises.
4. Subsidiary Turnaround
Monitor whether the overseas arms move toward break-even, narrowing the standalone-to-consolidated profit gap.
5. Order Book & Capex Payoff
The FY26 capex spike (₹34.8 cr) should translate into revenue and margin gains. Track order inflows and capacity utilisation.
6. Dividend Growth Trajectory
The dividend was held flat at ₹5 for two years. A resumption of growth would signal management confidence in earnings.
Should You Consider Thejo Engineering Limited for Dividend Income?
Positives
- Consistent 10-year dividend record, no cuts
- Very safe payout: ~11%, 9.1x earnings cover
- Net-cash balance sheet (₹61 cr), no pledging
- Strong returns: ROE 15.7%, ROCE 19.4%
- Revenue up +14.4%; long-term growth intact
Negatives
- Tiny yield: 0.23% — not an income stock
- Profit flat/down; margins compressed
- FCF coverage below 1x in FY26
- Receivables and working capital rising
- Rich valuation (P/E ~41x)
Bottom line: Thejo Engineering Limited is a quality, net-cash compounder that pays a small, dependable dividend — not a stock to buy for yield. The ₹5 FY26 dividend is safe and sustainable, but it was held flat because profit stalled even as sales grew. Investors should weigh the strong balance sheet and long-term growth against FY26’s margin and cash-conversion softness, and decide for themselves based on their own goals and risk tolerance.
Frequently Asked Questions
What dividend has Thejo Engineering announced for FY26?
What is the Thejo Engineering dividend yield?
What is the record date for the Thejo Engineering dividend?
What is the ex-dividend date for Thejo Engineering?
When will the Thejo Engineering dividend be paid?
Who is eligible for the Thejo Engineering dividend?
How is the Thejo Engineering dividend taxed?
Is the Thejo Engineering dividend sustainable?
What is the Thejo Engineering dividend history?
What should investors monitor in Thejo Engineering?
Why did Thejo’s profit fall while revenue grew in FY26?
Is Thejo Engineering a good dividend stock?
Disclaimer – Thejo Engineering Limited
This article is for informational and educational purposes only and does not constitute investment advice or a buy/sell/hold recommendation. Figures are drawn from Thejo Engineering’s FY26 filing (NSE, 27 May 2026) and third-party sources including Screener.in and NSE, believed reliable but not independently guaranteed; market prices and ratios are as of mid-September 2026 and will change. Some historical dividend-per-share figures are estimated from reported payout ratios and should be verified against annual reports. Securities investments are subject to market risks. Please consult a SEBI-registered investment adviser and read all offer/disclosure documents before investing. ShareBazaar Online and the author hold no responsibility for decisions taken based on this content.