
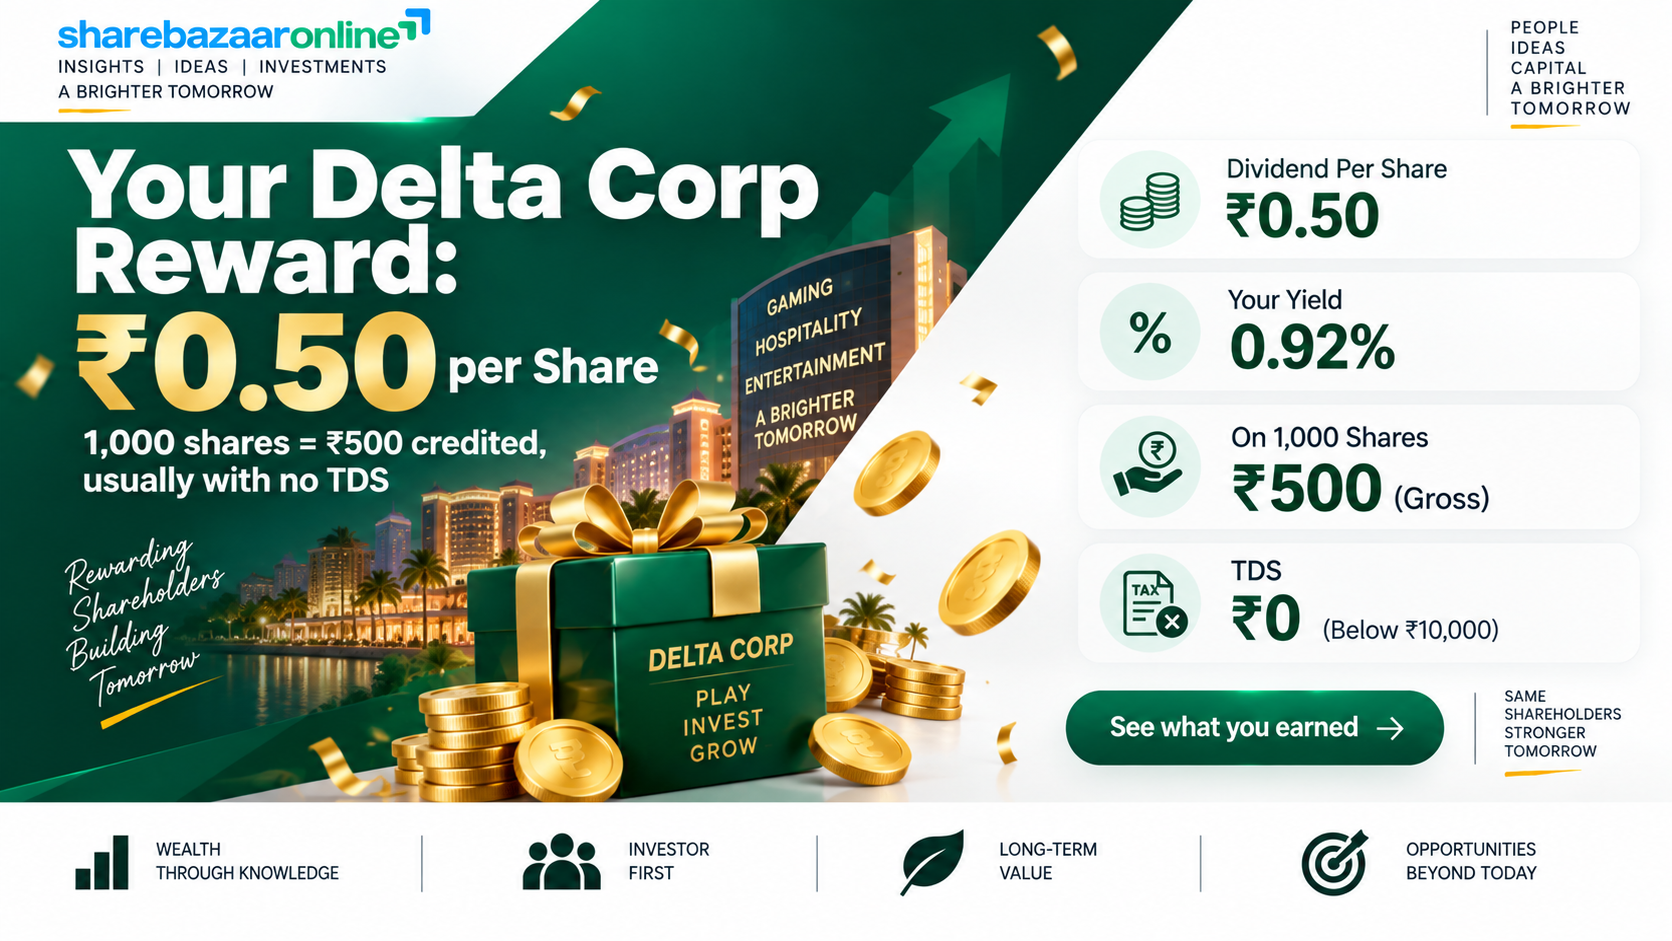
Dividend Snapshot
Delta Corp Limited (NSE: DELTACORP, BSE: 532848, ISIN: INE124G01033) — India's only listed pure-play casino operator — has recommended a Final Dividend of 50%, which works out to just ₹0.50 per equity share on a face value of ₹1 for the financial year ended 31 March 2026 (FY2025-26). The headline "50%" is a percentage of face value, not of your money invested. The real cash-yield story is far smaller.
Dividend Per Share
₹0.50
Final · 50% of ₹1 face value
Real Yield (at CMP ₹54.10)
0.92%
Not 50% — the face-value illusion
Change vs Last Year
−60%
Cut from ₹1.25 (FY22–FY25) to ₹0.50
Total Dividend Outflow
₹13.39 Cr
0.50 × 26.78 crore shares
The single most important number in this filing is not the dividend at all — it is the ₹24,959.69 crore aggregate GST show-cause exposure disclosed as a contingent liability, roughly 11 times the company's net worth. Read the dividend in that context.
Dividend Announcement Summary
At its Board meeting held on Wednesday, 22 April 2026 (which ran from 4:00 PM to 5:45 PM), the Board of Directors of Delta Corp Limited approved the audited standalone and consolidated results for the quarter and year ended 31 March 2026 and recommended a final dividend of ₹0.50 per equity share (50% of ₹1 face value).
Key points disclosed in the filing:
- The dividend is subject to shareholder approval at the ensuing Annual General Meeting and was to be paid within 30 days of that approval.
- The 35th AGM was held on 10 September 2026, where the 50% dividend was formally declared — so this is now an approved, past-event dividend.
- Statutory auditors are changing: M S K C & Associates LLP was appointed for five years (from the 35th to the 40th AGM), replacing Walker Chandiok & Co LLP after its tenure ended.
- The auditors issued an unmodified (clean) opinion, but attached two Emphasis of Matter notes — the GST contingency and the write-down of online real-money-gaming investments.
The forensic lead: for four straight years (FY2022 to FY2025) Delta Corp paid a stable ₹1.25 per share. This year the payout has been cut by 60% to ₹0.50 — the first reduction in the recent cycle. On a day when profits fell sharply, that cut is the clearest signal management sent.
Key Dates Timeline
| Event | Date | Status |
|---|---|---|
| Board Meeting / Announcement | 22 April 2026 | Completed |
| Record Date | 17 August 2026 | Passed |
| Ex-Dividend Date | 17 August 2026 (aligned with record date under T+1) | Passed |
| 35th AGM (approval) | 10 September 2026 | Held — dividend declared |
| Payment Window | Within 30 days of AGM (on or before ~9 October 2026) | Per filing |
Record date of 17 August 2026 is confirmed from the company's BSE communication on TDS/book closure. Under India's T+1 settlement, the ex-date and record date typically coincide (as they did for Delta Corp's FY25 dividend). For last year, payment was credited on 11 October 2025 — a comparable timeline is likely this year. Always verify the exact ex-date and payment date against the official NSE/BSE corporate-action circular.
Dividend Yield Analysis
The "50% dividend" headline confuses many first-time investors. That 50% is calculated on the ₹1 face value, not on the market price you actually pay. Here is what the yield really looks like:
Yield on Face Value (the headline)
50.00%
₹0.50 ÷ ₹1 face value — misleading
Yield at Current Price (₹54.10)
0.92%
₹0.50 ÷ ₹54.10 — the real number
Yield at Announcement Price (₹69.00)
0.72%
₹0.50 ÷ ₹69.00 on 22 Apr 2026 close
Real Yield vs Headline
54× smaller
0.92% real vs 50% quoted
In plain terms: on a ₹1 lakh investment at ₹54.10, this dividend puts roughly ₹924 in your pocket before tax — not ₹50,000. The current yield of 0.92% is below what a savings bank account pays. Delta Corp is not, and has never been, a high-yield income stock.
Dividend History Analysis
| Financial Year | Dividend / Share | Type |
|---|---|---|
| FY2025-26 | ₹0.50 | Final (cut) |
| FY2024-25 | ₹1.25 | Final |
| FY2023-24 | ₹1.25 | Final |
| FY2022-23 | ₹1.25 | Final |
| FY2021-22 | ₹1.25 | Final |
| FY2020-21 | ₹1.00 | Final |
| FY2019-20 | ₹1.50 | Interim + Final |
| FY2018-19 | ₹1.25 | Interim + Final |
| FY2017-18 | ₹1.00 | Final |
Per-share dividend history sourced from public corporate-action records (TipRanks/exchange filings). Figures are already on the current ₹1 face value.
Classification: Consistent Payer that has just cut. Delta Corp has paid a dividend every year since FY2016 and held a steady ₹1.25 for four consecutive years. The FY26 drop to ₹0.50 is the first material reduction in that run — a 60% cut. The reduction is not because the company cannot afford ₹1.25 (it comfortably can, as the cash analysis below shows); it reflects management caution against a backdrop of a 66% profit fall, a fresh loss-making June 2026 quarter, and unresolved regulatory and tax overhangs. A dividend cut on an affordable payout is a signal about confidence, not liquidity.
Financial Performance Analysis
All figures below are consolidated (the group view, including casinos, hospitality and subsidiaries), unless stated. FY26 was a year of falling revenue and severe negative operating leverage.
Revenue from Operations
₹688.46 Cr −5.6%
FY25: ₹729.63 Cr
Operating Profit (EBITDA)
~₹136 Cr −29.9%
OPM fell 27% → 20%
Net Profit (owners)
₹85.29 Cr −65.7%
FY25: ₹248.99 Cr (incl. one-time gains)
EPS (Consolidated)
₹3.19
FY25: ₹9.30
Operating leverage worked in reverse. Revenue fell 5.6%, but EBITDA fell 29.9% and net profit fell 65.7%. When a small drop in the top line produces a large drop in profit, the cost base is largely fixed — and Delta Corp's costs are: employee costs rose to ₹169.90 Cr (from ₹144.78 Cr, up ~17%) and licence fees & registration charges of ₹118.47 Cr are effectively fixed casino licence outgo. With gaming revenue itself soft (casino division fell from ₹678.60 Cr to ₹642.59 Cr), thinner margins flowed straight to the bottom line.
A crucial caveat on the prior year. FY25's "₹248.99 Cr profit" was flattered by a one-time exceptional gain of ~₹213 Cr from selling a 51% stake in Deltatech Gaming (Adda52 owner) and fair-valuing the residual holding. Strip that out and FY26's operating decline looks less dramatic against FY25's underlying business — but reported profit still collapsed. Reported profits are an opinion; the cash statement below is the fact.
Below the profit line, a red flag. Total Comprehensive Income for FY26 was negative ₹379.40 Cr. This is because the new Promotion and Regulation of Online Gaming Act, 2025 forced Delta Corp to write down its investments in real-money online-gaming companies (Deltatech Gaming, Head Digital Works, Openplay) to Nil, booking a ₹459.52 Cr reduction through Other Comprehensive Income. Reported profit stayed positive only because this hit bypassed the profit-and-loss statement and went straight to reserves.
Cash Flow Analysis
Cash is the acid test of a dividend. Here Delta Corp shows a split picture — strong operating cash, but negative free cash flow.
Operating Cash Flow (CFO)
₹135.00 Cr
Higher than reported PAT — healthy conversion
Capital Expenditure
₹253.34 Cr
Casino-hotel build-out (CWIP up to ₹468 Cr)
Free Cash Flow (CFO − Capex)
−₹118 Cr
Negative for a third straight year
Dividend Paid (in FY26)
₹33.47 Cr
This was the prior (₹1.25) dividend
How is the dividend funded? Operating cash flow of ₹135 Cr easily covers the new ₹13.39 Cr outflow — 10.1 times over. But free cash flow is negative because the company is ploughing ₹253 Cr into a new casino-hotel project (capital work-in-progress has climbed from ₹22 Cr in FY23 to ₹468 Cr in FY26). So while the dividend is paid out of operating cash and the large cash pile, the group as a whole is spending more than it generates. In sustainability terms: covered by earnings and operating cash, but not by free cash flow. This is exactly the kind of tension standard aggregator coverage skips.
Quality check — cash beats profit here. CFO of ₹135 Cr exceeds reported PAT of ₹85 Cr, and receivables are tiny (debtor days of just ~2). That is a positive: Delta Corp's casino revenue is largely cash-and-carry, so earnings are backed by real cash rather than growing receivables. The weakness is discretionary capex, not collection quality.
Balance Sheet Strength
Net Worth (equity, consol.)
₹2,251.69 Cr
Book value ~₹84 / share
Cash + Current Investments
₹276.73 Cr
₹75.70 Cr cash + ₹201.03 Cr liquid inv.
Borrowings
~₹49 Cr
Mostly lease liabilities — near debt-free
Price / Book
0.64×
Trading below book value
The balance sheet is genuinely strong — on paper. Delta Corp is almost debt-free, holds ₹277 crore of cash and liquid investments, and trades at just 0.64 times book value. On these numbers alone, a ₹13.39 crore dividend is trivially affordable. But the ₹24,959.69 crore aggregate GST contingent exposure sits entirely off this balance sheet, unprovided for. If even a fraction crystallises, the net-worth cushion erodes fast. The strength is real; the tail risk is enormous. Both must be held in view at once.
Dividend Sustainability Analysis
We run four coverage tests. The token size of the dividend means it passes most of them comfortably.
1. Earnings Coverage (EPS ÷ DPS)
6.4× Pass
Payout ratio just 15.7% (consol.)
2. Operating Cash Coverage
10.1× Pass
CFO ₹135 Cr vs outflow ₹13.39 Cr
3. Free Cash Flow Coverage
Fail
FCF negative (heavy capex)
4. Liquidity / Cash Coverage
20.7× Pass
Liquid assets ₹277 Cr vs outflow ₹13.39 Cr
Verdict: Conditionally Sustainable. The ₹0.50 dividend is easily affordable — it consumes barely a sixth of earnings and a tenth of operating cash. Three of four coverage tests pass with room to spare. The one failure (free cash flow) reflects the choice to invest heavily in a new casino-hotel, not distress. So why the label "conditional"? Because the company chose to cut the payout 60% despite this affordability. Management is prioritising balance-sheet conservatism ahead of a ₹24,960 crore GST cloud, a real-money-gaming ban, and a loss-making June 2026 quarter. The dividend is safe at ₹0.50; whether it returns to ₹1.25 depends on those overhangs clearing.
Peer Comparison
Delta Corp is the only listed pure-play casino operator in India, so there is no exact peer. The closest listed comparables sit in leisure, amusement and gaming. Treat this table as directional.
| Company | Div. Yield | Payout | ROE | P/B | Debt |
|---|---|---|---|---|---|
| Delta Corp | 0.92% | ~16% | 3.5% | 0.64× | Near nil |
| Wonderla Holidays | ~0.4% | ~12% | ~8% | ~1.8× | Near nil |
| Nazara Technologies | Nil (no regular div.) | — | Low | Premium | Near nil |
Peer figures are indicative and drawn from public screeners; verify before use. ROE/ROCE for Delta Corp: 3.5% / 5.1%.
What the comparison shows. Delta Corp actually offers the highest headline yield in this small set (0.92%), and trades at the cheapest valuation (below book value). But that "cheapness" is the market pricing in the GST and gaming-law risk. Wonderla, a debt-free leisure peer, earns a stronger return on equity (~8% vs Delta's 3.5%) and commands a much higher P/B (1.8× vs 0.64×) precisely because it carries none of Delta's regulatory tail risk. Nazara, the listed online-gaming name, pays no regular dividend and reinvests for growth. The takeaway: Delta's low valuation and slightly higher yield are a risk discount, not a bargain signal.
Promoter Impact Analysis
Promoter Holding
34.46%
Promoter dividend income ~₹4.61 Cr
Public Shareholders
63.68%
Public dividend income ~₹8.53 Cr
FII Holding
1.61%
Down from ~5% in 2023
DII Holding
0.24%
Collapsed from 7.75% (Mar 2025)
Who benefits — and who left. Of the ₹13.39 crore total dividend, promoters (34.46%) receive about ₹4.61 crore and public shareholders (63.68%) receive the majority, about ₹8.53 crore. Because promoter holding is relatively modest at ~34%, this is not a case of a dividend being routed largely to insiders — the public float captures most of it.
The more telling signal is institutional exit. Domestic institutions (DIIs) have fled: their stake crashed from 7.75% in March 2025 to just 0.24% a year later. FIIs have trimmed to ~1.6%. Public/retail holding has correspondingly risen above 63%. When professional money leaves and retail steps in around a regulatory cloud, that concentration of retail ownership is itself worth noting.
Taxation Analysis
Since FY2020-21, dividends are taxed in the hands of the shareholder at your applicable income-tax slab rate (there is no separate Dividend Distribution Tax). Key rules for FY2025-26:
- Slab-rate tax: the full dividend is added to your income and taxed at your slab (5% / 20% / 30%, plus cess).
- TDS under Section 194: the company deducts 10% TDS only if your total dividend from Delta Corp in the year exceeds ₹10,000 (this threshold was raised from ₹5,000 with effect from 1 April 2025). No PAN → TDS at 20%.
- Non-residents: TDS at 20% (plus surcharge/cess), subject to relief under any applicable DTAA.
- Section 57: you may deduct interest on money borrowed to buy the shares, capped at 20% of the dividend income — no other expense is allowed.
Worked example — investor holding 1,000 shares
| Item | Amount |
|---|---|
| Gross dividend (1,000 × ₹0.50) | ₹500 |
| TDS deducted | ₹0 (below ₹10,000 threshold) |
| Tax at 5% slab → net | ₹25 → ₹475 |
| Tax at 20% slab → net | ₹100 → ₹400 |
| Tax at 30% slab → net | ₹150 → ₹350 |
| Effective post-tax yield (30% slab, at ₹54.10) | ~0.65% |
Because the dividend is so small, you would need to hold more than 20,000 Delta Corp shares (a dividend above ₹10,000) before any TDS is deducted at all. For most retail holders, the full ₹0.50 per share is credited without any tax withheld — you simply report it in your return.
Key Risks
- GST mega-contingency (₹24,959.69 Cr). Show-cause notices to the group demand GST on gross bet/face value rather than gross gaming revenue. This aggregate exposure is roughly 11 times net worth and 17 times market cap. The matter is reserved for judgement before the Supreme Court; an adverse ruling would be existential, and no provision has been made.
- Online real-money gaming ban. The Promotion and Regulation of Online Gaming Act, 2025 has already forced Delta Corp to write its online-gaming investments (Deltatech Gaming, Head Digital Works, Openplay) down to Nil — a ₹459.52 Cr OCI hit. It closes a growth avenue and signals rising regulatory hostility toward the wider gaming sector.
- Falling core earnings. Revenue fell 5.6%, EBITDA fell ~30% and net profit fell 66% in FY26. The June 2026 quarter (Q1 FY27) reported a net loss of ~₹213 Cr, dragging trailing-twelve-month profit into the red. The core casino business is under pressure.
- Regulatory dependence on casino licences. The entire business rests on state casino licences (Goa, Sikkim, Daman) and offshore vessel permissions. Any policy change — higher taxes, licence caps, or a ban — hits revenue directly. Licence fees are already a large fixed cost (~₹118 Cr).
- Negative free cash flow during heavy capex. A large casino-hotel build-out (CWIP ₹468 Cr) keeps free cash flow negative. If earnings stay depressed while capex continues, the cash cushion will be drawn down.
- Institutional exit and retail concentration. DII holding collapsed from 7.75% to 0.24% and FIIs pared to ~1.6%, leaving retail holding above 63%. Thin institutional support can amplify volatility.
What To Monitor
- The Supreme Court GST verdict. This is the single most important catalyst, in either direction. Track the outcome of the reserved judgement on the ₹24,960 Cr industry-wide GST matter.
- Whether the dividend recovers. A return toward ₹1.25 in future years would signal restored management confidence; continued ₹0.50 or a further cut would confirm caution.
- Quarterly casino revenue and EBITDA margin. Watch whether the gaming division (₹642.59 Cr in FY26) stabilises and whether operating margin recovers from the ~20% level. The June 2026 loss makes the next few quarters critical.
- Capex completion and free cash flow turn. Track when the ₹468 Cr capital-work-in-progress converts into operating assets and revenue, and whether free cash flow turns positive.
- Progress on the NCLT restructuring scheme. The Revised Composite Scheme of Arrangement (Deltin Hotels, Delta Penland, Deltin Cruises) awaits NCLT Mumbai approval; its terms could reshape the group structure.
- Shareholding trend. Watch whether institutions return — a re-entry by DIIs/FIIs would suggest the regulatory cloud is perceived to be lifting.
Conclusion
The positives: Delta Corp's ₹0.50 dividend is comfortably affordable — a payout ratio of ~16%, operating-cash coverage of 10 times and a liquidity cushion of 21 times. The company is near debt-free, holds ₹277 crore in cash and liquid investments, and trades below book value at 0.64 times. Its casino revenue is genuinely cash-generative, with negligible receivables.
The negatives: The dividend has been cut 60% from a five-year run of ₹1.25. FY26 revenue, EBITDA and profit all fell sharply, the June 2026 quarter swung to a large loss, and free cash flow is negative amid heavy capex. Institutions have exited. Above all looms an unprovided ₹24,959.69 crore GST contingency and a real-money-gaming ban that has already zeroed out related investments.
The real story: This is not a dividend event — it is a ₹0.50 token distribution wrapped around an existential regulatory question. The 0.92% real yield is a rounding error next to the tail risks. The face-value "50%" headline tells you almost nothing; the cut, the cash-flow tension and the GST cloud tell you almost everything. We present the facts on both sides and leave the decision to you.
Frequently Asked Questions
What dividend has Delta Corp announced for FY2025-26?
What is the real dividend yield on Delta Corp shares?
What was the record date for the Delta Corp dividend?
What was the ex-dividend date?
When will the dividend be paid?
Who was eligible to receive the dividend?
How is the Delta Corp dividend taxed?
Is the Delta Corp dividend sustainable?
Has Delta Corp cut its dividend?
What is Delta Corp's dividend history?
Why is the ₹24,960 crore GST figure so important?
How did the online gaming ban affect Delta Corp?
What should investors monitor going forward?
Disclaimer
This article is for informational and educational purposes only and does not constitute investment advice, a recommendation, or an offer to buy or sell any security. ShareBazaar Online is not a SEBI-registered investment adviser. Figures are drawn from Delta Corp Limited's audited FY2025-26 results, exchange filings and public data sources; market prices, yields and computed ratios are as of the dates stated and will change. External figures (market price, shareholding, peer data, tax rules) should be independently verified against primary sources before any decision. Dividend, record and payment dates are subject to company and regulatory confirmation. Investing in equities carries risk, including loss of capital. Please consult a SEBI-registered financial adviser and read all official company disclosures before investing.