
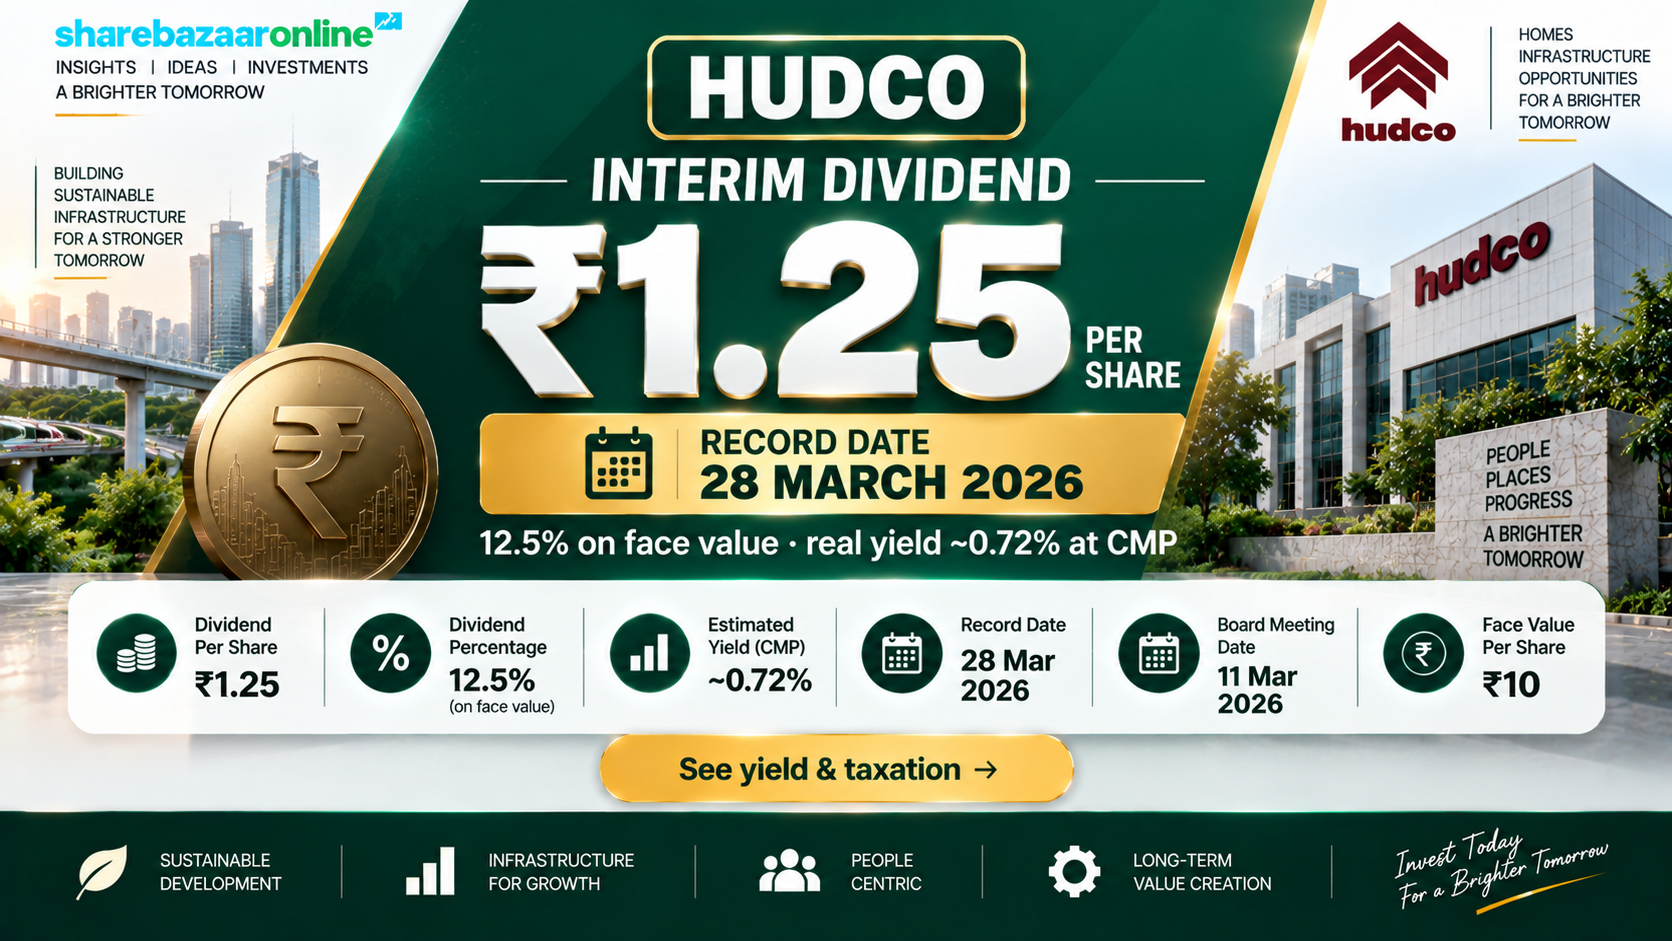
Dividend Snapshot
Housing & Urban Development Corporation Ltd (HUDCO), a Navratna Central Public Sector Enterprise under the Ministry of Housing & Urban Affairs, declared its 4th Interim Dividend of ₹1.25 per equity share (12.50% on a face value of ₹10) for FY2025–26 at its board meeting on 23 March 2026. The record date was fixed as 28 March 2026.
The headline “12.50%” is calculated on the ₹10 face value, not on the market price. Measured against the reference price around the announcement, this single interim delivered a real cash yield of well under 1% — the gap every dividend investor should understand before reacting to the percentage.
Dividend Per Share
₹1.25
4th Interim · 12.50% of ₹10 face value
Real Yield on This Interim
~0.72%
At CMP of ₹173 (11 Sep 2026 NSE close)
FY26 Full-Year Dividend
₹6.05
4 interims (₹1.15 + ₹1.00 + ₹1.15 + ₹1.25) + final ₹1.50
FY26 Yield (Full Year)
~3.50%
₹6.05 ÷ ₹173 current price
Record Date
28 Mar 2026
Ex-date 27 Mar 2026 (already passed)
Promoter (Govt of India)
75.00%
Receives ~₹188 Cr of this interim payout
The finding most reports miss: HUDCO’s FY26 net profit jumped ~49% to ₹4,034 Cr, but nearly ₹1,533 Cr of that came from a one-time deferred-tax write-back. Strip it out and core profit actually fell about 8% year-on-year. The dividend still looks comfortable, but on a normalised basis the cushion is thinner than the reported payout ratio suggests. Details in the sections below.
Dividend Announcement Summary
In its filing to BSE and NSE dated 23 March 2026, HUDCO’s Board of Directors approved the declaration of the 4th Interim Dividend of ₹1.25 per equity share (i.e. 12.50%, subject to TDS) on the face value of ₹10 each for the financial year 2025–26. The company fixed Saturday, 28 March 2026 as the record date for reckoning shareholder eligibility, and stated that the payment process would be completed within 30 days of declaration.
The same board meeting also approved an annual borrowing plan of up to ₹70,000 Cr for FY2026–27 through long-term and short-term loans, bonds and debentures (including 54EC capital gain tax-exemption bonds, perpetual Tier-I and Tier-II capital bonds), ECBs, FCNR(B) loans and multilateral borrowings. That plan tells you as much about HUDCO as the dividend does: this is a lending institution that grows by borrowing heavily and on-lending, so its cash-flow profile looks nothing like a manufacturer’s.
Company: Housing & Urban Development Corporation Ltd
NSE Symbol: HUDCO · BSE Code: 540530
ISIN: INE031A01017
Face Value: ₹10
Dividend Type: 4th Interim, FY2025–26
Amount: ₹1.25 per share (12.50%)
Announcement: 23 March 2026 (Monday)
Record Date: 28 March 2026 (Saturday)
Ex-Date: 27 March 2026
Payment: Within 30 days of declaration
Key Dates Timeline
Board Meeting / Announcement
23 March 2026
Monday · dividend declared
Ex-Dividend Date
27 March 2026
Buy before this date to qualify (T+1)
Record Date
28 March 2026
Saturday · eligibility reckoned
Payment Window
By ~22 April 2026
Within 30 days of declaration
Shareholders who held HUDCO in their demat account on the record date (28 March 2026) were eligible for this interim. Because India follows a T+1 settlement cycle, the ex-date fell one trading day before the record date. All of these dates have now passed; this article is a post-event analysis rather than an eligibility alert. The ex-date of 27 March 2026 is as reported by market data providers and should be confirmed against the official exchange corporate-action circular.
Dividend Yield Analysis
This is where the “12.50% dividend” headline needs translating. That percentage is applied to the ₹10 face value, giving ₹1.25 in cash. It is not the return on your invested rupee. To find the real yield, divide the cash dividend by the market price you actually pay.
Headline (on face value)
12.50%
₹1.25 on ₹10 — the number in the filing
Real yield — this interim
~0.72%
₹1.25 ÷ ₹173 current market price
Yield at announcement zone
~0.60%
₹1.25 ÷ ~₹210 (Mar 2026 reference; exact NSE close to be desk-verified)
Full-year FY26 yield
~3.50%
₹6.05 total ÷ ₹173 — the number that matters for income investors
Yield reality check: HUDCO’s trailing yield of ~3.5% is real and reasonable for a PSU lender — but note why it looks a touch higher than a year ago. The share price fell roughly 20% over the past 12 months (from a 52-week high of ₹246.85 to ₹173), which mechanically lifts the yield even though the rupee dividend rose only modestly. A yield that climbs because the price is falling is a very different signal from a yield that climbs because the payout is growing.
Dividend History Analysis
| Financial Year | Total Dividend / Share | Reported EPS | Payout Ratio |
|---|---|---|---|
| FY2021–22 | ₹3.50 | ₹8.57 | 41% |
| FY2022–23 | ₹3.85 | ₹8.50 | 45% |
| FY2023–24 | ₹4.15 | ₹10.57 | 39% |
| FY2024–25 | ₹4.20 | ₹13.53 | 31% |
| FY2025–26 | ₹6.05 | ₹20.15 | 30% |
Per-share totals and payout ratios compiled from public dividend records and Screener.in; individual interim splits vary by declaration timing. Payout ratios are on reported (not normalised) profit.
Classification: Consistent Payer. HUDCO has paid dividends every year for a decade, typically split across two or more interims plus a final. The rupee dividend has risen steadily from ₹3.50 (FY22) to ₹6.05 (FY26) — a genuine upward trend, with no cuts or suspensions in the visible history.
The subtle point: the payout ratio has actually drifted down (from 45% to 30%) even as the rupee amount rose, because reported EPS grew faster. But FY26’s EPS was flattered by the one-time tax write-back — on normalised earnings the FY26 payout is closer to 48%, in line with earlier years rather than the optically low 30%.
Financial Performance Analysis
| Consolidated (₹ Cr) | FY24 | FY25 | FY26 |
|---|---|---|---|
| Revenue | 7,831 | 10,345 | 13,150 |
| Profit before tax | 2,843 | 3,637 | 3,221 |
| Net profit (reported) | 2,117 | 2,709 | 4,034 |
| Effective tax rate | 26% | 26% | −25% |
Read the tax line, not just the profit line. Notice that FY26 profit before tax actually fell to ₹3,221 Cr from ₹3,637 Cr, yet net profit rose 49% to ₹4,034 Cr. That is only possible because the effective tax rate turned negative. HUDCO reversed ₹1,532.86 Cr from its deferred tax liability into the profit & loss statement after resolving to maintain the Special Reserve under Section 36(1)(viii) of the Income Tax Act. This is a genuine accounting entry, but it is a one-time, non-cash, non-operating gain.
The concentration is stark: the March 2026 quarter alone reported a net profit of ₹1,981 Cr (up ~172% year-on-year) on a pre-tax profit of just ₹621 Cr — the profit was larger than the pre-tax profit precisely because of this write-back.
Reported FY26 PAT growth
+48.9%
₹2,709 Cr → ₹4,034 Cr (as reported)
Core FY26 PAT growth (ex write-back)
−7.7%
Normalised core PAT ~₹2,501 Cr
Operating leverage: the operating engine remains healthy — revenue grew ~27% and the loan book expanded strongly — but the financing margin compressed (from ~35% to ~23% at the full-year level) as the cost of funding a fast-growing book rose. The core earnings picture is one of strong top-line growth with a flat-to-lower bottom line, masked at the reported level by the tax entry. Screener’s own checklist flags both the low effective tax rate and a low interest-coverage ratio.
Cash Flow Analysis
On paper, HUDCO’s cash flow looks alarming: operating cash flow was negative ₹33,912 Cr in FY26, and free cash flow was similarly negative. For a manufacturer, that would be a red flag. For a lending institution, it is normal and expected — and understanding why is essential.
Operating cash flow FY26
−₹33,912 Cr
Loans disbursed count as operating outflow
Financing cash flow FY26
+₹34,793 Cr
Borrowings raised to fund lending growth
When HUDCO disburses a loan, the cash going out is recorded under operating activities; when it raises bonds and loans to fund that lending, the cash coming in is recorded under financing activities. As the loan book grew (borrowings rose ~32% to ₹1,41,677 Cr), operating cash flow was deeply negative by design, offset almost exactly by financing inflows. The dividend is therefore not funded by operating cash flow in the manufacturing sense — it is paid out of accounting profits and the equity base, which is standard for an NBFC/financial institution.
The honest caveat: because the payout is not covered by free cash flow (there is none, by the nature of the business), dividend capacity for a lender must be judged on earnings quality, capital adequacy and asset quality — not on FCF. That is exactly what the sustainability section does.
Balance Sheet Strength
Consolidated Net Worth (Mar 2026)
₹21,975 Cr
Up from ₹17,968 Cr in FY25 · Book value ~₹110
Total Borrowings (Mar 2026)
₹1,41,677 Cr
+32% YoY — the fuel for loan growth
Net NPA
~0.18%
Very low; heavy government-agency lending
Reported ROE (FY26)
~20%
Flattered by tax write-back; ROCE ~8.4%
HUDCO’s balance sheet is expanding rapidly but remains anchored by low asset stress (net NPA ~0.18%) and a strengthening net worth. As a lender, its leverage is high by design — borrowings are the raw material. The reported 20% ROE looks excellent, but a large slice of FY26’s return came from the non-recurring tax entry; on normalised earnings, ROE is closer to the low-teens, in line with the 10-year average of ~14%. During Q4FY26 the company also raised ₹1,422 Cr of Perpetual Tier-I debt, supporting its capital base for continued growth.
Dividend Sustainability Analysis
For a lending institution, sustainability is judged on earnings coverage, capital adequacy and asset quality — not free cash flow. Here is the four-test scorecard.
1. Earnings coverage (reported)
3.33x
EPS ₹20.15 ÷ DPS ₹6.05 — comfortable
2. Earnings coverage (normalised)
2.06x
Core EPS ~₹12.49 ÷ ₹6.05 — still covered, thinner
3. Payout ratio (normalised)
~48%
On core profit, not the optical 30%
4. Asset quality / capital
Strong
Net NPA ~0.18%; Tier-I raise supports growth
Verdict: Moderately Sustainable. The FY26 dividend of ₹6.05 is covered roughly 2x by normalised earnings, sits at a ~48% normalised payout, and is backed by very low asset stress and 75% government ownership that incentivises steady distributions. The watch-item is earnings quality: if margin compression continues and one-off tax benefits do not repeat, the rupee dividend would depend on the core lending engine re-accelerating profit, not just revenue. Nothing here signals a cut — but the reported payout ratio overstates the cushion.
Peer Comparison
| PSU Lender | Approx. Div Yield | Approx. ROE | Approx. P/B |
|---|---|---|---|
| HUDCO | ~3.5% | ~20% (reported) | ~1.6–1.9x |
| REC Ltd | ~5.3% | ~20–22% | ~1.8x |
| Power Finance Corp | ~3.3–5% | ~high teens | ~1.2x |
| IRFC | ~1.5% | ~13–14% | ~2.3x |
| IREDA | ~0.5% | ~22% | ~2.8x |
Peer figures are approximate, sourced from public market data around mid-2026 and will move with prices; shown for context, not precision. Not directly comparable across differing business models (power, railways, renewables, urban infrastructure).
Where HUDCO sits: its ~3.5% trailing yield is mid-pack among PSU lenders — below high-payout REC and PFC, but well above growth-oriented IREDA and IRFC. On valuation it trades at a modest price-to-book. The key nuance is that HUDCO’s headline ROE is currently the most tax-flattered of this group; on normalised earnings its return profile is closer to the middle of the pack than the top.
Promoter Impact Analysis
This interim — total outflow
~₹250 Cr
₹1.25 × ~200.2 Cr shares
This interim — Govt of India share
~₹188 Cr
75% promoter holding
Full FY26 — total outflow
~₹1,211 Cr
₹6.05 × ~200.2 Cr shares
Full FY26 — Govt of India share
~₹908 Cr
Flows to the Union exchequer
With the Government of India holding 75%, roughly three of every four rupees of dividend flow to the exchequer — about ₹908 Cr across FY26. This alignment cuts both ways for minority investors. On the positive side, a promoter that relies on dividend income has a structural incentive to keep payouts steady and rising. On the caution side, distribution policy is shaped by the government’s fiscal needs as much as by the company’s reinvestment opportunities — a lender growing its book 30%+ could, in principle, retain more capital to fund growth rather than distribute it. The remaining ~₹303 Cr of the FY26 payout is shared by public, FII (~2.4%) and DII (~10%) holders.
Taxation Analysis
Since April 2020, dividends in India are taxed in the hands of the shareholder. There is no Dividend Distribution Tax at the company level anymore. Key rules: dividend income is added to your total income and taxed at your applicable income-tax slab rate; the company deducts TDS at 10% under Section 194 if your total dividend from that company in a financial year exceeds ₹10,000 (5,000 in earlier years — check the current threshold); and you can claim credit for the TDS when filing your return.
Worked example — this interim
Investor holds 1,000 shares, dividend ₹1.25/share, tax slab 30%:
Gross dividend = ₹1,250
TDS at 10% = ₹125 (withheld)
Tax at 30% slab = ₹375
Net in hand after tax = ₹875
Worked example — full FY26
Same 1,000 shares, full-year dividend ₹6.05/share, slab 30%:
Gross dividend = ₹6,050
TDS at 10% = ₹605 (withheld)
Tax at 30% slab = ₹1,815
Net in hand after tax = ₹4,235
Effective yield after tax: a 30%-slab investor keeps ~70% of the dividend, so the ~3.5% gross FY26 yield becomes roughly 2.45% after tax. Investors in lower slabs keep more; those below the taxable threshold can file Form 15G/15H to avoid TDS. HUDCO has advised shareholders to refer to its website (Investors > Dividend > TDS Communication) for TDS specifics. This is general information, not tax advice — consult a qualified professional for your situation.
Key Risks
- Earnings quality risk: FY26’s ~49% profit jump was driven by a one-time ₹1,532.86 Cr deferred-tax write-back; core profit fell ~8%. Future years will not have this tailwind, so reported earnings growth could look weak by comparison.
- Margin compression: the financing margin narrowed materially (from ~35% to ~23% at the full-year level) as the cost of funding a rapidly growing book rose. Sustained compression pressures the earnings that back the dividend.
- Rising leverage: borrowings grew ~32% to ₹1,41,677 Cr in FY26. A lender’s dividend capacity is sensitive to funding cost and access; any spike in borrowing costs squeezes spreads.
- Regulatory / provisioning risk: RBI project-finance provisioning norms and any tightening for infrastructure lenders could raise provisions and dent distributable profit, as seen across PSU lenders in 2026.
- Government-driven payout policy: with 75% government ownership, dividend decisions can reflect the exchequer’s fiscal needs rather than the reinvestment case for a fast-growing loan book.
- Price-driven yield illusion: the ~20% share-price decline over the past year has lifted the optical yield; a further de-rating would raise yield further without any improvement in fundamentals.
What To Monitor
- Normalised (core) profit trend: track pre-tax profit and profit excluding one-off tax entries — this is the real driver of future dividends, not headline PAT.
- Net interest margin / financing margin: watch whether the ~23% financing margin stabilises or keeps compressing as funding costs move.
- Loan-book growth vs asset quality: the book is growing 30%+; monitor whether net NPA stays near ~0.18% as newer, faster-growing exposures season.
- Cost of funds and borrowing mix: the ₹70,000 Cr FY27 borrowing plan makes funding cost a swing factor; track the blended cost trend.
- Payout policy signals: watch the rupee dividend per share and any stated dividend policy — whether HUDCO holds ₹6.05, raises it, or retains more capital for growth.
- Capital adequacy: follow Tier-I/CRAR levels and further perpetual-bond raises, which underpin both growth and distribution capacity.
Conclusion
HUDCO’s 4th interim dividend of ₹1.25 caps a full-year FY26 payout of ₹6.05 — a genuine step-up that continues a decade of consistent, rising distributions from a Navratna PSU lender with very low asset stress and 75% government backing. On the current price, the full-year yield of ~3.5% is respectable and mid-pack against PSU-lender peers.
The nuance a careful reader should carry away is two-fold. First, the “12.50%” headline is a face-value figure; the real cash yield on this single interim is under 1%. Second, FY26’s reported profit surge was substantially a one-time deferred-tax write-back of ₹1,532.86 Cr — on normalised earnings, core profit fell modestly and the payout ratio is closer to ~48% than the optical 30%. The dividend looks moderately sustainable, covered ~2x by core earnings, but the cushion is thinner than the reported numbers imply, and its future path depends on the core lending engine converting strong revenue growth back into profit growth. Positives, negatives, risks and monitoring points are laid out above so you can weigh them yourself.
Frequently Asked Questions
What dividend has HUDCO announced?
What is HUDCO’s dividend yield?
What was the record date for the HUDCO dividend?
What was the ex-dividend date?
When was the dividend paid?
Who was eligible for the dividend?
How is HUDCO’s dividend taxed?
Is HUDCO’s dividend sustainable?
What is HUDCO’s dividend history?
Why did HUDCO’s FY26 profit jump so much?
Why is HUDCO’s operating cash flow negative?
How much of the dividend goes to the Government of India?
What should investors monitor going forward?
Disclaimer
This article is for informational and educational purposes only and does not constitute investment, financial, legal or tax advice, nor a recommendation to buy, sell or hold any security. ShareBazaar Online is not a SEBI-registered investment adviser. Figures are compiled from the company’s exchange filing, Screener.in and public market data sources; some market prices (including the announcement-date reference price) are approximate and should be independently verified against official exchange records. Computed figures such as normalised profit, promoter dividend income and yields are our own estimates based on disclosed data. Dividend, taxation and eligibility rules are subject to change — verify current thresholds and consult a qualified professional before acting. Investments in securities are subject to market risks; past dividend history is not a guarantee of future payouts. Please do your own research.