
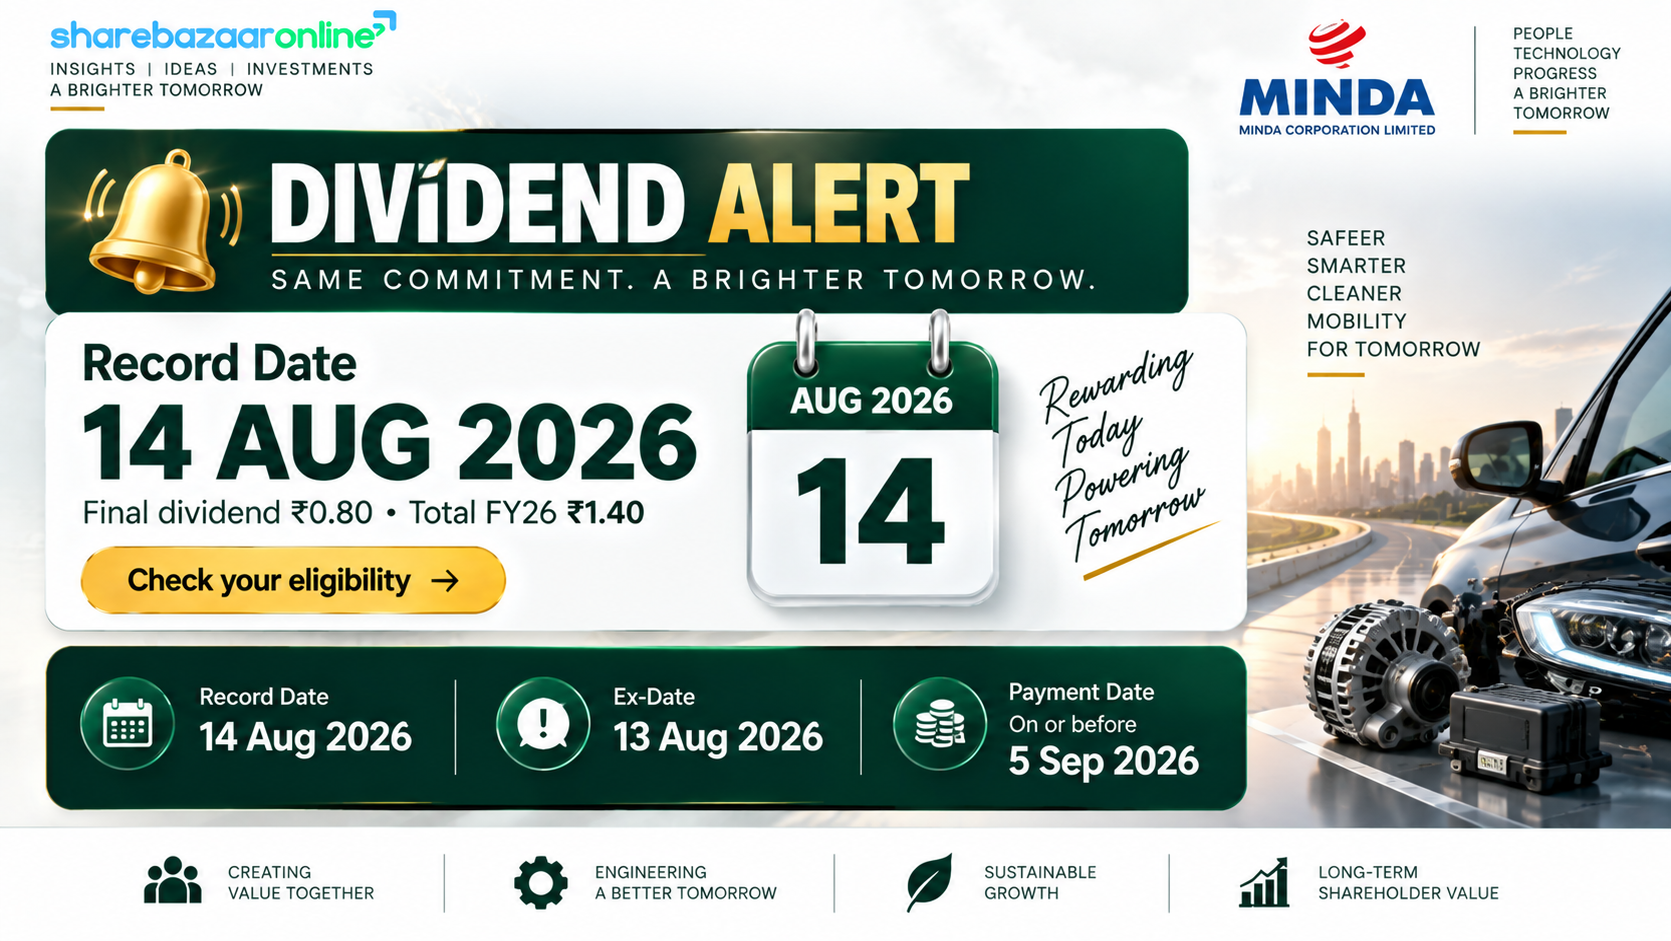
Dividend Snapshot
Minda Corporation Limited (NSE: MINDACORP, BSE: 538962) has recommended a final dividend of ₹0.80 per equity share for FY2025-26, equal to 40% of the ₹2 face value. Together with the ₹0.60 interim dividend paid earlier in the year, the total dividend for FY26 is ₹1.40 per share (70% of face value). The final payout is subject to shareholder approval, which was obtained at the 41st AGM held on 21 August 2026.
Final Dividend
₹0.80 / share (40%)
Total FY26 Dividend
₹1.40 / share (70%)
Real Dividend Yield (at CMP)
~0.20%
Total ₹1.40 ÷ CMP ₹702.80 (04-Sep-2026)
Record Date
14-Aug-2026
The one number to remember: the "70% dividend" headline is calculated on the ₹2 face value. On the actual market price of about ₹702.80, the real cash yield an investor earns is only about 0.20%. Minda Corporation is a growth-and-reinvestment stock, not an income stock — a distinction we unpack in detail below.
Dividend Announcement Summary
At its board meeting on 22 May 2026, the Board of Minda Corporation approved the audited standalone and consolidated results for the quarter and year ended 31 March 2026 and recommended a final dividend. The company is the flagship of the Spark Minda (Ashok Minda) group and operates in the auto-ancillary sector, making wiring harnesses, security and access systems, die-cast parts and interiors for two/three-wheelers, passenger and commercial vehicles.
Company: Minda Corporation Limited
NSE / BSE: MINDACORP / 538962
ISIN: INE842C01021
Face Value: ₹2 per share
Sector: Auto Ancillaries
Dividend Type: Final Dividend (FY2025-26)
Final Dividend: ₹0.80 per share (40%)
Interim (already paid): ₹0.60 per share (30%)
Total FY26: ₹1.40 per share (70%)
AGM approval: Obtained on 21-Aug-2026
The board also flagged that unclaimed dividend and shares for FY2018-19 (unpaid for seven consecutive years) will be transferred to the IEPF Authority, and issued/allotted 76,50,000 share warrants at ₹550 each to a promoter-group entity, receiving 25% subscription (₹105 crore) upfront.
Key Dates Timeline
Announcement / Board Meeting
22-May-2026
Record Date
14-Aug-2026
Ex-Date (inferred, T+1)
14-Aug-2026
Under India's T+1 regime the ex-date and record date normally coincide. This should be confirmed against the official NSE/BSE corporate-action circular.
Payment Date
Not Disclosed by Company
Statutory limit: within 30 days of AGM approval (i.e. by ~20-Sep-2026). In FY25 the final dividend was paid on 20-Sep-2025.
The 41st Annual General Meeting was held on 21 August 2026, where shareholders approved the final dividend. Because the record date of 14 August 2026 preceded the AGM, only shareholders on the register as of that date qualify for the final dividend once paid.
Dividend Yield Analysis
This is where the headline can mislead retail investors. A "40% final dividend" or "70% total dividend" is expressed as a percentage of the tiny ₹2 face value — it is not the return on your investment. The real dividend yield is the dividend divided by the actual share price you pay.
Headline (face-value) figure
70%
₹1.40 ÷ ₹2 face value — an accounting label, not a yield
Real total yield at CMP
~0.20%
₹1.40 ÷ ₹702.80 (CMP, 04-Sep-2026)
Yield at announcement price
~0.24%
₹1.40 ÷ ₹574.65 (NSE close, 22-May-2026)
Final dividend only (at CMP)
~0.11%
₹0.80 ÷ ₹702.80
Note that the real yield has fallen from about 0.24% at announcement to about 0.20% today — not because the dividend shrank, but because the share price rose roughly 22% (from ₹574.65 to ₹702.80). When a stock re-rates upward, its dividend yield mechanically compresses. This is a yield-falling-because-price-rose story, which is a healthy reason for a low yield, not a warning sign.
Dividend History Analysis
| Financial Year | Interim | Final | Total (per ₹2 share) | % of Face Value |
|---|---|---|---|---|
| FY2025-26 | ₹0.60 | ₹0.80 | ₹1.40 | 70% |
| FY2024-25 | ₹0.50 | ₹0.90 | ₹1.40 | 70% |
| FY2023-24 | ₹0.50 | ₹0.90 | ₹1.40 | 70% |
| FY2022-23 | ₹0.40 | ₹0.80 | ₹1.20 | 60% |
| FY2021-22 | ₹0.30 | ₹0.70 | ₹1.00 | 50% |
| FY2020-21 | ₹0.30 | ₹0.35 | ₹0.65 | 32.5% |
Face value has been ₹2 throughout this window, so no Ind AS 33 per-share restatement is required. Source: exchange corporate-action records / dividend-history data providers.
Minda Corporation is a consistent payer that has raised the total dividend from ₹0.65 in FY21 to ₹1.40 in FY24, FY25 and FY26 — a rising then plateauing pattern. It pays twice a year (an interim around February and a final around May/August).
The subtle change this year: the FY26 total is flat at ₹1.40 for a third straight year, but the mix shifted — a higher interim (₹0.60 vs ₹0.50) and a lower final (₹0.80 vs ₹0.90). Despite record profits, the absolute rupee dividend was not increased, signalling a deliberate preference for retaining cash.
Financial Performance Analysis
All figures below are on a consolidated basis (the group including subsidiaries, joint ventures and associates), which is the correct basis for judging the whole business. FY26 was a record year on every top line.
Consolidated Revenue
₹6,185 Cr +22.3%
FY25: ₹5,056 Cr
EBITDA
₹721 Cr +25.5%
Margin 11.7% (+29 bps)
Profit After Tax
₹358 Cr +40.3%
Margin 5.8%; EPS ₹15.31 (basic)
Standalone PAT
₹242 Cr
Standalone EPS ₹10.10
Operating-leverage check: revenue grew 22.3%, EBITDA 25.5% and PAT 40.3% — profits scaling faster than sales, which usually signals healthy operating leverage. But dig one layer deeper and a large part of the profit jump is not from the core factory.
Where the profit growth really came from (differentiated finding): the group's share of profit from associates and joint ventures leapt to ₹81 crore in FY26 from just ₹16 crore in FY25 — largely reflecting the 49% associate stake in Flash Electronics. That single line added about ₹65 crore, which is roughly 63% of the entire ₹103 crore year-on-year rise in consolidated PAT. In other words, the headline "40% profit growth" is substantially an associate-income story sitting below the operating line, not purely a manufacturing-margin story. This matters because associate income is equity-accounted and does not bring cash into the parent unless those associates themselves pay dividends.
Cash Flow Analysis
Reported profit is an accounting opinion; cash is a fact. Here Minda Corporation looks strong: on a consolidated basis it converted profit into cash comfortably.
Operating Cash Flow (FY26)
₹676 Cr
OCF ÷ PAT = 1.89x — strong conversion
Capital Expenditure
₹394 Cr
Heavy investment in capacity and new lines
Free Cash Flow (OCF − Capex)
₹281 Cr
Positive despite the capex cycle
Total FY26 Dividend Outflow
₹33 Cr
Tiny relative to ₹281 Cr FCF
Is the dividend funded from earnings, reserves, asset sales or borrowings? Squarely from current operating cash flow. The full FY26 dividend of about ₹33 crore is a rounding error against ₹281 crore of free cash flow and ₹676 crore of operating cash. No reserves, asset sales or debt were needed to fund it.
Receivables vs revenue: trade receivables grew 20.2% while revenue grew 22.3%. Receivables rising slightly slower than sales is a mild positive — there is no sign of profit being propped up by uncollected credit sales.
Balance Sheet Strength
Gross Debt (consolidated)
₹1,212 Cr
Down from ₹1,344 Cr in FY25
Net Debt
₹1,065 Cr
Down from ~₹1,247 Cr in FY25
Net Debt / Equity
~0.40x
Improved from ~0.6x
ROCE (FY26)
23.1%
Up from ~20.0% in FY24 and FY25
The group holds only about ₹147 crore of cash and bank balances, but it also carries roughly ₹1,558 crore of non-current investments — largely strategic stakes in subsidiaries, JVs and associates, which are not liquid. Net worth rose to about ₹2,659 crore. Interest cover (disclosed interest-service-coverage) is about 5.8x, and leverage is falling — a comfortable position from which to pay a small dividend.
Dividend Sustainability Analysis
| Coverage Test | Metric | Reading |
|---|---|---|
| Earnings coverage | 10.9x | EPS ₹15.31 ÷ DPS ₹1.40 (consolidated) |
| Operating cash flow coverage | 20.2x | OCF ₹676 Cr ÷ dividend ₹33 Cr |
| Free cash flow coverage | 8.4x | FCF ₹281 Cr ÷ dividend ₹33 Cr |
| Liquidity / cash coverage | 4.4x | Cash & bank ₹147 Cr ÷ dividend ₹33 Cr |
Composite verdict: Sustainable. Every one of the four tests passes comfortably. The dividend is so small relative to profit and cash that affordability is simply not the question. Standalone earnings coverage is still a healthy 7.2x (EPS ₹10.10 ÷ ₹1.40), and the parent additionally receives about ₹34 crore of dividend income up-streamed from its own subsidiaries, which more than funds the entire distribution.
The real constraint is choice, not capacity. With a payout ratio of only about 9% of consolidated profit (about 14% of standalone profit), management is deliberately keeping the cash inside the business to fund capex and acquisitions rather than paying it out. Investors should read the low dividend as a capital-allocation decision, not a coverage worry.
Peer Comparison
| Company | Div Yield (approx) | Payout Ratio | ROCE | Promoter Holding |
|---|---|---|---|---|
| Minda Corporation | ~0.20% | ~9% (cons) | 23.1% | 64.84% |
| UNO Minda | ~0.18% | ~8% | ~15.7% | 68.37% |
| Sundram Fasteners | ~0.75% | ~30% | >17% | ~46.95% |
| Gabriel India | ~0.46% | ~27% | ~30% (core) | Not Disclosed by Company |
| Auto Components sector avg. | ~0.6% | — | — | — |
Peer yields and payouts are approximate and price-dependent; verify at the point of publishing. Blank cells are left intentionally where a figure could not be independently verified.
Minda Corporation sits at the low-yield, low-payout end of the auto-ancillary pack, alongside its larger sister-in-name UNO Minda. Its yield of about 0.20% is well below the sector average of about 0.6%, and below higher-payout names like Sundram Fasteners (~0.75%). Crucially, Minda Corporation posts the highest ROCE (23.1%) in this group while paying the least — consistent with a company reinvesting high-return capital rather than distributing it.
Promoter Impact Analysis
Promoter Holding
64.84%
Total Dividend Outflow (FY26)
~₹33.5 Cr
Flowing to Promoter Group
~₹21.7 Cr
Final dividend alone: ~₹12.4 Cr
Flowing to Public / Non-Promoter
~₹11.8 Cr
Because promoters own 64.84%, roughly two-thirds of every rupee of dividend — about ₹21.7 crore of the ₹33.5 crore total — flows to the Ashok Minda promoter group. Minority (public) shareholders share the remaining ₹11.8 crore. This is normal for a promoter-controlled company; the point is transparency, not criticism. Institutions (DIIs ~18% and FIIs ~9%) hold the bulk of the non-promoter float.
Taxation Analysis
Since the abolition of the Dividend Distribution Tax in 2020, dividends are taxed in the hands of the shareholder under "Income from Other Sources" at your applicable income-tax slab rate. Companies deduct TDS at 10% under Section 194 (20% if PAN is not provided) only when total dividend from that company in a financial year exceeds ₹10,000 — a threshold raised from ₹5,000 with effect from FY2025-26. TDS is not an extra tax; it is adjusted against your final liability when you file your return.
Worked example — investor in the 30% slab, FY26 dividend ₹1.40 per share
| Item | 1,000 shares | 10,000 shares |
|---|---|---|
| Gross dividend (₹1.40 × shares) | ₹1,400 | ₹14,000 |
| TDS @ 10% (only above ₹10,000) | ₹0 | ₹1,400 |
| Total tax @ 30% + 4% cess | ₹437 | ₹4,368 |
| Net dividend in hand | ₹963 | ₹9,632 |
The 1,000-share holder receives the full ₹1,400 up front (below the TDS threshold) but still owes ₹437 at filing. Post-tax effective yield at CMP ₹702.80 is about 0.14% for a 30%-slab investor. Cess/surcharge and slab vary by individual; this is illustrative only.
Key Risks
1. Negligible income return. At a real yield of about 0.20%, this stock offers almost no cash income. It is unsuitable for anyone buying primarily for dividend income; the entire return case rests on capital appreciation.
2. Profit quality skewed to associate income. About 63% of FY26's profit growth came from the share of profit of associates/JVs (largely Flash Electronics), which is non-cash at the parent and depends on those entities continuing to perform.
3. Rich valuation. The stock trades at a trailing P/E in the region of 33–38x. A low dividend gives little downside cushion if earnings disappoint or the auto cycle turns.
4. Cyclical, customer-concentrated demand. As an auto-ancillary supplier to OEMs, revenue is tied to two/three-wheeler and commercial-vehicle production volumes, which are cyclical and sensitive to interest rates and fuel/regulatory shifts.
5. Execution and dilution risk on the growth pivot. Heavy capex (₹394 Cr), multiple new JVs (Toyodenso, Turntide) and the ₹550 share-warrant issuance (potential ~3.2% dilution) mean the reinvestment strategy must deliver returns to justify the low payout.
What To Monitor
1. Payout trajectory. Whether management lifts the absolute rupee dividend above ₹1.40 as profits grow, or continues to hold it flat and reinvest — a signal of how it views its own reinvestment runway.
2. Core (ex-associate) margin. Track EBITDA margin (currently 11.7%) and the CFO's stated FY30 target of a 12.5% margin, to see how much profit growth is coming from the base business versus associates.
3. Return on invested capital. ROCE has climbed to 23.1%; sustaining it while deploying heavy capex is the test of whether retention beats distribution for shareholders.
4. Net debt and free cash flow. Net debt fell to ₹1,065 Cr and net D/E to 0.40x; watch whether the capex/JV cycle keeps FCF positive and leverage falling.
5. Warrant conversion and EV order execution. Conversion of the 76.5 lakh warrants and delivery on EV/electronics orders (wiring harnesses, Flash Electronics ramp) will shape both the share count and future earnings.
Conclusion
Minda Corporation's FY26 dividend of ₹1.40 per share (70% of face value) is a headline that sounds generous but translates to a real yield of only about 0.20% on the current price of about ₹702.80. The dividend is comfortably sustainable — covered 10.9x by earnings, 20.2x by operating cash flow and 8.4x by free cash flow — but it is deliberately kept small, at a payout of only about 9% of consolidated profit.
The honest picture: this is a growth-and-reinvestment company that happens to pay a token dividend, not an income stock. Record FY26 revenue (₹6,185 Cr), improving ROCE (23.1%) and falling net debt are the real story — along with the important nuance that a majority of this year's profit jump came from associate/JV income rather than the core factory. Roughly two-thirds of the dividend flows to promoters given their 64.84% stake. Investors seeking cash income will find little here; investors backing the reinvestment strategy should judge the company on execution, not on its dividend.
Frequently Asked Questions
What dividend has Minda Corporation announced for FY2025-26?
What is the real dividend yield on Minda Corporation shares?
What is the record date for the Minda Corporation final dividend?
What is the ex-dividend date?
When will the dividend be paid?
Who is eligible to receive the dividend?
How is the dividend taxed?
Is the Minda Corporation dividend sustainable?
What is Minda Corporation's dividend history?
Why did most of FY26 profit growth not come from the core business?
How much of the dividend goes to promoters?
What should investors monitor going forward?
How does Minda Corporation's yield compare with peers?
Disclaimer
This article is for informational and educational purposes only and does not constitute investment, financial, legal or tax advice, nor any recommendation to buy, sell or hold any security. ShareBazaar Online is not a SEBI-registered investment adviser. Figures are drawn from Minda Corporation's board filing dated 22 May 2026, its audited FY2025-26 results, and publicly available market and dividend data; some data points (current market price, ex-date, payment date and peer figures) are price-dependent or inferred and must be independently verified before acting. All yield and dividend calculations are illustrative and can change with the share price. Taxation depends on individual circumstances and prevailing law — consult a qualified professional. Investments in securities are subject to market risks; please read all related documents carefully and make your own independent decisions.