
Dividend Snapshot
Gateway Distriparks Limited (NSE: GATEWAY | BSE: 543489 | ISIN: INE079J01017) has declared a First Interim Dividend of ₹1.25 per equity share (12.5% on face value of ₹10) for the financial year 2026-27. The dividend was approved at the Board meeting held on Wednesday, 05 August 2026, with a Record Date of 11 August 2026 and payment on or before 04 September 2026.
Dividend Per Share
₹1.25
12.5% on ₹10 face value
Dividend Yield (this interim, at CMP)
≈ 2.32%
₹1.25 ÷ ₹53.89 CMP (07-Sep-2026, exchange data)
Dividend Type
First Interim
FY 2026-27
Estimated Dividend Outflow
≈ ₹62.6 Cr
₹1.25 × ~50.06 Cr shares (derived)
Dividend Announcement Summary
At its meeting on 05 August 2026 (which ran from 01:05 P.M. to 01:50 P.M. IST), the Board of Gateway Distriparks approved four items: the un-audited Q1 FY2026-27 financial results (quarter ended 30 June 2026), the First Interim Dividend of ₹1.25/share, and the re-appointments of Ms. Vanita Yadav (Non-Executive Independent Director) and Mr. Ishaan Gupta (Joint Managing Director), both for a further five-year term from 27 December 2026, subject to shareholder approval at the ensuing AGM (scheduled 25 September 2026).
Facts disclosed by the company (from the exchange filing):
- Dividend per share: ₹1.25 (12.5% of ₹10 face value)
- Dividend type: First Interim Dividend for FY 2026-27
- Announcement / Board date: 05 August 2026
- Record Date: 11 August 2026
- Payment: on or before 04 September 2026 (within 30 days of declaration)
- Total dividend outflow: Not Disclosed by Company (estimated ≈ ₹62.6 Cr below)
- Shares outstanding / share capital: Not Disclosed in this filing (≈ 50.06 Cr shares / ≈ ₹500 Cr, derived from market data)
- Management commentary on the dividend: Not Disclosed by Company in the outcome letter
- Standalone AGM approval for the dividend: Not required — interim dividends are declared by the Board
Key Dates Timeline
Announcement Date
05 August 2026
Board meeting (Wednesday)
Ex-Dividend Date
11 August 2026
Derived: under T+1 settlement the ex-date coincides with the record date. The filing stated only the Record Date; one data vendor lists 10-Aug-2026.
Record Date
11 August 2026
Eligibility cut-off (Tuesday)
Payment Date
On or before 04 September 2026
Within 30 days of declaration (Thursday)
To be eligible, an investor must hold shares as of the Record Date, 11 August 2026. Under India's T+1 settlement cycle, the shares had to be bought on or before the ex-date so that the trade settled by the record date.
Dividend Yield Analysis
Yield on this ₹1.25 interim dividend
- At announcement-day price (~₹56, 05-Aug-2026): ≈ 2.23%
- At latest CMP (₹53.89, 07-Sep-2026): ≈ 2.32%
Annualised / trailing yield (context)
- On a ₹2.00 regular annual run-rate: ≈ 3.71%
- On the FY26 trailing payout of ~₹3.25 (per Investing.com): ≈ 6.0%
How the yield is calculated
Dividend Yield % = (Dividend Per Share ÷ Current Market Price) × 100. The single interim of ₹1.25 gives roughly a 2.3% yield; the headline "5–6%" figures quoted on some portals annualise a larger FY26 payout and reflect a lower share price. See the Yield Reality Check in the Sustainability section for why the trailing yield looks elevated.
Dividend History Analysis
Recent dividend record (per exchange / TipRanks data)
| Financial Year | Dividend(s) per share | FY Total | Type |
|---|---|---|---|
| FY 2026-27 | ₹1.25 (1st interim, Aug 2026) | ₹1.25* | Interim (ongoing) |
| FY 2025-26 | ₹1.25 (Aug 2025) + higher 2nd interim (Feb 2026) | ≈ ₹3.25 | Interim × 2 |
| FY 2024-25 | ₹1.25 (Aug 2024) + ₹0.75 (Feb 2025) | ₹2.00 | Interim × 2 |
| FY 2023-24 | ₹1.25 (Aug 2023) + ₹0.75 (Feb 2024) | ₹2.00 | Interim × 2 |
| FY 2022-23 | ₹1.25 (2022) + ₹0.75 (Feb 2023) | ₹2.00 | Interim × 2 |
| Pre-FY2022 | Not cleanly comparable — the present entity was named "Gateway Rail Freight Limited" until the Scheme of Amalgamation renamed it "Gateway Distriparks Limited" on 11 February 2022, so the pre-2022 per-share series belongs to a different capital structure. | ||
*FY27 still in progress; a second interim is typically declared around February. Amounts sourced from third-party dividend trackers and exchange filings; the ~₹3.25 FY26 figure follows Investing.com's trailing annualised payout.
Consistency & trend
Since FY2022-23 the company has paid a dividend twice a year (an August first interim plus a February/March second interim) without a skip. The first interim has been steady at ₹1.25 for four consecutive years. However, third-party data flags a 5-year dividend growth rate of about −12.94% and describes the payments as "paid unevenly", reflecting the pre-merger disruption and a broadly flat-to-lower trajectory.
Classification: Consistent (but modest) Payer
On the post-merger record, Gateway is a Consistent Payer — regular semi-annual interims, no suspension, no visible cut in the first interim. The caveat is that the payout has been flat to slightly declining rather than growing, so it is a steady income stock rather than a dividend-growth story.
Financial Performance Analysis (Consolidated)
Q1 FY2026-27 (quarter ended 30 June 2026) — consolidated
| Metric | Q1 FY27 | Q1 FY26 | Change |
|---|---|---|---|
| Total income | ₹553.7 Cr | ₹554.1 Cr | ≈ flat |
| EBITDA | ₹121.5 Cr | — | Margin 21.9% vs 22.2% |
| Profit before tax | ₹69.3 Cr | — | — |
| PAT (total, consolidated) | ₹51.3 Cr | ₹62.2 Cr | −17.6% |
| EPS | ₹0.98 | ₹1.20 | Lower |
| Throughput (TEUs) | 1,83,867 | 1,87,550 | −1.96% |
Why did profit fall on flat revenue? (Operating Leverage)
Revenue was essentially flat and the EBITDA margin slipped only ~30 basis points (22.2% → 21.9%). The 17.6% PAT drop is almost entirely a tax effect, not operating deterioration: the company shifted to the concessional tax regime under Section 115BAA from 01 April 2026, so the tax rate jumped to 25.17% from an effective 9.57% a year earlier (which had benefited from MAT credit). Volumes dipped ~2%, cushioned by tariff hikes taken in June 2026.
Full-year context (FY2025-26, consolidated)
FY26 revenue was around ₹2,211–2,229 Cr with PAT of roughly ₹248–259 Cr (EPS ≈ ₹5.0–5.2), per Screener and other data services. Snowman Logistics (50.01% owned) contributed Q1 revenue of ₹177.1 Cr, EBITDA of ₹29.3 Cr and net profit of ₹4.6 Cr; the core container business (ex-Snowman) did revenue of ₹373 Cr and EBITDA of ₹92 Cr.
Cash Flow Analysis
Profit is an opinion; cash is a fact
The most important cash-flow insight this quarter is that the PAT decline is largely non-cash / accounting in nature. Management itself noted that despite the reported tax rate rising to 25.17%, the actual cash tax outgo rose only marginally — from 17.47% to 18.88% — because accumulated MAT credit is being utilised. In other words, the profit fell far more than the cash the business actually parts with, so operating cash generation is much less affected than the 17.6% headline PAT fall suggests.
Operating cash flow vs net profit
Quarter-level operating cash flow and free cash flow figures are Not Disclosed by Company in the results release. On a full-year basis third-party services describe Gateway as a company that has reduced debt and generates positive operating cash flow, but investors should verify the exact numbers against the FY27 cash flow statement when the annual report is published.
How is the dividend funded?
The ~₹62.6 Cr interim outflow is small next to FY26 PAT of ~₹259 Cr, and it is being paid from current earnings rather than by selling assets or raising borrowings — consistent with the "reduced debt" and IND AA rating signals. Exact free cash flow coverage of the dividend is Not Disclosed by Company and should be checked in the audited cash flow statement.
Balance Sheet Strength
Credit & leverage
- Credit rating: India Ratings IND AA / Stable (affirmed March 2026)
- Debt: third-party data notes the company has reduced debt
- Promoter pledge: 0% (no pledge risk flagged)
- Net debt figure: Not Disclosed by Company in the quarterly release
Return ratios
- ROE (3-yr): ≈ 12.4% (flagged as low)
- ROCE: ≈ 12–13% range (third-party estimates)
- ROIC (TTM): ≈ 8.83% vs WACC of ~12.12% (GuruFocus) — returns currently below cost of capital
- Cash & investments: Not Disclosed by Company in this release
Watch item — contingent liabilities
Screener flags contingent liabilities of roughly ₹6,000 crore for the group (largely tax and rail-haulage related disputes). These are not on-balance-sheet debt, but a material adverse ruling could crystallise into a real cash outgo, so they are worth monitoring alongside the dividend.
Dividend Sustainability Analysis
Coverage & payout
- Dividend coverage (TTM EPS ~₹5.0 ÷ ₹1.25): ≈ 4.0× for this interim
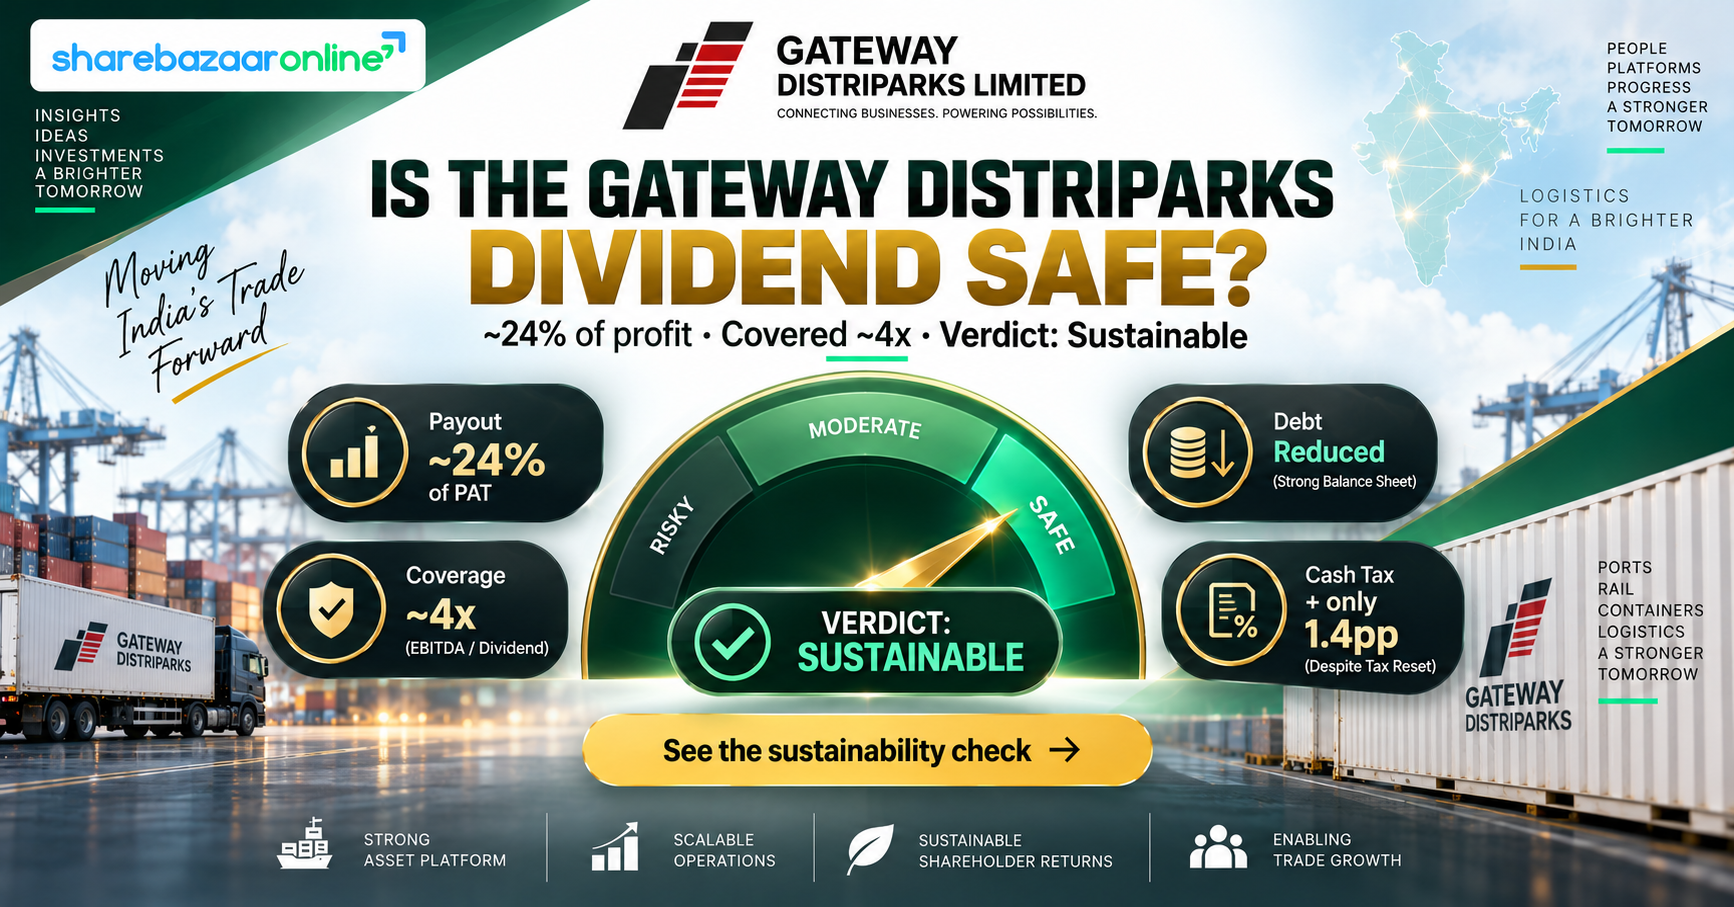
- This ₹62.6 Cr interim is only ~24% of FY26 PAT (₹259 Cr)
- Full-year payout ratio run-rate: ~35–42% (Screener); ~65% on the larger FY26 trailing payout (Investing.com)
Yield Reality Check
The trailing yield looks high mainly for two reasons that are not a stronger dividend: (1) the share price has fallen ~28% over one year (from a 52-week high of ₹67.72, and ~40% off the Dec-2024 high near ₹92), which mechanically lifts yield; and (2) FY26 included a larger-than-usual second interim. The regular ₹1.25 first interim yields only ~2.3%.
Verdict: Moderately Sustainable → Sustainable
On affordability the dividend is comfortable: it consumes well under a quarter of annual profit, is covered ~4× by earnings, debt has been reduced, and the AA rating is intact. The tempering factors are that reported profit is now structurally lower after the 115BAA tax reset, return ratios sit below the cost of capital, the group is in a capex-heavy expansion phase, and the dividend has not been growing. Net-net, the current ₹1.25 interim looks sustainable; a repeat of the larger FY26-style second interim is more earnings- and cash-dependent and should not be assumed.
Peer Comparison
Gateway Distriparks vs listed logistics peers (approx., latest third-party data)
| Company | Approx. Dividend Yield | Payout | ROE (3-yr) | Balance sheet |
|---|---|---|---|---|
| Gateway Distriparks | ~2.3% (this interim) / ~3.7% annualised | ~35–42% | ~12.4% | Reduced debt, IND AA |
| Container Corp (CONCOR) | ~1.8–1.9% | ~45–54% | ~10.2–10.5% | Almost debt-free (PSU) |
| Allcargo Logistics | Variable | — | — | Lower financial stability (peer note) |
| Transport Corp of India (TCI) | Low (~0.7%) | Low | ~20%+ | Strong returns, growth-tilted |
The takeaway: Gateway offers a higher dividend yield than the much larger CONCOR (₹2,700 Cr vs ~₹37,000 Cr market cap), with a lower payout ratio — leaving room to sustain the dividend. But its ROE is only middling, similar to CONCOR and well below a growth-focused peer like TCI. Gateway is a mid-yield, modest-growth logistics play rather than a high-return compounder.
Promoter Impact Analysis
Shareholding (approx., latest)
- Promoter group: ~33.9% (flagged as low) — largest is Prism International Pvt Ltd at 24.09%
- Foreign institutions (FII): ~6.7–8.4%
- Domestic institutions / mutual funds: ~33–40% (HDFC Small Cap ~9.48%)
- Public: ~25%
Who receives the dividend cash?
- Estimated total outflow: ≈ ₹62.6 Cr
- Promoter share (~33.9%): ≈ ₹21.2 Cr
- Prism International (24.09%): ≈ ₹15.1 Cr
- Minority / public + institutions (~66%): ≈ ₹41.4 Cr
Because promoter holding is relatively low (~34%), the majority of the dividend (~66%) flows to non-promoter shareholders — a more even distribution than at companies with 60–75% promoter stakes. The Gupta family (Prem Kishan Dass Gupta and sons Ishaan and Samvid) controls management; the re-appointment of Ishaan Gupta as Joint Managing Director keeps that continuity.
Taxation Analysis
Indian dividend tax rules (since FY2020-21)
- Dividends are taxable in the hands of the shareholder at their income-tax slab rate; there is no Dividend Distribution Tax and no separate exemption.
- TDS under Section 194: the company deducts 10% TDS if total dividend paid to a resident shareholder in a financial year exceeds ₹10,000 (this threshold was raised from ₹5,000 with effect from 01 April 2025). Submit Form 15G/15H if eligible; for missing PAN, TDS is 20%.
- The TDS is adjustable against final tax liability when you file your return.
Worked example (generic, ₹10/share)
Investor holds 1,000 shares, dividend ₹10/share, tax slab 30%:
- Gross dividend: ₹10,000
- Tax @30% + 4% cess: ₹3,120
- Net in hand: ₹6,880
- TDS: at exactly ₹10,000 no TDS is triggered; above the threshold, 10% (₹1,000+) is withheld and later adjusted.
Gateway-specific example (₹1.25/share)
Investor holds 1,000 shares, dividend ₹1.25/share, tax slab 30%:
- Gross dividend: ₹1,250
- TDS: Nil (below ₹10,000 threshold)
- Tax @30% + 4% cess: ₹390
- Net in hand: ₹860
- Effective post-tax yield (at ₹53.89): ≈ 1.6%
Key Risks
- Tax normalisation: the shift to Section 115BAA structurally raises the tax rate (25.17% vs 9.57% effective), so reported PAT is permanently lower — the ~18% Q1 drop is the first visible sign.
- EXIM & volume dependence: Q1 throughput fell 1.96% to 1,83,867 TEUs. The business is geared to export-import container flows and is exposed to global trade slowdowns and geopolitical disruption (West Asia crisis impacted earlier volumes).
- Margin pressure: EBITDA margin already eased to 21.9%. High fuel/input costs and intensifying competition in CFS and rail could keep margins under pressure despite June-2026 tariff hikes.
- Large contingent liabilities (~₹6,000 Cr): tax and haulage disputes that, if they go against the company, could become real cash outflows.
- Capex vs cash claims: a funded expansion pipeline (Ankleshwar MMLP EXIM ops from Sept 2026, Indore ICD by 2028) competes with dividends for cash; execution and funding are risks.
- Below-cost-of-capital returns: ROIC (~8.8%) sits under WACC (~12%), meaning the business is not currently creating economic value as it grows.
- Uneven dividend growth: a ~−12.9% five-year dividend growth rate and a "paid unevenly" tag mean income is steady but not rising.
What To Monitor
- TEU throughput recovery — whether rail and CFS volumes return to growth in coming quarters after the Q1 dip.
- EBITDA margin trajectory — whether the June-2026 tariff hikes stick and the margin holds near ~22%.
- Free cash flow after capex — how much cash is left once the terminal-expansion spending is deducted (check the FY27 cash flow statement).
- Net debt & credit rating — continued debt reduction and maintenance of the IND AA rating.
- Ankleshwar MMLP ramp-up (EXIM ops from Sept 2026) and Indore ICD (2028) — whether new terminals add profitable volume.
- Full-year FY27 dividend — whether the second interim matches the elevated FY26 payout or reverts to the ₹0.75-style top-up.
- Western DFC utilisation — double-stack train volumes on the completed freight corridor.
- Contingent-liability / litigation outcomes (including Jaipur ICD) that could affect cash.
Conclusion
Gateway Distriparks' ₹1.25 first interim dividend for FY2026-27 continues an unbroken run of semi-annual payouts and yields about 2.3% on the current price (higher on an annualised basis). The dividend itself is well covered — roughly 4× by earnings and only about a quarter of annual profit — and is backed by a de-levered, IND AA-rated balance sheet.
The nuance retail investors should carry away is that this quarter's 17.6% profit fall is mostly a tax-accounting reset, not an operating collapse — cash tax rose only marginally, revenue was flat, and margins held. The real watch-points are flat volumes, below-cost-of-capital returns, a heavy capex pipeline, and a dividend that is steady but not growing. The elevated trailing yield on some portals is inflated by a ~28% one-year price decline and a larger FY26 payout rather than a stronger regular dividend. This is an income-style logistics stock to hold for a modest, reasonably safe yield — with the sustainability of any larger future payout tied to volume recovery and free cash flow.
Frequently Asked Questions
What dividend has Gateway Distriparks announced?
What is the Gateway Distriparks dividend yield?
What is the record date for the Gateway Distriparks dividend?
What is the ex-dividend date?
When will the Gateway Distriparks dividend be paid?
Who is eligible for the dividend?
How is the Gateway Distriparks dividend taxed?
Is the Gateway Distriparks dividend sustainable?
What is Gateway Distriparks' dividend history?
Why did Gateway Distriparks' Q1 FY27 profit fall?
What should investors monitor going forward?
How much is the total dividend outflow?
How does Gateway compare with CONCOR on dividends?
Disclaimer
This article is for informational and educational purposes only and does not constitute investment advice or a recommendation to buy, sell or hold any security. Figures from the company's exchange filing are stated as disclosed; other data points (market price, financial ratios, shareholding, peer figures and dividend history) are sourced from third-party services such as the NSE/BSE, Screener, Investing.com, TipRanks and others as of early September 2026 and may change or contain errors. Where information was unavailable it is marked "Not Disclosed by Company." Derived figures (e.g. dividend outflow, yield, promoter income) are estimates. ShareBazaar Online is not a SEBI-registered investment adviser. Please verify all data independently and consult a qualified financial adviser before investing. Investments in securities are subject to market risks.