
Dividend Snapshot
Company
Symphony Limited
NSE: SYMPHONY · BSE: 517385 · ISIN: INE225D01027
Dividend Announced
Final Dividend of ₹5.00 per share (250%)
Face value ₹2 · FY 2025-26
Full-Year FY26 Dividend
₹9.00 per share (450%)
₹4 interim (3 payouts) + ₹5 final · Total outflow ₹61.80 cr
FY26 Dividend Yield (on latest price)
≈ 1.58%
₹9 ÷ CMP ₹568 (NSE, 02-Sep-2026)
Announcement Date
15 May 2026
Board Meeting outcome, BSE/NSE filing
Record / Ex / Payment Date
Not Disclosed by Company
Final dividend subject to shareholder approval at the ensuing AGM
The Symphony dividend for FY26 arrives in an unusual year: the air-cooler major declared a ₹5 final dividend (250%) even as it reported a consolidated net loss of ₹141 crore, its first annual loss in years. This report goes beyond the announcement to test whether the payout is funded by earnings, cash, or reserves — and what the numbers mean for a long-term investor tracking the Symphony share dividend.
Dividend Announcement Summary
At its board meeting on 15 May 2026, Symphony Limited approved its audited standalone and consolidated results for Q4 and the full year ended 31 March 2026, and recommended a final dividend of ₹5.00 per equity share (250%) on a face value of ₹2. This final dividend amounts to ₹34.34 crore and is subject to approval by shareholders at the ensuing Annual General Meeting.
What was declared
- Final dividend: ₹5.00/share (250%)
- Three interim dividends already paid in FY26: ₹4.00/share (200%) in aggregate
- Total FY26 dividend: ₹9.00/share (450%)
- Total FY26 cash outflow: ₹61.80 crore
Alongside the dividend
- Auditors (B S R & Co. LLP) issued an unmodified opinion
- Consolidated FY26 net result: loss of ₹141 crore
- Exceptional items of ₹208 crore (led by a ₹173.09 crore goodwill impairment on the Australia business)
- Mr. Nrupesh Shah reappointed MD – Corporate Affairs for 5 years (w.e.f. 1 Nov 2026)
Reader takeaway: The headline "250% final dividend" is calculated on the ₹2 face value, not the market price. In rupee terms, an investor receives ₹5 per share from this final dividend, or ₹9 per share counting the full year.
Key Dates Timeline
Announcement Date
15 May 2026
Record Date
Not Disclosed by Company
Ex-Dividend Date
Not Disclosed by Company
Payment Date
Not Disclosed by Company
The Symphony dividend record date and ex-date for the ₹5 final dividend were not fixed in the 15 May 2026 board outcome, because the final dividend must first be approved at the AGM. Investors tracking eligibility should watch for a separate exchange filing that sets the record/ex-dates, which typically fall close to the AGM. To be eligible, you generally need to hold the shares before the ex-date once it is announced.
Dividend Yield Analysis
Yield on the latest price
At a latest market price of about ₹568 (NSE, 02-Sep-2026), the full-year FY26 dividend of ₹9 gives a dividend yield of ≈1.58%. The ₹5 final dividend alone works out to about 0.88%. Note the stock has been volatile, trading roughly in a ₹560–690 band over recent weeks, so the exact yield moves with the price.
Yield at announcement
Around the 15 May 2026 announcement, Symphony traded near ₹771. On that price, the full-year ₹9 dividend was a yield of about 1.17%, and the ₹5 final dividend about 0.65%. The reason the current yield looks higher is largely that the share price has fallen since then — a point we return to in the Yield Reality Check below.
Yield Reality Check
A rising dividend yield is not automatically good news. Symphony's yield has crept up mainly because the stock is down roughly 40% over the past year, from a 52-week high above ₹1,200. The company's absolute dividend actually fell this year (₹9 in FY26 versus ₹13–14 in the prior year). So the higher headline yield reflects a lower price and a smaller payout, not a bigger reward — the classic sign of a yield that has risen for the "wrong" reasons.
Dividend History Analysis
| Financial Year | Total Dividend / Share | % on FV ₹2 | Notes |
|---|---|---|---|
| FY 2025-26 | ₹9.00 | 450% | ₹4 interim + ₹5 final; paid in a loss-making year |
| FY 2024-25 | ₹13–14 | 650–700% | Higher payout; included an ₹8 final |
| FY 2023-24 | ₹13.00 | 650% | Multiple interim payouts |
| FY 2014-15 (ref.) | ₹6.50 | 325% | Starting point of the last decade's growth trend |
FY26 from company filing. Prior-year totals are from public market data providers and are indicative; exact per-year figures can vary by source.
Consistency & trend
Symphony has paid dividends for many years, and the annual payout broadly grew from about ₹6.50 in 2015 to the ₹13–14 range recently — a growth rate of roughly 7% a year. However, market data providers note the dividend has been cut at least once in the last decade, so it is not a perfectly smooth record.
Classification
On this record, Symphony reads as a consistent-but-cyclical payer: it pays every year, but the amount flexes with the highly seasonal, monsoon-sensitive air-cooler business. FY26's reduction from ₹13–14 to ₹9 is a live example of that cyclicality.
Financial Performance Analysis
Consolidated FY26 vs FY25 (₹ crore)
| Particulars | FY26 | FY25 | Change |
|---|---|---|---|
| Revenue from operations | 1,131 | 1,576 | −28% |
| Profit before exceptional & tax | 149 | 326 | −54% |
| Exceptional items | 208 | 46 | — |
| Profit/(Loss) before tax | (59) | 280 | Loss |
| Net Profit/(Loss) | (141) | 213 | Loss |
| EPS (₹) | (20.54) | 30.89 | Loss |
Operating leverage worked against Symphony
Revenue fell 28%, but profit before exceptional items fell faster, by 54% (₹326 cr → ₹149 cr). This is negative operating leverage: when sales drop, relatively fixed costs bite harder. Employee cost actually rose to ₹136 cr (from ₹126 cr) even as revenue shrank, squeezing margins. A weak, erratic summer for air coolers is the core demand driver here.
What turned profit into a loss
The reported loss is driven by one-off exceptional charges of ₹208 cr — chiefly a ₹173.09 cr goodwill impairment plus ₹35.47 cr of asset write-downs on the underperforming Australia (Climate Holdings/CTPL) business — and a ₹44 cr deferred-tax write-down. Strip these out and the underlying business was still operationally profitable (PBT before exceptionals of ₹149 cr), just sharply lower.
Standalone view: The parent (India) business reported FY26 revenue of ₹765 cr (down from ₹1,182 cr) and a net loss of ₹166 cr, after a ₹298 cr impairment of its investment in the Australian subsidiary. Return ratios reflect the weak year: consolidated ROE fell to about 3%, while ROCE stayed near 20–21% on the core operations (external data). Five-year sales growth has been muted at roughly 5%.
Cash Flow Analysis
Reported profit is an opinion; cash is a fact. This is where the Symphony dividend story gets uncomfortable. On a consolidated basis, FY26 net cash from operations was negative at ₹(81) crore, versus a healthy +₹259 crore in FY25. Yet the company paid out ₹82 crore of dividends during the year.
Where the cash went
Operating profit before working-capital changes was ₹130 cr, but a large working-capital outflow (trade payables down ₹50 cr, other liabilities down ₹52 cr) plus ₹49 cr of taxes turned operating cash negative. Free cash flow (operating cash minus ₹19 cr capex) was therefore about ₹(100) crore on a consolidated basis.
How the dividend was funded
With operating and free cash flow negative, the FY26 dividend was effectively funded from the balance sheet: Symphony raised ₹147 cr by selling non-current investments and drew on its treasury. In short, this year's payout came from reserves and investment sales, not from current-year operating cash.
Standalone nuance: the parent's operating cash flow was slightly positive at ₹16 crore, but after ₹16 cr of capex its standalone free cash flow was roughly break-even — still well short of the ₹82 cr dividend paid. The gap was bridged by selling investments (₹147 cr) and receiving subsidiary loan repayments (₹97 cr). This is the single most important red flag in this analysis: a shrinking-cash year should be watched closely if it repeats.
Balance Sheet Strength
Liquidity cushion (consolidated, 31-Mar-26)
- Cash & equivalents: ₹50 cr
- Current investments: ₹114 cr
- Non-current investments: ₹155 cr
- Total cash + investments: ≈ ₹319 cr
Debt & net position
- Current borrowings: ₹144 cr (up from ₹128 cr)
- Finance cost: ₹16 cr (up from ₹10 cr)
- Approx. net cash (cash + inv − borrowings): ≈ ₹175 cr
- Total equity: ₹545 cr (down from ₹761 cr)
Symphony still holds a net-cash balance sheet of roughly ₹175 crore, so the ₹61.80 cr FY26 payout is comfortably affordable in absolute terms. But two things have moved the wrong way: goodwill of ₹155 cr has been written down to nil, and borrowings and finance costs have risen while cash was used for dividends and investment activity. Net worth fell from ₹761 cr to ₹545 cr, largely due to the impairment losses.
Dividend Sustainability Analysis
| Coverage Test | FY26 (reported) | Read |
|---|---|---|
| Payout ratio (Div ÷ PAT) | Not meaningful (loss) | ≈56% on normalised profit |
| Dividend coverage (EPS ÷ DPS) | −2.3x | ≈1.8x on normalised EPS |
| FCF coverage (FCF ÷ outflow) | Negative | Not covered by FY26 cash |
| Cash coverage (cash+inv ÷ outflow) | ≈5.2x | Balance sheet can absorb it |
"Normalised" strips out the ₹208 cr exceptional items and ₹44 cr deferred-tax write-down. Coverage figures are ShareBazaar Online computations from the filing.
The case that it is sustainable
The loss is non-cash and one-off (impairment of an overseas business). The underlying India operation stayed profitable, the balance sheet is net-cash, and cash + investments cover the payout more than 5 times. Symphony has also already resumed dividends in FY27 (a ₹1 first interim), signalling intent to keep paying.
The case for caution
Free cash flow was negative and the dividend was funded by selling investments — not repeatable indefinitely. The dividend was already cut from ₹13–14 to ₹9. If weak summers and margin pressure persist, further payout cuts are possible.
Verdict — Moderately Sustainable. Affordable today because of a strong treasury, but not currently funded by operating cash. Sustainability from here depends on a recovery in the core air-cooling business and a return to positive free cash flow.
Peer Comparison
| Company | Div. Yield (approx.) | Business tilt |
|---|---|---|
| Symphony | ≈1.5–1.6% | Pure-play air coolers; net-cash, high-ROCE, asset-light |
| Crompton Greaves Consumer | ≈1% | Fans, pumps, appliances |
| Havells India | ≈0.7% | Diversified electricals |
| V-Guard Industries | ≈0.5–0.6% | Stabilisers, wires, appliances |
| Voltas | ≈0.4–0.5% | Air-conditioning, cooling |
| Bajaj Electricals | ≈0.4% | Appliances, lighting |
Peer yields are indicative approximations from public market data and move with price. Symphony's own figures are from the filing and cited sources.
Against consumer-durable peers, Symphony has traditionally been an above-average dividend payer, helped by an asset-light model and historically strong ROCE (~20%). Its advantage is a cash-generative, low-capex core; its disadvantage is high seasonality and a single-category concentration (air cooling) that most diversified peers do not carry. The FY26 loss is company-specific (overseas impairment), not an industry-wide event.
Promoter Impact Analysis
Promoter dividend income
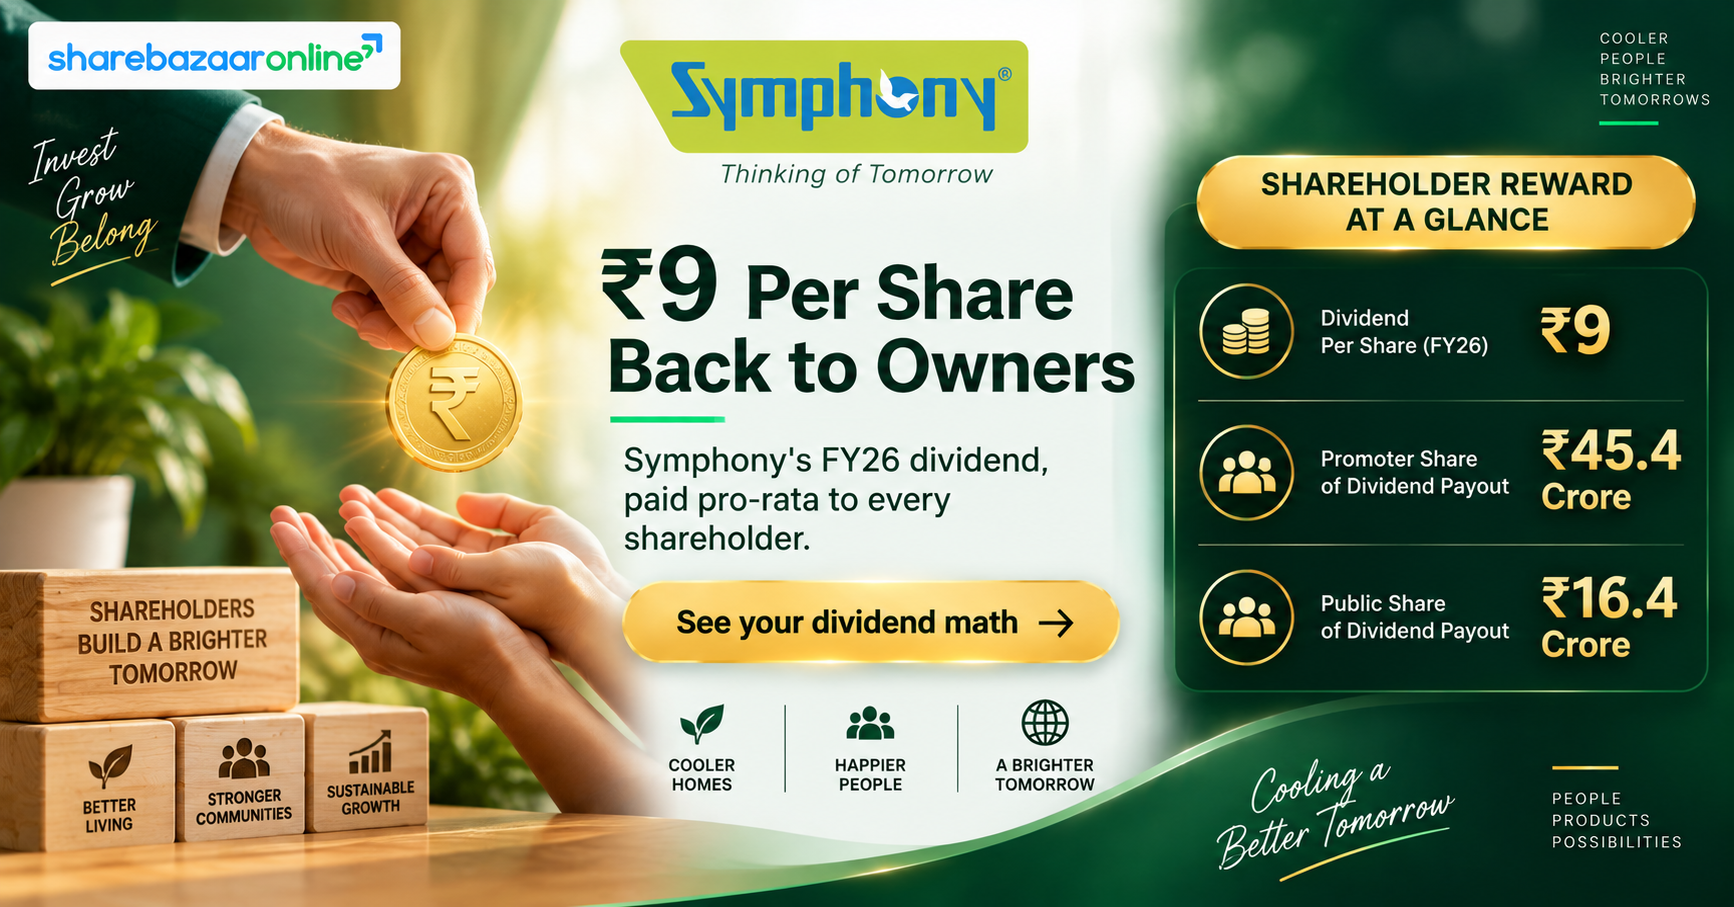
Promoter holding is about 73.43% (Mar 2026, unchanged). On the full-year ₹61.80 cr payout, the promoter group's share is roughly ₹45.4 crore; on just the ₹5 final dividend (₹34.34 cr), about ₹25.2 crore.
Minority shareholders
Public and institutional shareholders (the remaining ~26.6%) receive the balance — about ₹16.4 crore of the full-year payout. Every shareholder is paid the same ₹9 per share, so the distribution is pro-rata and even-handed.
Reading it fairly: a high promoter stake means most of the dividend flows to the founding family, which can align interests (promoters want the business to keep generating cash). The flip side is that in a loss year, a large payout funded partly from reserves also benefits promoters most — a reason to keep watching whether payouts track real cash generation going forward.
Taxation Analysis
Since April 2020, dividends in India are taxed in the hands of the investor at their applicable income-tax slab rate (there is no separate Dividend Distribution Tax). The company deducts TDS under Section 194 at 10% only if your total dividend from that company in the year exceeds ₹10,000 (the threshold was raised from ₹5,000). For most small holders below that limit, no TDS is deducted, but the dividend is still taxable.
Worked example — 1,000 Symphony shares
- Gross dividend (1,000 × ₹9 full-year): ₹9,000
- TDS u/s 194: NIL (below the ₹10,000 threshold)
- Tax at 30% slab + 4% cess (31.2%): ₹2,808
- Net dividend in hand: ₹6,192
- Effective post-tax yield (on ₹568 price): ≈1.09%
Illustrative for a 30%-slab investor. A holder in a lower slab pays less; if annual dividend crosses ₹10,000, 10% TDS applies and is adjusted against final tax. Not tax advice — consult a professional for your situation.
Key Risks
- Weather & seasonality risk: Air-cooler demand hinges on summer intensity. An erratic or short summer — as seen in FY26 — can cut revenue sharply (down 28% this year) and drag profits down even faster.
- Single-category concentration: Symphony is largely a one-product company (air cooling). Newer lines like tower fans and water heaters are still small relative to the core.
- Overseas execution risk: The FY26 loss came from impairing the Australia business (₹173 cr goodwill plus asset write-downs). Global subsidiaries in Australia, Mexico, China, Brazil and the US add currency and turnaround risk.
- Cash-flow risk to the dividend: FY26 operating and free cash flow were negative, and the payout leaned on investment sales. A repeat could pressure future dividends.
- Valuation risk: Even after a ~40% fall, the stock trades at a high multiple of book value (P/B in the 7–8x range), so disappointments can hit the price hard.
- Rising cost base: Employee and finance costs rose while revenue fell, showing limited near-term cost flexibility.
What To Monitor
- Return to positive operating & free cash flow: The single most important signal that the dividend is being funded by the business again, not by reserves.
- Core India air-cooler revenue recovery: Watch summer-quarter (Q1/Q4) volumes and whether FY27 rebuilds the ₹1,131 cr revenue base. Early FY27 data showed Q1 revenue up ~8% YoY — a tentative green shoot.
- Australia/overseas turnaround: After the reset (manufacturing shift to outsourcing, IP and Bonaire moved under the parent), track whether foreign operations stop bleeding.
- Dividend trajectory: Whether the payout stabilises around ₹9 or is cut further; and whether future dividends match free cash flow.
- Margins & cost control: Employee and other-expense trends versus revenue — the operating-leverage story needs to reverse.
- Record/ex-date filing & AGM outcome: Confirmation of the final-dividend approval and the eligibility dates.
Conclusion
Symphony's ₹5 final dividend (250%) caps a full-year payout of ₹9 (450%) in a year the company slipped to a ₹141 crore consolidated loss. The positives are real: the loss is driven by one-off overseas impairments, the India business remains operationally profitable, and a net-cash balance sheet covers the payout more than five times over.
The negatives are equally real: the dividend was cut (from ₹13–14 to ₹9), FY26 free cash flow was negative, and the payout was funded partly by selling investments rather than by operating cash. The higher current yield reflects a falling share price, not a bigger reward. Net-net, this is a moderately sustainable dividend that now depends on a cyclical recovery in air cooling. We present the positives, negatives, risks and monitoring points — the decision is yours.
Frequently Asked Questions
What dividend has Symphony announced for FY26?
What is the Symphony dividend yield?
What is the record date for the Symphony dividend?
What is the ex-dividend date?
When will the Symphony dividend be paid?
Who is eligible for the Symphony final dividend?
How is the Symphony dividend taxed?
Is the Symphony dividend sustainable?
What is Symphony's dividend history?
Why did Symphony report a loss but still pay a dividend?
How much dividend income goes to the promoters?
What should investors monitor after this dividend?
Disclaimer
This article is prepared by ShareBazaar Online for informational and educational purposes only and is based on Symphony Limited's board meeting outcome and audited results dated 15 May 2026, together with publicly available market data. It is not investment, legal or tax advice, and does not constitute a recommendation to buy, sell or hold any security. Market prices, yields and dates are subject to change; record, ex-dividend and payment dates for the final dividend had not been disclosed at the time of writing and are subject to shareholder approval at the AGM. Figures marked as computed are our own workings and may differ from other sources. Please verify all data from the company's filings and consult a SEBI-registered financial adviser and a qualified tax professional before making any investment decision. ShareBazaar Online and its authors accept no liability for any loss arising from the use of this information.