
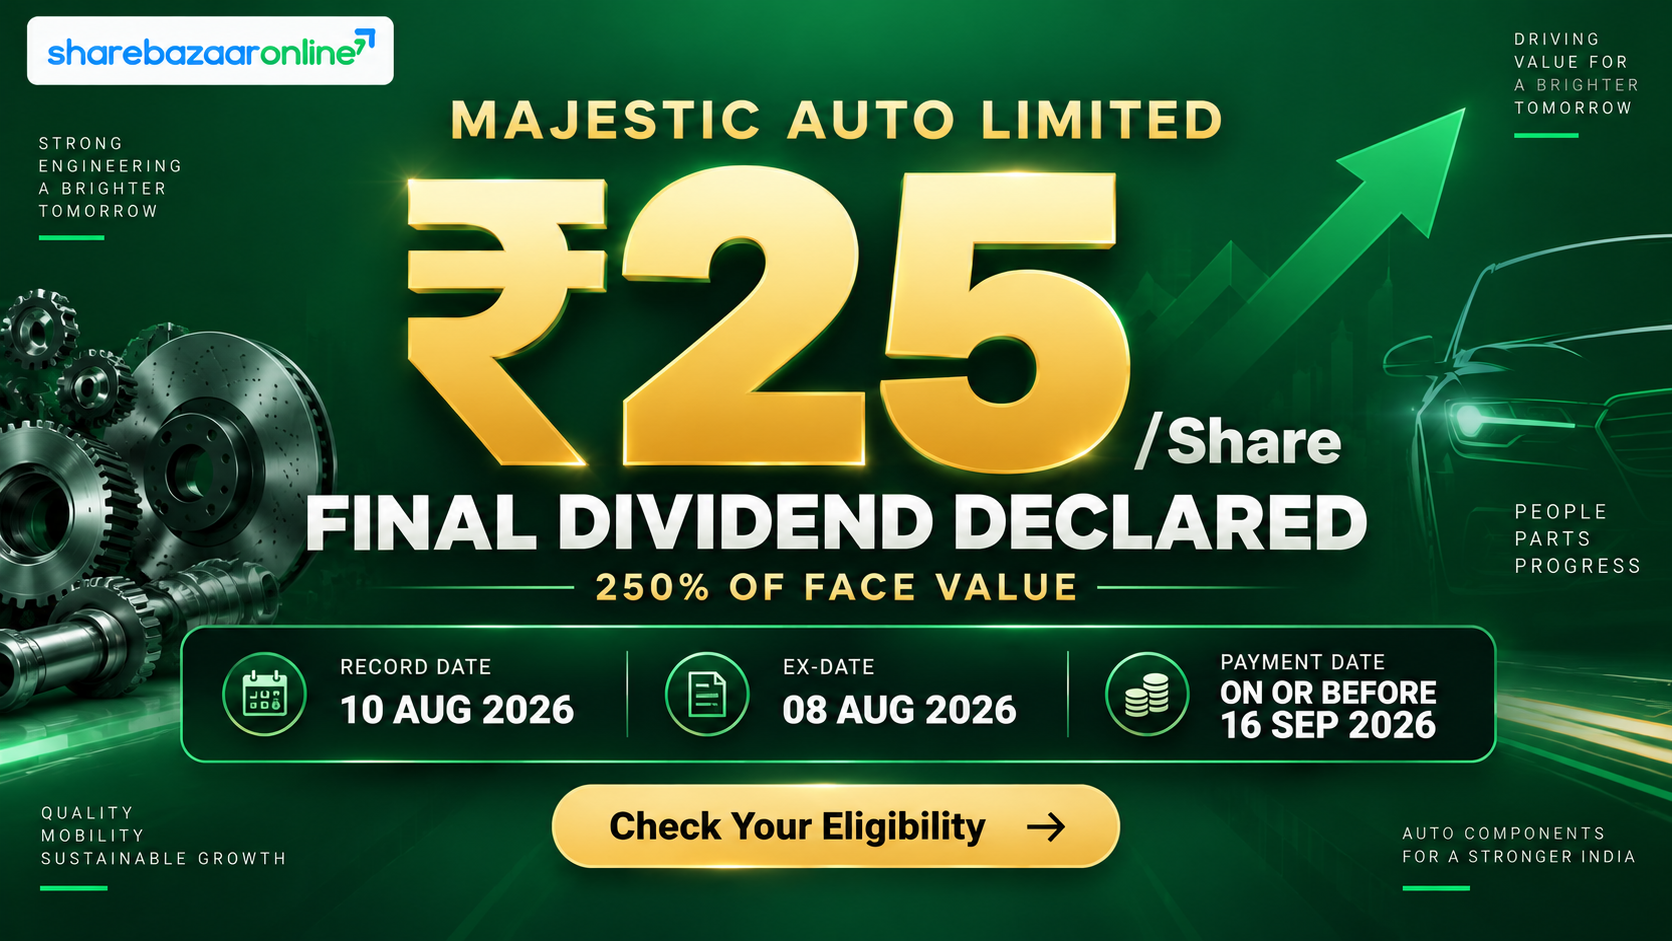
Dividend Snapshot
Company
Majestic Auto Limited
NSE: MAJESAUT • BSE: 500267 • ISIN: INE201B01022
Dividend Type
Final Dividend, FY2025-26
Recommended by Board, approved at 53rd AGM
Dividend Per Share
₹25.00
250% of face value of ₹10 per equity share
Dividend Yield (on CMP of ₹353)
7.08%
Based on final dividend only; see Yield Analysis for full-year figure
Record Date / Ex-Date
10 August 2026
Payment Date (Company Target)
On or before 16 September 2026
Dividend Announcement Summary
Majestic Auto Limited's Board of Directors, at its meeting held on May 23, 2026, recommended a final dividend of ₹25 per equity share (250% of the ₹10 face value) for the financial year ended March 31, 2026. The recommendation was placed before shareholders at the company's 53rd Annual General Meeting held via video conferencing on August 17, 2026, where it was approved along with the adoption of audited standalone and consolidated financial statements. Voting disclosures show the resolution received 100% support from promoters and a 13.64% turnout among public non-institutional investors.
Context: A Year of Two Dividends
This final dividend of ₹25/share follows a separate Special Interim Dividend of ₹35 per share (350%) approved by the Board on February 11, 2026, with a record date of February 17, 2026. That interim payout was explicitly funded by the ₹196 crore sale proceeds from the company's stake in subsidiary Emirates Technologies Private Limited (ETPL), completed on September 4, 2025. Combined, FY2025-26 shareholders are set to receive ₹60 per share in total dividends — an unusually high payout that this article examines in detail below.
Management Commentary
Management highlighted that the company remains debt-free with borrowings reduced to just ₹15 crore, and flagged ₹135 crore in planned investments tied to the resolution of its Sharan Hospitality (SHPL) exposure. The company also noted global macroeconomic factors, including currency volatility linked to geopolitical tensions, as a watch item for its treasury operations.
Key Dates Timeline
Board Recommendation
May 23, 2026
TDS Documentation Deadline
August 16, 2026
Remote E-Voting Window
August 14 – August 16, 2026
Record Date / Ex-Date
August 10, 2026
53rd AGM (Shareholder Approval)
August 17, 2026 — Approved
Payment Date (Target)
On or before September 16, 2026
Note: Record date and ex-date coincide at August 10, 2026 per company disclosures under the T+1 settlement cycle. Payment date reflects the company's disclosed target, which falls within the statutory 30-day window from the date of declaration (AGM approval) mandated under the Companies Act, 2013.
Dividend Yield Analysis
The Face-Value Yield Illusion
Headlines describing this as a "250% dividend" refer to the payout as a percentage of the ₹10 face value — not the market price. On the ₹10 face value, ₹25 per share is indeed 250%. But investors buy shares at the market price, not face value, so the number that actually matters is the real dividend yield on CMP, which is meaningfully lower.
Final Dividend Yield (CMP basis)
7.08%
₹25 ÷ ₹353 (CMP, September 3, 2026 close) × 100
Combined FY26 Yield (Final + Special Interim)
17.00%
₹60 total FY26 dividend ÷ ₹353 CMP × 100
Live CMP Re-Verification Required
All yield figures above are computed against a closing price of ₹353 (NSE/BSE, September 3, 2026). Majestic Auto's stock has shown high volatility over the past year (52-week range of roughly ₹274 to ₹501), so readers should re-check the live CMP before relying on this yield figure, as it will shift with every price movement.
Announcement-Date Yield
Intraday/closing price data specifically for May 23, 2026 (the board recommendation date) was Not Independently Verified (NIV) from primary exchange sources at the time of writing. Readers wanting the announcement-day yield should cross-check the NSE/BSE bhavcopy for that date.
Dividend History Analysis
| Financial Year | Dividend Payout Ratio | Character of Payout |
|---|---|---|
| FY2020-21 | 39% | Regular |
| FY2021-22 | 0% | No dividend |
| FY2022-23 | 206% | Payout exceeded PAT |
| FY2023-24 | 49% | Regular |
| FY2024-25 | 153% | Payout exceeded PAT |
| FY2025-26 | 68% (Screener); 67.1% (independently computed) | Special Interim + Final, asset-sale funded |
Classification: Irregular Payer
Majestic Auto's payout ratio has swung from 0% (FY22) to 206% (FY23) to 153% (FY25) to a combined ~67% in FY26. This volatility — including years where dividends exceeded reported profit — means the company does not fit the "Consistent Payer" or even "Cyclical Payer" mould. It is best classified as an Irregular Payer whose distributions are driven more by episodic asset-monetisation events (subsidiary stake sales, land parcel sales) than by a stable, board-articulated dividend policy.
Per-share dividend history prior to FY2025-26: Not Independently Verified (NIV) — third-party aggregators show materially inconsistent per-share figures for this stock across years, likely reflecting historical corporate actions. Readers should refer to the company's BSE corporate-action filings for verified per-share dividend history beyond FY2025-26.
Financial Performance Analysis
Revenue (Consolidated), FY25 → FY26
₹64 Cr → ₹35 Cr
-45.3% YoY decline
Net Profit (Consolidated), FY25 → FY26
₹9 Cr → ₹93 Cr
+933.3% YoY, but see note below
Operating Leverage Breaks Down — Read This Before the Headline Numbers
This is the single most important number in this article: revenue fell 45.3% while reported net profit rose 933%. That is not operating leverage working in the company's favour — it is a one-time item swamping the operating business. Consolidated Other Income for FY26 stood at ₹136 crore (TTM ₹151 crore), driven overwhelmingly by the gain booked on the ETPL stake sale. Core operating profit for FY26 was just ₹5 crore on ₹35 crore of sales (13% OPM), down sharply from ₹28 crore operating profit on 44% OPM in FY25. Quarterly data confirms the trend turned negative: operating profit was -₹4 crore (OPM -127%) in the March 2026 quarter and revenue from operations was reported as nil in the June 2026 quarter.
Standalone vs Consolidated Divergence
Company press disclosures cite a standalone net profit of ₹114.18 crore for FY26 (versus a standalone loss of ₹3.36 crore in FY25), while Screener's consolidated figures show ₹93 crore. The gap reflects consolidation adjustments from subsidiaries and the accounting treatment of the ETPL divestment. This article uses consolidated figures as the primary basis throughout, per standard practice, and flags standalone figures separately where cited.
5-Year Growth Context
Compounded sales growth has been negative across every window Screener tracks: -13% over 10 years, -9% over 5 years, -11% over 3 years, and -69% on a trailing-twelve-month basis. Compounded profit growth looks strong on paper (81% over 3 years, 196% TTM) but this is dominated by the same one-time other-income effect described above, not organic earnings expansion. Return on equity has averaged just 2-3% over the last 3-10 years.
Cash Flow Analysis
Reported Profits Are Opinions. Cash Is Fact.
Despite a consolidated PAT of ₹93 crore for FY26, Majestic Auto's Operating Cash Flow (OCF) was negative ₹7 crore and Free Cash Flow (FCF) was negative ₹19 crore for the year. This is a textbook example of PAT-vs-OCF divergence: the profit line is inflated by a non-cash-adjacent, one-time investing gain (sale of ETPL stake), which flows through the P&L but does not represent recurring operating cash generation.
Operating Cash Flow, FY26
-₹7 Cr
Free Cash Flow, FY26
-₹19 Cr
How Is the Dividend Actually Being Funded?
With both OCF and FCF negative for FY26, the combined ₹62.4 crore dividend outflow (final + special interim) cannot be funded from current-year operations or free cash flow. It is instead funded through asset sales — specifically the ₹196 crore ETPL stake sale (completed September 4, 2025) and a ₹143.52 crore sale deed for a Greater Noida land parcel disclosed around the AGM period — supplemented by the company's substantial investment book (₹418 crore in market value). This is a materially different sustainability profile than a dividend funded by recurring earnings or operating cash flow.
Receivables and Revenue
Debtor days have fallen to near-zero (0-4 days across recent years) alongside the collapse in operating revenue, so no adverse receivables-growth-outpacing-revenue signal is visible — the far larger flag here is the revenue collapse itself and the operating cash burn, not working-capital stress.
Balance Sheet Strength
Borrowings (Mar 2026)
₹15 Cr
Down from ₹145 Cr (Mar 2025); company is now almost debt-free
Reserves (Mar 2026)
₹658 Cr
Investments (Market Value)
₹418 Cr
Exceeds the company's total market capitalisation of ₹367 Cr
Book Value per Share
₹643
Stock trades at ~0.55x book value
Reading the Balance Sheet
The debt reduction (from ₹145 Cr to ₹15 Cr) and the investment book exceeding market cap are genuine positives, and largely explain why simplywall.st-style automated screens rate the company well on financial health despite weak profitability metrics. However, note that Total Assets also nearly halved between Mar-2025 (₹908 Cr) and TTM figures (₹696 Cr), consistent with the balance sheet being actively monetised (subsidiary stake sold, land parcel sold) rather than growing organically. Cash & bank balances specific to the standalone entity were Not Disclosed by Company in the sources reviewed; readers should refer to the FY26 Annual Report for the exact cash and bank balance line.
Dividend Sustainability Analysis
Earnings Coverage
Moderately Sustainable
Dividend Coverage Ratio (EPS ÷ Final DPS) = 3.53x on paper, but EPS is inflated by one-time gains
OCF Coverage
Unsustainable (Standalone Basis)
OCF/Dividend Outflow = -0.11x — operations alone cannot fund the payout
FCF Coverage
Unsustainable (Standalone Basis)
FCF/Dividend Outflow = -0.30x — negative free cash flow for FY26
Cash/Liquidity Coverage
Sustainable (Asset-Backed)
Investment book of ₹418 Cr is 6.7x the ₹62.4 Cr total FY26 dividend outflow
Overall Verdict: Conditionally Sustainable
Across the four-test framework, Majestic Auto's FY26 dividend clears the earnings-coverage and liquidity-coverage tests comfortably, but fails both the operating cash flow and free cash flow coverage tests on a standalone-year basis. This is a company funding a large dividend from balance-sheet monetisation (subsidiary and land sales) rather than recurring cash generation from its core leasing and facility-management business, whose revenue has been contracting sharply. The verdict is therefore Conditionally Sustainable — sustainable so long as the company continues to hold and periodically monetise its substantial investment book, but not sustainable on the strength of core operations as they currently stand. Whether this level of payout repeats in FY2026-27 depends entirely on whether similar one-time monetisation events occur again; investors should not extrapolate the FY26 yield forward without fresh confirmation each year.
Peer Comparison
| Metric | Majestic Auto Ltd | Real Estate Sector Average (NIV) |
|---|---|---|
| Dividend Yield | 7.08% (final) / 17.00% (FY26 total) | ~0.4–0.5% (NIV, aggregator-sourced) |
| ROE | 3.51% | Not Independently Verified (NIV) |
| ROCE | 5.24% | Not Independently Verified (NIV) |
| Dividend Payout Ratio | 67.1% (FY26, total dividend) | Not Independently Verified (NIV) |
| Cash/Investment Position | ₹418 Cr investments > ₹367 Cr market cap | Not Independently Verified (NIV) |
Majestic Auto does not have a clean set of directly comparable listed peers: it has transitioned from an erstwhile auto-component/moped manufacturer into a commercial real estate leasing and facility-management company with a large treasury/investment book, and its FY26 numbers are further distorted by a one-off subsidiary divestment. Traditional real estate developers, REITs, and facility-management pure-plays each capture only part of its current business mix. Rather than force an unreliable like-for-like comparison, this section reports the company's own metrics against a broad sector benchmark and leaves direct peer cells blank where verified data was not available, per our data-integrity policy.
Promoter Impact Analysis
Promoter Holding
75.00%
Unchanged for several years per shareholding pattern data
Promoter Income from Final Dividend
₹19.50 Cr
75% × ₹26.00 Cr total final dividend outflow
Full-Year Promoter Benefit
Including the earlier ₹35/share special interim dividend, promoters (holding 75% of the company) are estimated to receive approximately ₹46.80 crore in total dividend income for FY2025-26, out of a total shareholder payout of ₹62.40 crore. Minority shareholders (the remaining ~25% public float, with FII and DII holdings effectively negligible at 0.02% and 0.03% respectively) receive the balance, roughly ₹15.60 crore in aggregate. Because the payout is funded substantially from asset-sale proceeds rather than recurring profit, this represents a genuine cash distribution to all shareholders proportionate to holding, rather than a related-party-favouring structure — but the near-total promoter concentration (75%) combined with negligible institutional ownership (0.05% combined FII+DII) means minority shareholders have limited influence over capital-allocation decisions, including the decision to distribute rather than reinvest asset-sale proceeds.
Taxation Analysis
Dividends from Indian companies are taxable in the hands of shareholders under "Income from Other Sources," at the investor's applicable slab rate. Under Section 194 of the Income-tax Act, companies deduct Tax Deducted at Source (TDS) at 10% on dividend payments where the total dividend to a resident shareholder in a financial year exceeds the prescribed threshold, which has been raised to ₹10,000 for FY2025-26 onwards. Shareholders who submit Form 15G/15H (where eligible, based on total taxable income) can claim nil or lower TDS. Non-resident shareholders face TDS of up to 20% (plus surcharge and cess) unless they submit valid DTAA documentation, which Majestic Auto required by August 16, 2026 for this dividend.
Worked Example: Resident Investor, 1,000 Shares, 30% Tax Slab
| Item | Amount |
|---|---|
| Shares Held | 1,000 |
| Dividend Per Share (Final) | ₹25.00 |
| Gross Dividend | ₹25,000.00 |
| TDS @10% (Sec 194, since > ₹10,000 threshold) | ₹2,500.00 |
| Net Dividend Credited to Bank | ₹22,500.00 |
| Total Tax Liability @30% Slab | ₹7,500.00 |
| Additional Tax Payable at Filing (after TDS credit) | ₹5,000.00 |
| Net-of-Tax Dividend (Final) | ₹17,500.00 |
| Effective Post-Tax Yield on CMP | 4.96% |
A 30%-slab investor keeps roughly 70% of the gross dividend after full tax settlement, even though the immediate TDS deduction is only 10% — the balance becomes payable at the time of income tax filing.
Key Risks
1. Core Operating Revenue Collapse
Revenue from operations fell 45.3% YoY in FY26 and was reported as nil in the June 2026 quarter, raising questions about the ongoing scale of the core leasing/facility-management business.
2. Non-Repeatable Earnings Base
FY26 profit was overwhelmingly driven by a one-time ETPL stake-sale gain. Without a similar asset-sale event, FY27 earnings and dividend capacity could look very different.
3. Negative Operating & Free Cash Flow
Both OCF (-₹7 Cr) and FCF (-₹19 Cr) were negative in FY26, meaning the dividend is not backed by recurring cash generation.
4. Sharan Hospitality (SHPL) Resolution Exposure
The company has committed to a Resolution Plan involving payments of over ₹105 crore (Resolution Amount plus Additional Interest) and has already infused ₹75.79 crore in NCDs as of September 1, 2026, financed via a Securities Purchase Agreement with external funds — a new and evolving capital commitment.
5. High Non-Cash Earnings / Accrual Risk
Third-party analysis flags an elevated accrual ratio (~25%), indicating a meaningful gap between reported earnings and underlying cash profit — a signal that warrants caution when extrapolating EPS-based coverage ratios.
6. Concentrated Promoter Control, Thin Institutional Oversight
With promoters at 75% and combined FII+DII holding of just 0.05%, minority shareholders have limited checks on capital-allocation and related-party decisions.
What To Monitor
1. Core Business Revenue Trajectory
Watch whether facility-management and leasing revenue stabilises or continues toward zero in coming quarters.
2. Operating Cash Flow Trend
A return to positive OCF would materially improve the sustainability picture; continued negative OCF is a red flag for future payouts.
3. Progress on the SHPL Resolution Plan
Track further NCD infusions, timelines, and whether the ₹135 crore planned investment materialises as expected.
4. Deployment of Remaining Investment Book
The ₹418 crore investment portfolio is central to future dividend capacity — monitor how it is redeployed or further monetised.
5. FY2026-27 Dividend Policy Signal
Whether the company reverts to a smaller, earnings-linked dividend or continues distributing from asset sales will define the go-forward yield story.
6. Actual Payment Date Confirmation
Confirm via bank credit or NSDL corporate-action tracker that the ₹25/share final dividend has actually been credited by the September 16, 2026 target date.
Conclusion
Majestic Auto Limited's ₹25 per share final dividend for FY2025-26 — on top of an earlier ₹35 per share special interim dividend — adds up to one of the largest headline payouts on the Indian small-cap board this year, with a combined CMP-based yield of 17%. But the analysis above shows this is fundamentally a capital-return event tied to asset monetisation (the ETPL subsidiary stake sale and a Greater Noida land parcel sale) rather than a reflection of a growing, cash-generative operating business. Core revenue has contracted sharply, operating and free cash flow were both negative in FY26, and the company's own quarterly disclosures show operating losses in the most recent periods. Investors evaluating this dividend should weigh the genuine balance-sheet strength (near-zero debt, a large investment book) against the clear signal that the underlying leasing and facility-management operations are shrinking. This article does not make a buy, sell, or hold recommendation; readers should form their own view using the positives, negatives, risks, and monitoring points presented here, ideally alongside professional financial advice suited to their individual circumstances.
Frequently Asked Questions
What dividend has Majestic Auto Limited announced?
What is the dividend yield on Majestic Auto's final dividend?
What is the record date for the Majestic Auto final dividend?
What is the ex-date for this dividend?
When will the dividend be paid?
Who is eligible to receive this dividend?
How is this dividend taxed?
Is Majestic Auto's dividend sustainable?
What is Majestic Auto's dividend history?
What should investors monitor going forward?
Why is Majestic Auto's profit up sharply even though revenue fell?
What was the earlier special interim dividend about?
What is the promoter shareholding in Majestic Auto?
Does Majestic Auto require shareholder approval for this dividend?
Disclaimer
This article is published by ShareBazaar Online for general informational and educational purposes only. It does not constitute investment advice, a recommendation, or a solicitation to buy, sell, or hold any security. ShareBazaar Online is not registered with SEBI as an investment adviser or research analyst. Figures relating to CMP, market capitalisation, and yield are point-in-time and subject to change; readers must independently verify live prices, corporate-action dates, and financial figures from official NSE/BSE filings and the company's disclosures before making any investment decision. Past dividend payments and financial performance are not indicative of future results. Please consult a SEBI-registered investment adviser or financial professional before making investment decisions.