
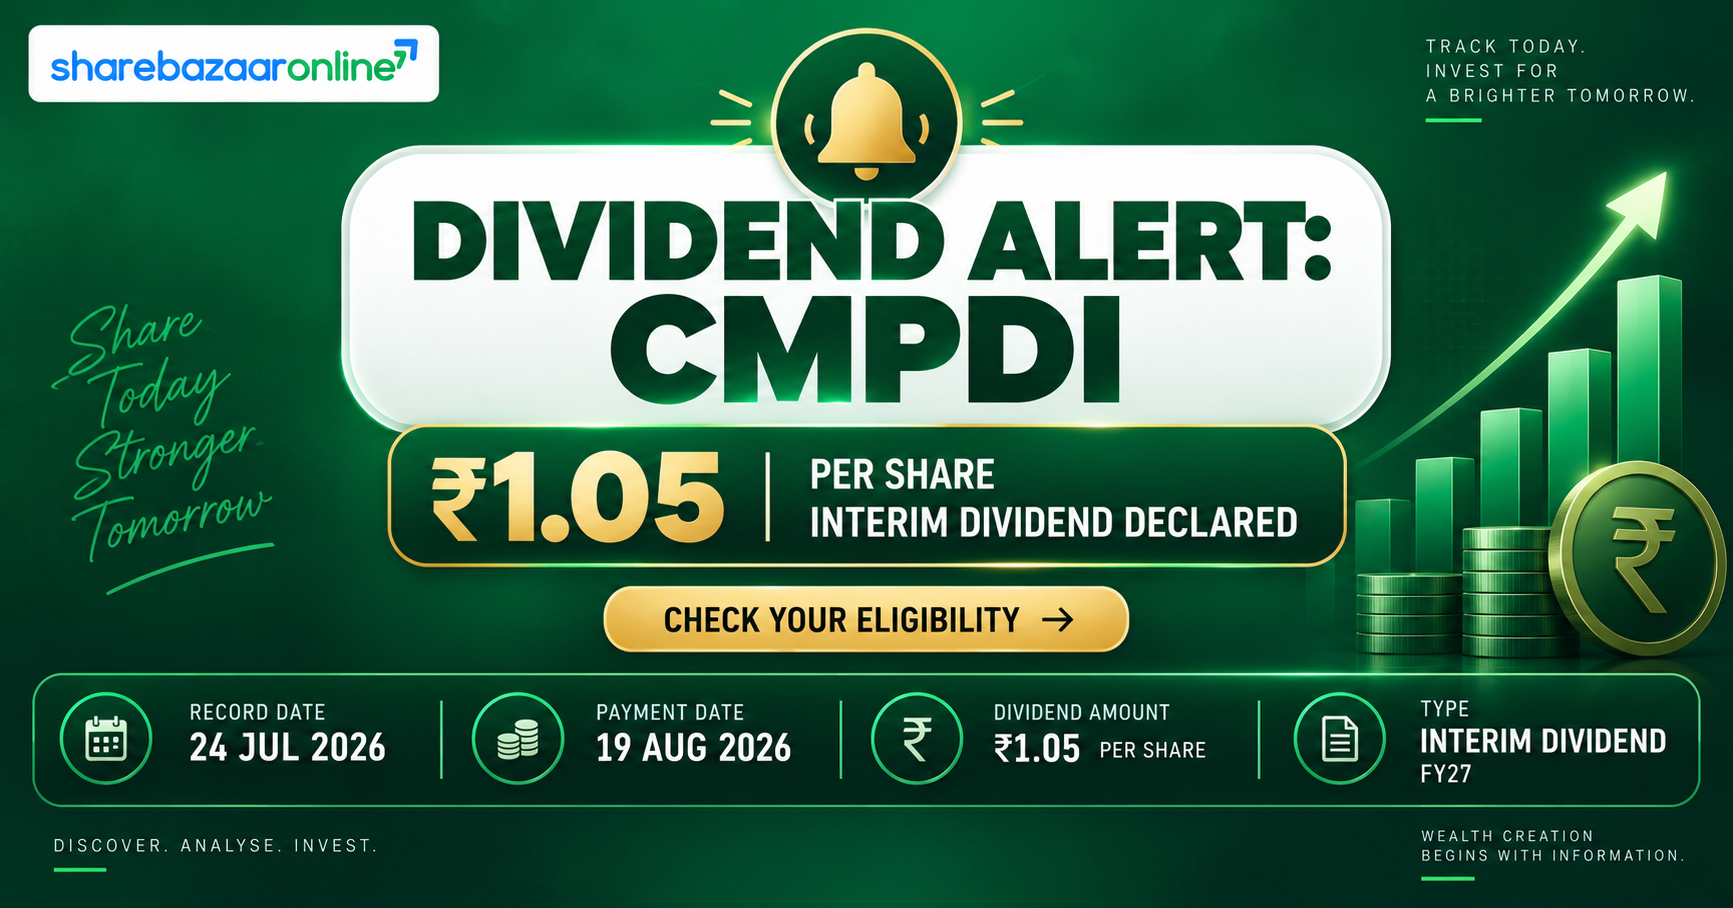
Dividend Snapshot
Company
Central Mine Planning & Design Institute Ltd (CMPDI)
NSE: CMPDI • BSE: 544739 • ISIN: INE05HV01027
Dividend Declared
₹1.05 per equity share
1st Interim Dividend, FY 2026-27 • Face Value ₹2 (52.5% of face value)
Dividend Yield (on Announcement-Date CMP)
0.41%
Based on inferred NSE close of ₹253.46 on 20-Jul-2026 (re-verify before publishing)
Dividend Yield (on Latest CMP)
0.45%
Based on ₹235.00 (Screener, 26-Aug-2026) • Re-verify live price before publishing
Record Date
Friday, 24 July 2026
Payment Date
On or before 19 August 2026
Dividend Announcement Summary
The Board of Directors of Central Mine Planning & Design Institute Limited (CMPDI), a Mini Ratna Category-I subsidiary of Coal India Limited and the country's largest coal and mineral consultancy, met on 20 July 2026 to take on record the company's un-audited standalone financial results for the quarter ended 30 June 2026 (Q1 FY 2026-27). At the same meeting, the Board declared a 1st Interim Dividend of ₹1.05 per equity share (face value ₹2 each) for FY 2026-27. This is only the second dividend event since CMPDI's shares began trading on the NSE and BSE on 30 March 2026, following the ₹1,842 crore Offer-for-Sale IPO by promoter Coal India Limited.
Since the entire IPO was an Offer for Sale, CMPDI itself raised no fresh capital from the listing — every rupee went to Coal India. That context matters for this analysis: this interim dividend is one of the earliest tests of how a newly-listed, historically wholly-owned PSU subsidiary treats its new base of public shareholders on capital distribution.
Total Dividend Outflow
₹74.97 Crore
₹1.05 × 71.40 crore shares outstanding
AGM Approval Required?
No
Interim dividends are declared by the Board alone under Section 123 of the Companies Act, 2013 and do not require shareholder approval, unlike final dividends
Key Dates Timeline
Board Meeting / Announcement Date
20 July 2026
Meeting commenced 20:00 hrs, concluded 20:40 hrs — after market close
Record Date
24 July 2026 (Friday)
Shareholders on the register as of this date were eligible
Ex-Dividend Date
24 July 2026 (Inferred)
Under India's T+1 rolling settlement, the ex-date coincides with the record date. Not separately confirmed by the company — treat as inferred, not stated fact
Payment Date
On or before 19 August 2026
Company committed to a payment deadline rather than a fixed date
Financial Year / Period
FY 2026-27, arising from Q1 (quarter ended 30 June 2026) results
Dividend Yield Analysis
A ₹1.05 per share dividend on a ₹2 face-value stock sounds substantial when expressed as "52.5% of face value" — a framing several wire services are likely to lead with. But face value is an accounting artefact from CMPDI's 1975 incorporation, not what any investor actually paid. What matters is dividend as a percentage of the price paid on the market.
Face-Value Yield (headline number)
52.50%
₹1.05 ÷ ₹2 face value × 100 — not a meaningful return metric for a market investor
Real Market-Price Yield (latest CMP)
0.45%
₹1.05 ÷ ₹235.00 × 100 — the number that actually matters to a buyer today
At 0.45%, CMPDI's real dividend yield sits well below its two closest listed PSU consultancy peers — RITES (~2.4%–3.6%) and Engineers India Limited (~0.96%–1.9%). This is not a red flag on sustainability; it largely reflects that CMPDI is a much younger listed company with a low FY26 payout ratio of roughly 12%, that its share price has re-rated sharply since the March 2026 listing (up from a 52-week low of ₹150.16 to a high of ₹283.69), and that this is only the second dividend event in its listed history. A low current yield with strong earnings coverage and a low payout ratio can be read either as conservative capital discipline or as room for the payout ratio to expand in future years — investors should watch subsequent quarters for a trend before drawing conclusions either way.
Dividend History Analysis
CMPDI was converted from a private limited company to a public limited company on 20 May 2025 and listed on the NSE and BSE only on 30 March 2026. Every dividend paid before listing went entirely to its sole shareholder, Coal India Limited, and is not comparable to a public dividend track record. The table below separates the pre-listing payout history (disclosed via standalone dividend payout ratios) from the two dividend events since listing.
| Financial Year | Dividend Payout Ratio | Status |
|---|---|---|
| FY 2020-21 | 30% | Pre-listing (paid to Coal India only) |
| FY 2021-22 | 0% | Pre-listing — no dividend |
| FY 2022-23 | 24% | Pre-listing (paid to Coal India only) |
| FY 2023-24 | 0% | Pre-listing — no dividend |
| FY 2024-25 | 0% | Pre-listing — no dividend |
| FY 2025-26 | ~12.3% (est.) | First dividend as a public company: Final Dividend ₹1.06/share, approved at the 51st AGM held 17 Aug 2026 |
| FY 2026-27 (in progress) | To be determined | 1st Interim Dividend ₹1.05/share — this article's subject event |
Payer Classification
Early-Stage Payer (as a listed company)
With only two dividend declarations since public listing, CMPDI has not yet established a track record long enough to classify as Consistent, Irregular or Cyclical in the way an investor would judge a company with 5-10 years of public dividend history. The pre-listing payout pattern (irregular, driven by a single promoter shareholder's cash needs) is not a reliable guide to future public-market dividend policy.
Financial Performance Analysis
Q1 FY27 Revenue
₹481.37 Cr
+17.62% YoY (Q1 FY26: ₹409.25 Cr)
Q1 FY27 Net Profit (PAT)
₹116.27 Cr
+53.88% YoY (Q1 FY26: ₹75.56 Cr)
Q1 FY27 shows healthy positive operating leverage on a standalone basis: revenue grew 17.62% YoY while total expenses rose just 4.87% (₹343.88 Cr vs ₹327.90 Cr), and other income jumped 61.32% YoY (₹22.65 Cr vs ₹14.04 Cr) on the back of a larger cash and investment base post-IPO listing. As a result, profit before tax grew 67.88% YoY — almost 4x the pace of revenue growth. Operating margin (per Screener quarterly data) expanded from roughly 22% in Q1 FY26 to about 30% in Q1 FY27.
This quarter's strength should be read against a more mixed full-year FY26 picture, however. For FY 2025-26 as a whole, standalone revenue grew 10.17% YoY (₹2,316.53 Cr vs ₹2,102.76 Cr) but net profit declined 8.07% YoY (₹613.18 Cr vs an estimated ₹667 Cr in FY25) — a case of revenue rising while profit fell, driven by total expenses growing roughly 22% YoY (₹1,539 Cr vs ₹1,262 Cr), materially outpacing revenue growth. This compressed the FY26 operating margin to about 34% from roughly 40% in FY25. The exact FY26 standalone cost break-up beyond quarterly filings (e.g. the precise employee-cost and other-expense split for the full year) is Not Disclosed by Company in the source filings reviewed for this article and is flagged NIV.
A related base-effect distortion: Q4 FY26 (Jan-Mar 2026) standalone net profit fell 32.19% YoY to ₹187.82 Cr from ₹276.96 Cr in Q4 FY25, even as Q4 FY26 revenue rose 11.69% YoY. This decline reflects an unusually strong Q4 FY25 base rather than a deterioration in the underlying quarterly run-rate — readers comparing year-over-year profit headlines around this stock should check which base period is being used before drawing conclusions.
Cash Flow Analysis
Reported profit is an opinion shaped by accounting judgement; cash is a fact. CMPDI's standalone cash flow statement for FY26 supports the profit figures reasonably well, though a structural receivables issue is worth flagging.
FY26 Operating Cash Flow (OCF)
₹716 Cr
vs FY25 OCF of ₹671 Cr • OCF/Operating Profit ratio: 130% (FY26) vs 102% (FY25)
FY26 Free Cash Flow (FCF)
₹652 Cr
vs FY25 FCF of ₹629 Cr • FCF comfortably exceeds reported net profit of ₹613.18 Cr
Notably, FY26 OCF (₹716 Cr) exceeds FY26 reported PAT (₹613.18 Cr) — a positive quality-of-earnings signal that suggests profits are being converted into real cash rather than sitting in receivables or one-time non-cash gains. This is the opposite of a red-flag pattern (PAT positive but OCF weak) and is worth highlighting explicitly as a strength.
The one caution: CMPDI carries persistently high debtor days of 169 (FY26), and the independent auditor's limited review report for Q1 FY27 flags ₹114.81 crore of old debtor balances (over one year outstanding) owed by Coal India and its subsidiaries, up from ₹111.97 crore in the prior year, with the auditor noting the impact of any eventual reconciliation "is not currently ascertainable." Since roughly 68% of CMPDI's revenue comes from the CIL group itself, this related-party receivables overhang is a structural feature of the business model rather than a one-off event, and is worth monitoring even though working capital days have improved from 135 to 99.2 over FY25-26.
How Is This Dividend Funded?
Based on the disclosed FY26 cash flow statement, this ₹74.97 crore interim dividend outflow is funded through current operating cash generation, not asset sales or borrowings — FY26 standalone OCF of ₹716 crore is nearly ten times the size of this interim outflow.
Balance Sheet Strength
Total Borrowings (FY26)
₹1 Cr
Effectively debt-free on a standalone basis
Equity Capital + Reserves (FY26)
₹2,283.24 Cr
₹142.80 Cr equity capital + ₹2,140.44 Cr other equity
CMPDI's balance sheet is asset-light and effectively free of debt, consistent with a pure consultancy business model that does not require heavy capital investment. Book value per share stands at approximately ₹32, against which the stock trades at roughly 7.3x price-to-book — a premium that reflects the market's view of CMPDI's high return ratios (ROE 28.4%, ROCE 38.1%) rather than tangible asset backing.
Cash & Bank Balances
Not Disclosed by Company
The standalone balance sheet summary available for this article does not break out a separate cash-and-investments line (shown as ₹0 in the summarized "Investments" row, with cash embedded within a combined "Other Assets" figure of ₹2,975 Cr for FY26). A precise standalone cash-and-bank figure requires the full annual report schedules and is flagged NIV pending that reconciliation. Independent secondary estimates around the March 2026 IPO cited combined cash and bank deposits in the ₹1,000+ crore range, but this pre-dates the FY26 year-end audited balance sheet and should not be treated as current.
Dividend Sustainability Analysis
Test 1: Earnings Coverage
PASS — 8.10x (FY26 basis)
FY26 EPS ₹8.59 ÷ FY26 final DPS ₹1.06. On a standalone Q1 FY27 basis, this interim's coverage is 1.55x (Q1 EPS ₹1.63 ÷ DPS ₹1.05) — note this single-quarter figure is not annualized and should not be read as a full-year coverage ratio.
Test 2: OCF Coverage
PASS — 9.6x
FY26 standalone OCF of ₹716 Cr ÷ this interim's ₹74.97 Cr outflow
Test 3: FCF Coverage
PASS — 8.7x
FY26 standalone FCF of ₹652 Cr ÷ this interim's ₹74.97 Cr outflow. No capex cycle concern given the asset-light model.
Test 4: Liquidity / Cash Coverage
Not Disclosed by Company
Precise standalone cash-and-bank balance not separately available in the reviewed filings; flagged NIV rather than estimated
Overall Classification
Sustainable
Three of the four coverage tests are strongly positive and independently verifiable from disclosed FY26 financials; the fourth (liquidity coverage) could not be independently verified from the specific balance-sheet line items available and is marked NIV rather than assumed. Given the company's debt-free status, strong OCF/FCF generation and low FY26 payout ratio (~12%), the overall picture supports a Sustainable classification, though this rests on continued collection discipline on the large related-party receivable balance noted in the Cash Flow Analysis section above.
Peer Comparison
CMPDI's closest listed peers, per its own IPO prospectus, are the two other listed PSU engineering/consultancy majors — RITES Limited (Ministry of Railways) and Engineers India Limited (Ministry of Petroleum & Natural Gas).
| Metric | CMPDI | RITES | Engineers India (EIL) |
|---|---|---|---|
| Dividend Yield | ~0.45% | ~2.4%–3.6% | ~0.96%–1.9% |
| ROE | 28.4% | ~15.3%–15.4% | ~17.7%–22.0% |
| ROCE | 38.1% | ~19.5% | ~23.4% |
| P/E (TTM) | ~25.6x | ~24x–26x | ~19x–21x |
| Promoter Holding | 85.00% | ~72.2% | ~51.3% |
| Debt Position | Near debt-free | Near debt-free | Near debt-free |
Peer figures are sourced from secondary market-data providers as of various dates in 2026 (flagged NIV for exact same-day comparability) and should be independently re-verified before publication, since dividend yields in particular move with each provider's price snapshot date.
CMPDI screens as the more profitable operator of the three on both ROE and ROCE, consistent with its RHP-disclosed operating margin advantage (~40% vs EIL's ~16.6% and RITES' ~23.8%, per pre-IPO comparisons). But its dividend yield trails both peers meaningfully, largely because CMPDI is a much newer public company with a far lower current payout ratio (~12% vs RITES' payout ratio near or above 90-100% in some years). Investors should not read the yield gap alone as a sign of weaker shareholder orientation — CMPDI's promoter (Coal India) also has an 85% economic interest in every rupee distributed, which may itself shape future payout policy in ways smaller-promoter peers like EIL (51.3% promoter) do not face.
Promoter Impact Analysis
Promoter (Coal India Ltd) Holding
85.00%
Unchanged between Mar 2026 and Jun 2026 shareholding filings
Promoter Dividend Income
₹63.72 Cr
85.00% × ₹74.97 Cr total outflow
Non-Promoter (Public + Institutional) Dividend Income
₹11.25 Cr
Split across FIIs (0.50%), DIIs (7.85%), Government entities (0.00%) and retail/other public shareholders (6.64%) as per the June 2026 shareholding pattern, covering 76,622 shareholders.
Because Coal India retained an 85% stake through the OFS structure, the overwhelming majority of this dividend — nearly ₹64 crore of the ₹75 crore total — effectively flows back to the Government of India via its majority ownership of Coal India itself. Minority shareholders who bought into the March 2026 IPO or subsequently in the secondary market collectively receive roughly ₹11.25 crore from this interim distribution alone. This concentration is a standard feature of recently-listed PSU OFS issues and is not, by itself, a governance concern, but it does mean float-adjusted yield calculations (dividend received per rupee of publicly-traded market cap) differ materially from headline yield figures for readers building portfolio-level cash-flow models.
Taxation Analysis
Since April 2020, dividends from Indian companies are taxable in the hands of the shareholder at their applicable income-tax slab rate; the erstwhile Dividend Distribution Tax paid by the company no longer applies. CMPDI (or its registrar) is required to deduct TDS under Section 194 of the Income Tax Act at 10% if the total dividend paid to a resident individual shareholder exceeds ₹5,000 in a financial year (no TDS threshold trigger applies to dividends below this level, though the income itself remains taxable and must be disclosed). Non-resident shareholders face TDS at 20% (plus applicable surcharge and cess), subject to relief under an applicable Double Taxation Avoidance Agreement.
Worked Example — Illustrative ₹10 Per Share Dividend at 30% Slab
| Shares Held | 1,000 |
| Illustrative Dividend Per Share | ₹10.00 |
| Gross Dividend | ₹10,000 |
| Tax at 30% Slab | ₹3,000 |
| Net Dividend in Hand | ₹7,000 |
Applied to This Actual Interim Dividend (₹1.05/share) at 30% Slab
| Gross Dividend on 1,000 Shares | ₹1,050.00 |
| Tax at 30% Slab | ₹315.00 |
| Net Dividend in Hand | ₹735.00 |
Effective post-tax yield for a 30%-slab investor on the latest CMP works out to roughly 0.31% (0.45% gross yield × 70% retention). Actual outcomes vary by an investor's total taxable income, applicable surcharge, cess, and whether TDS has already been deducted at source.
Key Risks
1. Extreme Client Concentration
Roughly 68% of revenue and, per the RHP, 93.8%–95.8% of top-10-client revenue comes from the Coal India group. Any change in CIL's capex plans, mine expansion pace or internal consultancy sourcing decisions would directly hit CMPDI's revenue.
2. Rising Related-Party Receivables
₹114.81 crore of debtor balances against CIL & subsidiaries remain outstanding for over a year, up from ₹111.97 crore, with the auditor unable to ascertain the eventual reconciliation impact.
3. High Debtor Days
Standalone debtor days stood at 169 in FY26 — a structurally elevated figure that ties up working capital even as collections have improved from prior years.
4. Coal-Sector Structural Demand Risk
CMPDI's near-term growth case rests heavily on Coal India's planned capacity build-out (~787 MT across 50 mines by FY2030). Any acceleration of India's energy transition away from coal beyond the medium term could compress CMPDI's addressable consultancy pipeline.
5. Newly Listed, Thin Public Float
With promoter holding at 85% and only 6.64% direct public holding, free-float liquidity is comparatively thin, which can amplify share-price volatility around news events including dividend announcements (the stock moved over 7% intraday around this announcement).
6. Limited Public Dividend Track Record
With only two dividend events since listing, there is no multi-year public payout pattern to validate consistency, growth trajectory, or resilience through a down-cycle.
What To Monitor
1. Trend in the Related-Party Receivable Balance
Watch subsequent quarterly filings for whether the ₹114.81 crore CIL-group debtor balance shrinks or continues to age past the circular-mandated reconciliation timelines.
2. Full-Year FY27 Payout Ratio Trend
Whether the combined FY27 interim-plus-final payout ratio expands meaningfully from FY26's ~12% level, which would be the clearest signal of an evolving public-company dividend policy.
3. Employee Cost and Other-Expense Trajectory
FY26's ~22% expense growth against ~10% revenue growth compressed margins; investors should track whether this normalizes or persists into FY27.
4. Coal India Group Order Flow and Capex Announcements
Given the ~68% revenue dependency, any update on CIL's 50-mine, 787 MT expansion pipeline is a direct forward indicator for CMPDI.
5. Government/Coal India Stake Sale Signals
As with most recent PSU OFS listings, any further stake dilution by Coal India would affect free float, index inclusion prospects and near-term supply-demand dynamics for the stock.
Conclusion
CMPDI's 1st Interim Dividend of ₹1.05 per share for FY 2026-27 is a modest-yield but well-covered distribution from a debt-free, high-margin PSU consultancy that has generated more operating cash than reported profit in each of the last two fiscal years. The dividend is comfortably funded from current earnings rather than reserves or borrowings, with FY26 OCF and FCF each covering the outflow more than eight times over. At the same time, this remains an early data point: CMPDI has been a public, dividend-paying-to-minority-shareholders company for less than five months, its receivables from the Coal India group are rising and structurally elevated, and roughly 85% of every dividend rupee still returns to its state-owned promoter. Whether this interim dividend marks the start of a more generous, consistent public payout policy or simply reflects a conservative first step will only become clear over the next several quarterly and annual declarations.
This analysis presents facts, computed ratios and disclosed risks only. It does not constitute, and should not be read as, a Buy, Sell or Hold recommendation. Readers should form their own view or consult a SEBI-registered investment adviser.
Frequently Asked Questions
What dividend has CMPDI announced?
What is CMPDI's dividend yield on this dividend?
What was the record date for CMPDI's 1st interim dividend?
What was the ex-dividend date?
When was CMPDI's interim dividend paid?
Who was eligible for CMPDI's 1st interim dividend?
How is CMPDI's dividend taxed for Indian resident shareholders?
Is CMPDI's dividend sustainable?
What is CMPDI's dividend history?
What should investors monitor going forward?
Why is the dividend described as "52.5% of face value" in some headlines?
Does this dividend require shareholder (AGM) approval?
How much of this dividend goes to Coal India as promoter?
How does CMPDI's dividend yield compare with its listed peers?
Disclaimer
This article is prepared for general informational and educational purposes only and is based on publicly available corporate filings, exchange disclosures and secondary market-data sources believed to be reliable as of the date of research. ShareBazaarOnline is not a SEBI-registered investment adviser or research analyst, and nothing in this article constitutes investment advice or a recommendation to buy, sell or hold any security. Live market prices, dividend yields and peer metrics are subject to change and must be independently re-verified before any investment or publishing decision. Certain figures marked "Not Disclosed by Company" or "NIV" reflect information not independently available to us at the time of writing and should not be treated as zero or as confirmed facts. Past dividend history, including pre-listing distributions to the sole promoter shareholder, is not indicative of future dividend policy. Readers should consult a SEBI-registered investment adviser before making investment decisions. Investments in securities are subject to market risk.