
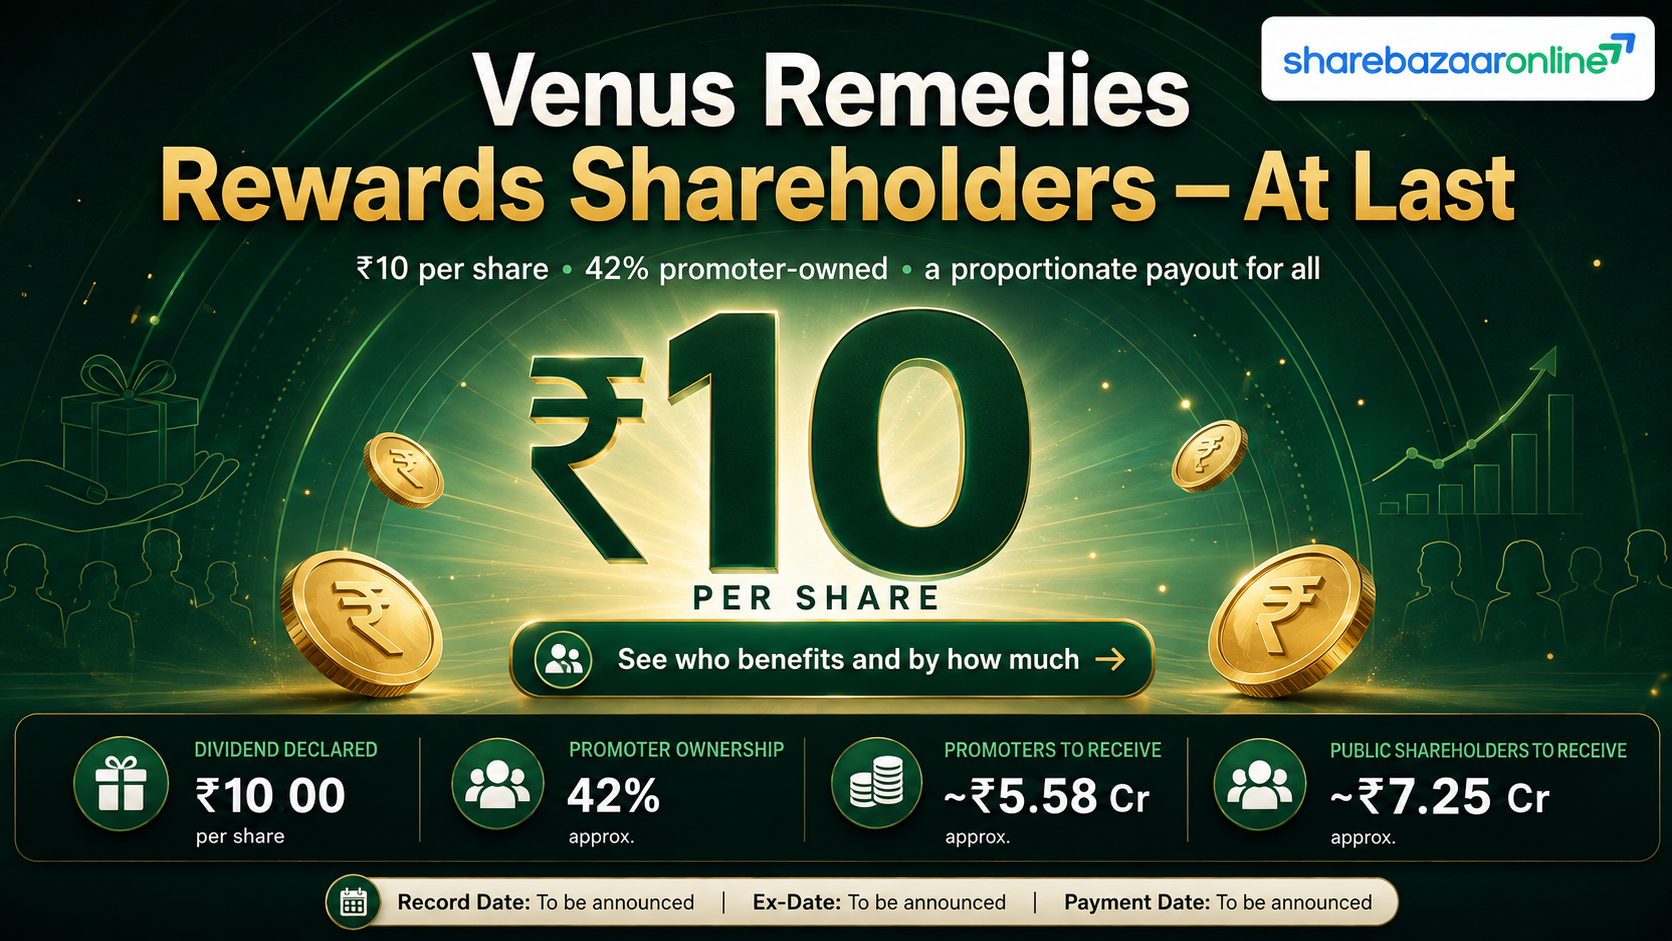
Dividend Snapshot
Venus Remedies Limited (NSE: VENUSREM, BSE: 526953) has recommended a final dividend of ₹10 per equity share for the financial year 2025-26 — a payout equal to 100% of the ₹10 face value. The most striking part of this Venus Remedies dividend is not the headline percentage but the timing: exchange dividend records show the company had not paid a dividend since 2013, making this its first shareholder payout in roughly 13 years. The revival lands in a record year — consolidated net profit more than doubled to ₹102.78 crore and the balance sheet is now effectively debt-free.
Dividend At A Glance
- Dividend Type: Final Dividend
- Dividend Per Share: ₹10
- Dividend Percentage: 100% (on face value ₹10)
- Financial Year: FY2025-26
- Announcement Date: 26 May 2026
- Record Date: 7 August 2026
Key Numbers
- Latest Price (17 Aug 2026): ₹1,803
- Dividend Yield at CMP: ~0.55%
- Total Dividend Outflow: ~₹13.37 crore
- Dividend Payout Ratio: ~13% of PAT
- Earnings Coverage: 7.69x (EPS ₹76.89)
- Promoter Holding: 41.76%
The one-line takeaway: A "100% dividend" sounds enormous, but because it is calculated on a ₹10 face value, the real cash return works out to roughly 0.55% at the current market price of ₹1,803. This is a token, symbolic dividend from a company in growth mode — not an income stock. Its true significance is the signal it sends: after a long turnaround from heavy losses and high debt, the board is confident enough to reward shareholders again.
Dividend Announcement Summary
At its board meeting held on Tuesday, 26 May 2026 (the meeting began at 3:15 pm and concluded at 9:35 pm), the Board of Directors of Venus Remedies Limited considered and recommended a final dividend of ₹10 per equity share (100%) on shares of face value ₹10 each for FY2025-26. The recommendation was made alongside the company's audited annual results, which the statutory auditor J.K. Jain & Associates certified with an unmodified (clean) opinion for both standalone and consolidated accounts.
What The Board Approved
- Final dividend of ₹10/share, subject to shareholder approval at the 37th AGM
- Audited FY2025-26 results (standalone & consolidated)
- 37th AGM scheduled for Thursday, 20 August 2026 via video conferencing
- Record date of Friday, 7 August 2026 under Regulation 42
- Payment within 30 days of the AGM date, net of applicable TDS
Market Reaction
The dividend and results were announced after market hours on 26 May 2026 (closing price that day: ₹1,161 on NSE). On the next trading session, 27 May 2026, the stock locked in a 5% upper circuit at ₹1,219.10, touching a fresh all-time high as investors reacted to the sharp jump in profitability and the surprise return of dividends.
Approval status: Because this is a final dividend, it is a recommendation that becomes binding only after shareholders approve it at the 37th Annual General Meeting on 20 August 2026. Editors should update this language once AGM approval is confirmed.
Key Dates Timeline
Venus Remedies Dividend Dates FY2025-26
- Announcement / Board Meeting: 26 May 2026
- Record Date: 7 August 2026 (Friday) — to determine eligible shareholders
- Ex-Dividend Date: 7 August 2026 (as reflected by exchange/data providers under the T+1 settlement cycle, where ex-date typically coincides with record date)
- Annual General Meeting (37th AGM): 20 August 2026 (Thursday)
- Payment Date: Not disclosed as a specific date — the company has stated payment will be made within 30 days from the AGM date, i.e. on or before approximately 19 September 2026
To have been eligible for this dividend, an investor needed to hold Venus Remedies shares as of the record date of 7 August 2026. The exact ex-date should be confirmed against the official NSE/BSE corporate-action circular, as the ex-date drives eligibility in practice. The specific payment date is not fixed in the filing; the company has committed only to a statutory outer limit of 30 days post-AGM, subject to shareholder approval and deduction of tax at source.
Dividend Yield Analysis
This is where the "100% dividend" headline needs a reality check. The 100% figure is calculated on the ₹10 face value — it does not mean a 100% return on your investment. The dividend yield — the cash return relative to the price you actually pay — is far more modest.
Yield At Different Prices
- At latest price ₹1,803: yield ~0.55%
- At announcement-day price ₹1,161: yield ~0.86%
- At post-results high ₹1,219: yield ~0.82%
- Pharma sector average yield: ~0.8% (benchmark)
The Math, Simply
Dividend Yield = (Dividend ÷ Price) × 100. At ₹10 ÷ ₹1,803, that is 0.55%. Even at the lower announcement-day price of ₹1,161, it was only 0.86%. Because the share price has run up sharply over the past year, the yield sits below the pharma sector average despite the eye-catching 100% label.
Why the yield is low is important: it is not because the dividend is weak — it is because the stock has re-rated dramatically. Venus Remedies shares are up roughly 200%+ over the past year, so the same ₹10 dividend now buys a much smaller percentage return. A rising denominator (price), not a shrinking numerator (dividend), is compressing the yield. All yield figures are price-dependent and must be re-verified against the live market price before acting.
Dividend History Analysis
This is the single most important context that wire-service coverage tends to miss. Venus Remedies is not a consistent dividend payer resuming a routine payout — it is a company returning to the dividend list after well over a decade of paying nothing.
Dividend Payout History (Consolidated)
| Financial Year | Dividend Payout Ratio | Dividend Paid |
|---|---|---|
| FY2013 (last old dividend) | — | ₹3/share |
| FY2015 to FY2025 | 0% every year | Nil |
| FY2026 (current) | ~13% | ₹10/share |
Why Dividends Stopped
Between FY2017 and FY2020, Venus Remedies reported consecutive losses (net losses of roughly ₹17 cr, ₹31 cr, ₹29 cr and ₹10 cr) while carrying heavy borrowings that peaked near ₹320 crore. In that phase, cash was directed toward survival and debt reduction, not shareholder payouts.
Why It Returned Now
The company swung back to profit in FY2021 (~₹62 cr), slashed borrowings to near zero, and in FY2026 delivered a record ₹103 crore consolidated profit. Debt-free and cash-generative, the board could finally afford to resume dividends — and did so at more than triple the old ₹3 rate.
Classification: Irregular / Reviving Payer. With an 11-year gap at 0% payout, Venus Remedies does not yet qualify as a consistent dividend payer. Whether this becomes the start of a regular dividend track record — or remains a one-off gesture — is the key thing for income-focused investors to watch in FY2027.
Financial Performance Analysis
Consolidated Results: FY2026 vs FY2025
| Metric (₹ crore) | FY2025 | FY2026 | Growth |
|---|---|---|---|
| Revenue from Operations | 652.89 | 769.60 | +17.9% |
| EBITDA | 84.48 | 159.86 | +89.2% |
| Profit Before Tax (core) | 61.91 | 134.16 | +116.7% |
| Net Profit (PAT) | 45.31 | 102.78 | +126.8% |
| EPS (₹) | 33.89 | 76.89 | +126.9% |
| Operating Margin (OPM) | 12.9% | 20.8% | +7.8 pp |
Operating Leverage: The Real Engine
Notice how the numbers accelerate as you go down the table: revenue grew 18%, but EBITDA grew 89% and profit grew 127%. This is textbook operating leverage — costs grew far slower than sales. Cost of materials rose only +11.2% (well below the 17.9% sales growth), employee cost +10.2%, and R&D spend was essentially flat (+0.5%). When revenue outruns costs like this, margins expand and profit multiplies.
Two Earnings-Quality Points Worth Flagging
1. The profit jump is genuine, not "other income." Other income actually fell 21% (from ₹15.95 cr to ₹12.58 cr). So the earnings surge came from the core injectables business, not from treasury or one-off gains.
2. The base year was flattered, not the current year. FY2025 profit included a ₹9.91 crore exceptional gain; FY2026 had none. That means the 127% headline growth is, if anything, understated relative to the clean underlying improvement — a positive quality signal rather than a red flag.
Cash Flow Analysis
Reported profit is an accounting opinion; cash is a fact. Here the two agree, which is reassuring. In FY2026, Venus Remedies converted its ₹103 crore accounting profit into even more operating cash.
Cash Flow Snapshot (Consolidated FY2026)
- Operating Cash Flow (OCF): ₹155.77 cr
- Free Cash Flow (FCF): ~₹118 cr
- Cash from Investing: (₹181.57 cr)
- Cash from Financing: (₹3.12 cr)
- Cash conversion (CFO/OP): ~129%
Is The Dividend Cash-Funded?
Yes, comfortably. Against a dividend outflow of just ₹13.37 crore, operating cash flow of ₹155.77 crore covers it about 11.7 times over, and free cash flow of ~₹118 crore covers it ~8.8 times. The dividend is funded entirely out of current-year operations — no need to dip into reserves or borrow.
Where Did The Cash Go?
The large investing outflow of ₹181.57 crore is the key story. Roughly ₹152.56 crore went into mutual funds and fixed deposits, and capital work-in-progress rose from ₹26 cr to ₹51 cr. In other words, the company generated strong cash but chose to park most of it in investments and reinvest in assets rather than pay it out — which is exactly why the modest 13% dividend payout looks conservative. Closing cash and equivalents stood at ₹25.11 crore, with a much larger investment book behind it.
Balance Sheet Strength
The transformation of the balance sheet is the reason this dividend is even possible. A company that once carried more than ₹300 crore of debt now runs effectively debt-free.
Balance Sheet (Consolidated, Mar 2026)
- Total Equity: ₹663.75 cr
- Book Value: ~₹497 per share
- Borrowings: ~₹12 cr (mostly lease liabilities)
- Cash + Bank + Current Investments: ~₹103.41 cr
- Non-current Investments: ₹163.82 cr
- Total Assets: ₹853.70 cr
What It Means For The Dividend
With borrowings of only ~₹12 crore (largely accounting lease liabilities rather than real financial debt) against liquid resources of over ₹103 crore in cash and current investments, the company is in a net-cash position. Debt is not rising to fund dividends. Liquid resources alone cover the ₹13.37 crore payout about 7.7 times; including longer-dated investments, coverage rises to roughly 20 times.
Dividend Sustainability Analysis
Four-Test Sustainability Scorecard
| Test | Coverage | Verdict |
|---|---|---|
| Earnings (PAT ₹102.78 cr) | 7.7x | Strong |
| Operating Cash Flow (₹155.77 cr) | 11.7x | Strong |
| Free Cash Flow (~₹118 cr) | 8.8x | Strong |
| Liquidity (cash + current inv ₹103 cr) | 7.7x | Strong |
Verdict: Sustainable
On every affordability test — earnings, operating cash, free cash and liquidity — the ₹13.37 crore payout is covered many times over. At just 13% of profit, the payout leaves an enormous buffer, so the company could comfortably maintain or grow it. The one honest caveat is consistency, not affordability: after an 11-year gap, this is a reviving payer, and a single year does not establish a dependable dividend track record. The dividend is highly sustainable in size; its continuity is what remains to be proven.
Peer Comparison
Venus Remedies vs Sector Benchmarks
| Metric | Venus Remedies | Pharma Sector (benchmark) |
|---|---|---|
| Dividend Yield | ~0.55% | ~0.8% average |
| Dividend Payout Ratio | ~13% | Varies (20-40% typical for mature payers) |
| ROE (last year) | ~16.8% | Not Independently Verified |
| ROCE | ~21.7% | Not Independently Verified |
| Net Debt Position | Net cash | Not Independently Verified |
Venus Remedies is a small-cap injectables specialist, not directly comparable to large-cap dividend payers like Sun Pharma, Cipla or Dr. Reddy's, which carry multi-year, more predictable payout records and larger scale. Against the broad pharma sector, Venus offers a below-average yield (0.55% vs ~0.8%) and a conservative payout (~13%) — consistent with its profile as a re-rating growth stock resuming token dividends rather than an established income name. Its ROE (~16.8%) and ROCE (~21.7%) for FY2026 are healthy for the sector. Exact peer-by-peer dividend yields and returns should be verified against live data before publication; sector-specific peer cells are marked Not Independently Verified (NIV) accordingly.
Promoter Impact Analysis
Who Receives The ₹13.37 Crore
- Promoters (41.76%): ~₹5.58 cr
- Public shareholders (54.24%): ~₹7.25 cr
- FIIs (2.80%): ~₹0.37 cr
- DIIs (1.20%): ~₹0.16 cr
Is It Skewed To Promoters?
No. The promoter family (the Chaudhary family) holds 41.76%, so it receives a proportionate ₹5.58 crore — less than the ₹7.25 crore flowing to public shareholders. Crucially, promoter holding has been stable at 41.76% for several quarters with no recent pledging-driven distortion visible in the shareholding pattern, so this is an ordinary pro-rata distribution rather than a promoter-tilted payout.
Because the payout is small and proportionate, the dividend is best read as a confidence signal from insiders — a family that owns 42% choosing to formally reward all shareholders after 13 years — rather than a mechanism to extract cash. Institutional interest (FII + DII combined ~4%) has been inching up, another sign the turnaround is drawing attention.
Taxation Analysis
How Dividends Are Taxed In India
Since April 2020, dividends are taxed in the hands of the investor, not the company. The dividend is added to your total income and taxed at your applicable income-tax slab rate. In addition, the company must deduct TDS at 10% under Section 194 if your total dividend from that company in the year exceeds ₹5,000 (the rate is higher if PAN is not provided). This TDS is adjustable against your final tax liability when you file your return.
Worked Example: 1,000 Shares, 30% Slab
- Shares held: 1,000
- Dividend per share: ₹10
- Gross dividend: ₹10,000
- TDS @10% (since > ₹5,000): ₹1,000 deducted at source
- Total tax @30% slab: ₹3,000
- Net dividend in hand (after full tax): ₹7,000
- Effective post-tax yield (at CMP ₹1,803): ~0.39% (gross ~0.55%)
For a high-slab investor, the already-modest 0.55% gross yield falls to roughly 0.39% after tax. This reinforces the point that the appeal of Venus Remedies is capital appreciation and the turnaround story, not dividend income. Tax rules vary by individual circumstances — investors should consult a qualified tax adviser.
Key Risks
- Dividend consistency is unproven. After an 11-year gap at 0% payout, there is no guarantee this becomes a recurring dividend. Income investors should not assume repetition.
- Sluggish long-term sales growth. Five-year revenue CAGR is only ~7%. The FY2026 surge is impressive but must prove durable rather than a single strong year.
- Rich valuation. The stock trades at roughly 3.6x book value and has risen ~200%+ in a year; a growth disappointment could de-rate the shares sharply, and any dividend is a tiny cushion against that.
- Export and regulatory concentration. Exports crossed ₹590 crore with heavy reliance on Latin America (~24%) and Europe (~23%); currency swings, tender timing, and overseas GMP/regulatory actions can dent margins.
- European subsidiary uncertainty. The investment in Venus Pharma GmbH remains pending formal share allotment amid an ongoing restructuring of European operations, an area still being advised by external consultants.
- Small-cap liquidity and volatility. As a small-cap (₹2,400 crore market cap), the stock can be volatile, and prices/yields can move quickly.
What To Monitor
- FY2027 dividend decision. Whether the board repeats (or raises) the dividend next year is the single biggest test of whether this is a durable policy or a one-off.
- Sustained margin trajectory. Watch if the ~21% operating margin holds. The FY2026 leap was cost-driven; monitor whether material costs and pricing keep supporting it.
- Revenue growth quality. Track quarterly sales and the export mix to see whether the 18% FY2026 growth continues or reverts toward the ~7% five-year trend.
- Cash deployment. With ~₹238 crore in investments and rising CWIP, watch how management uses the cash pile — capex, acquisitions, larger dividends, or buybacks.
- European restructuring outcome. Progress on the Venus Pharma GmbH share-allotment and European operations reorganisation.
- Return ratios. Whether the improved ROE (~17%) and ROCE (~22%) are sustained rather than a one-year spike.
Conclusion
Venus Remedies' ₹10 final dividend for FY2025-26 is a small payout with a big story behind it. Read purely as income, it is unremarkable — a ~0.55% yield that shrinks to ~0.39% after tax for high-slab investors, well below the pharma sector average. But read as a signal, it is significant: this is the company's first dividend in about 13 years, made possible by a genuine turnaround from years of losses and heavy debt to a debt-free balance sheet and a record ₹103 crore profit.
Positives
- First dividend since 2013 — a turnaround milestone
- Payout covered 8-12x by cash flows; highly affordable
- Debt-free, net-cash balance sheet
- Profit surge is operating-led and cash-backed
- Stable 41.76% promoter holding; proportionate payout
Negatives
- Very low yield; not an income stock
- No dividend track record (11-year 0% gap)
- Weak ~7% five-year sales CAGR
- Rich ~3.6x book valuation after big run-up
- Export/regulatory and European-subsidiary risks
The positives, negatives, risks and monitoring factors are laid out above so readers can weigh them against their own goals. This analysis is informational and does not constitute a buy, sell or hold recommendation.
Frequently Asked Questions
What dividend has Venus Remedies announced for FY2025-26?
What is the Venus Remedies dividend yield?
What is the record date for the Venus Remedies dividend?
What is the ex-dividend date?
When will the Venus Remedies dividend be paid?
Who was eligible to receive this dividend?
How is the Venus Remedies dividend taxed?
Is the Venus Remedies dividend sustainable?
What is the Venus Remedies dividend history?
Why did Venus Remedies stop paying dividends for so long?
How much did Venus Remedies earn in FY2026?
Does the dividend favour promoters?
What should investors monitor going forward?
Is Venus Remedies a good dividend stock?
Disclaimer
This article is for informational and educational purposes only and is a work of financial journalism. It does not constitute investment advice or a buy, sell or hold recommendation. Figures are drawn from the company's exchange filings and publicly available financial data sources; live market prices, yields and corporate-action dates are time-sensitive and must be independently re-verified before any decision, as all yields are price-dependent. ShareBazaar Online and the author are not registered investment advisers. Securities investments are subject to market risks; please read all related documents carefully and consult a SEBI-registered adviser and a qualified tax professional before investing. Neither ShareBazaar Online nor the author accepts liability for any loss arising from the use of this information.