
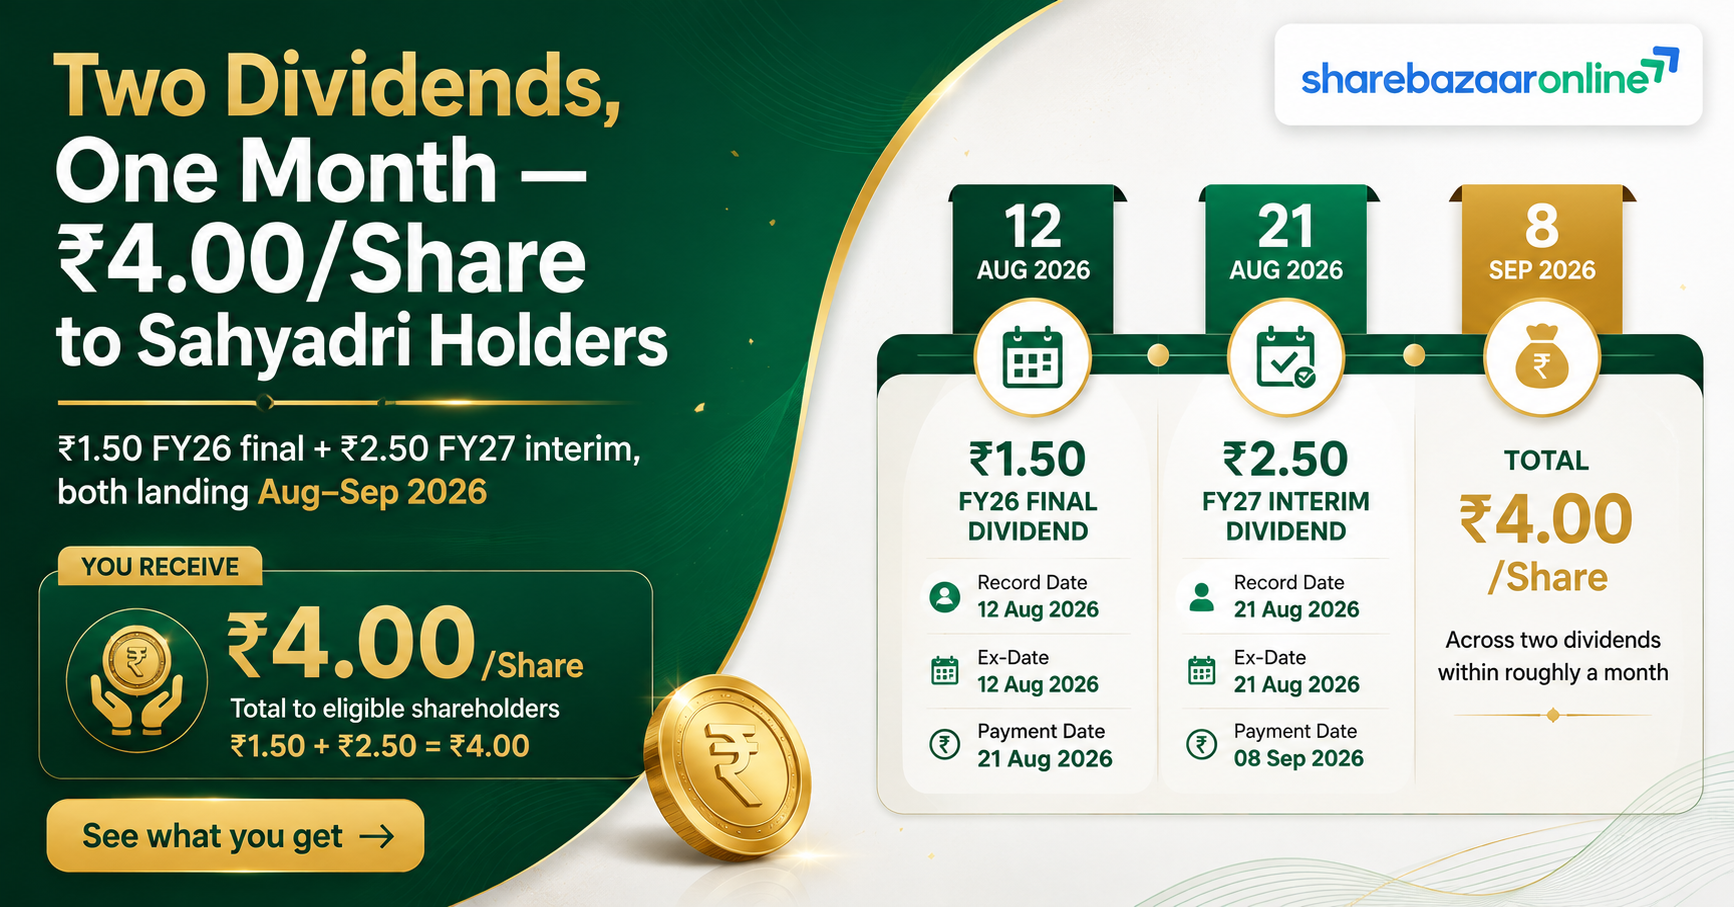
Dividend Snapshot
Sahyadri Industries Limited (NSE: SAHYADRI, BSE: 532841) has declared an interim dividend of ₹2.50 per equity share of face value ₹10 for the financial year 2026-27, approved at its Board meeting on 12 August 2026. In coupon terms this is a 25% interim dividend, but on the live market price the real cash yield is far smaller — the gap that this analysis unpacks in detail.
Dividend Per Share
₹2.50
Interim • FY 2026-27 • 25% of face value
Real Market Yield
~0.69%
at CMP ₹363 (14 Aug 2026)
Record Date
21 Aug 2026
Friday
Payment Date
8 Sep 2026
Total outflow ~₹2.74 crore
The standout fact: this ₹2.50 interim payout is the company's largest single dividend since FY2023, and it lands barely two weeks after the ₹1.50 FY26 final dividend (record date 7 August 2026). Shareholders on record for both are set to receive ₹4.00 per share within roughly one month — a clear signal of a dividend revival riding on a blockbuster June-quarter result.
Dividend Announcement Summary
On 12 August 2026, the Board of Directors of Sahyadri Industries, at a meeting that ran from 12:10 PM to 2:10 PM, approved the unaudited financial results for the quarter ended 30 June 2026 and declared (not merely recommended) an interim dividend of ₹2.50 per equity share for FY2026-27. Because this is an interim dividend declared directly by the Board, it does not require shareholder approval at an AGM — payment proceeds on the stated timeline.
What was approved
- Interim dividend: ₹2.50 per share (face value ₹10)
- Corporate action: Dividend (Series: Equity)
- Purpose: Payment of interim dividend for FY 2026-27
- Q1 FY27 unaudited results with limited review
Filing & audit basis
- Filed under SEBI LODR Regulation 30, 33 & 42
- Statutory auditor: Joshi Apte & Co., Pune
- Review conclusion: unmodified (no qualification)
- Company has no subsidiaries — standalone = consolidated
Key Dates Timeline
| Event | Date | Note |
|---|---|---|
| Announcement / Board meeting | 12 August 2026 | Interim dividend declared |
| Ex-Date | 21 August 2026 | Inferred under T+1 — Not Disclosed by Company |
| Record Date | 21 August 2026 (Fri) | Eligibility cut-off |
| Payment Date | 8 September 2026 | Credit to eligible members |
Under India's T+1 settlement, the ex-date and record date usually coincide. The company disclosed only the record date; the ex-date shown here is inferred and should be confirmed against the NSE/BSE corporate-action circular before acting.
Dividend Yield Analysis
The headline “25% dividend” is a face-value coupon (₹2.50 on a ₹10 face value) — not the return an investor actually earns. On the market price, the yield is a fraction of that:
Yield on announcement price
0.72%
₹2.50 ÷ ₹346.75 (NSE close, 12 Aug 2026)
Yield on latest market price
0.69%
₹2.50 ÷ ₹363 (14 Aug 2026)
Yield reality check
The modest ~0.7% yield is not the product of a falling share price or a one-off special dividend. The stock is actually near a 52-week high (₹200–₹379 range) and rose sharply on the results. The low yield instead reflects a deliberately conservative payout policy: the company distributes only a small slice of profits and retains the rest to fund two new manufacturing plants. Investors buying SAHYADRI for cash income should note this is a growth-and-capex story with a token dividend, not a high-yield instrument.
Dividend History Analysis
| Financial Year | Dividend Per Share (₹) | Character |
|---|---|---|
| FY2019 | 1.00 | Modest |
| FY2020 | 2.50 | — |
| FY2021 | 5.00 | Interim 1.50 + Final 3.50 |
| FY2022 | 6.00 | Peak (3.00 + 3.00) |
| FY2023 | 4.00 | Interim 2.50 + Final 1.50 |
| FY2024 | 1.00 | Sharp cut |
| FY2025 | 1.00 | Held low |
| FY2026 | 1.50 | Final (record 7 Aug 2026) |
| FY2027* | 2.50 | This interim — revival |
*FY2027 shows only the interim declared so far. Dividend history compiled from exchange corporate-action records and dividend aggregators; per-year figures should be cross-checked against annual reports.
Pattern: an irregular payer, now recovering
Sahyadri's dividend record is cyclical and irregular, not a smooth compounding stream. Payouts scaled up to a ₹6.00 peak in FY2022, then were cut roughly 75% to ₹1.00 in FY2024 and FY2025 as earnings and cash generation weakened. The current ₹2.50 interim — combined with the ₹1.50 FY26 final — marks a decisive step back up, funded by a strong turnaround quarter. Income-focused investors should treat the payout as variable and earnings-linked rather than assured.
Financial Performance Analysis
The dividend is backed by a standout June 2026 quarter. Q1 FY27 was seasonally strong (pre-monsoon construction demand) and delivered sharp operating leverage.
| Metric (₹ cr) | Q1 FY27 | Q1 FY26 | Change |
|---|---|---|---|
| Revenue from operations | 258.42 | 214.19 | +20.6% |
| Operating profit | ~39 | ~20 | +95% |
| Profit before tax | 35.50 | 14.49 | +145% |
| Net profit (PAT) | 26.52 | 10.77 | +146% |
| EPS (₹, not annualised) | 24.22 | 9.84 | +146% |
Operating leverage in action
Revenue grew ~21% but PAT jumped ~146% — the hallmark of operating leverage. The operating margin expanded from about 9.3% to 15.1%, as fixed costs were spread over higher volumes and finance costs fell (interest halved to ₹0.54 cr from ₹1.07 cr). The building-material segment (₹256 cr revenue) did the heavy lifting; the small power-generation segment added ₹4.84 cr.
Full-year context (FY26 vs TTM)
FY26 revenue was ₹679 cr with PAT of ₹29 cr (EPS ₹26.49). On a trailing-twelve-month basis, revenue is ~₹723 cr and PAT ~₹45 cr (EPS ~₹40.9), reflecting the Q1 surge. Note the FY26 seasonality: Q1 alone can rival a full prior year's profit, so do not annualise Q1 EPS.
Cash Flow Analysis
Reported profit is an opinion; cash is fact — and here the cash tells a genuinely strong story. In FY26 the company converted profit into cash at an exceptional rate.
Operating cash flow (FY26)
₹121 cr
vs PAT of ₹29 cr — CFO/operating-profit ~218%
Free cash flow (FY26)
₹107 cr
Up sharply from ₹35 cr in FY25
Is the dividend cash-funded?
Emphatically yes. The total interim outflow of about ₹2.74 cr is a rounding error against ₹107 cr of free cash flow — the dividend is funded comfortably from current-year cash generation, not from reserves, asset sales or borrowings. A large part of FY26's cash strength came from a big improvement in working capital: inventory days fell from ~242 to ~172, releasing cash. The one caution: this is a seasonal, working-capital-heavy business, so cash flow can swing between quarters.