
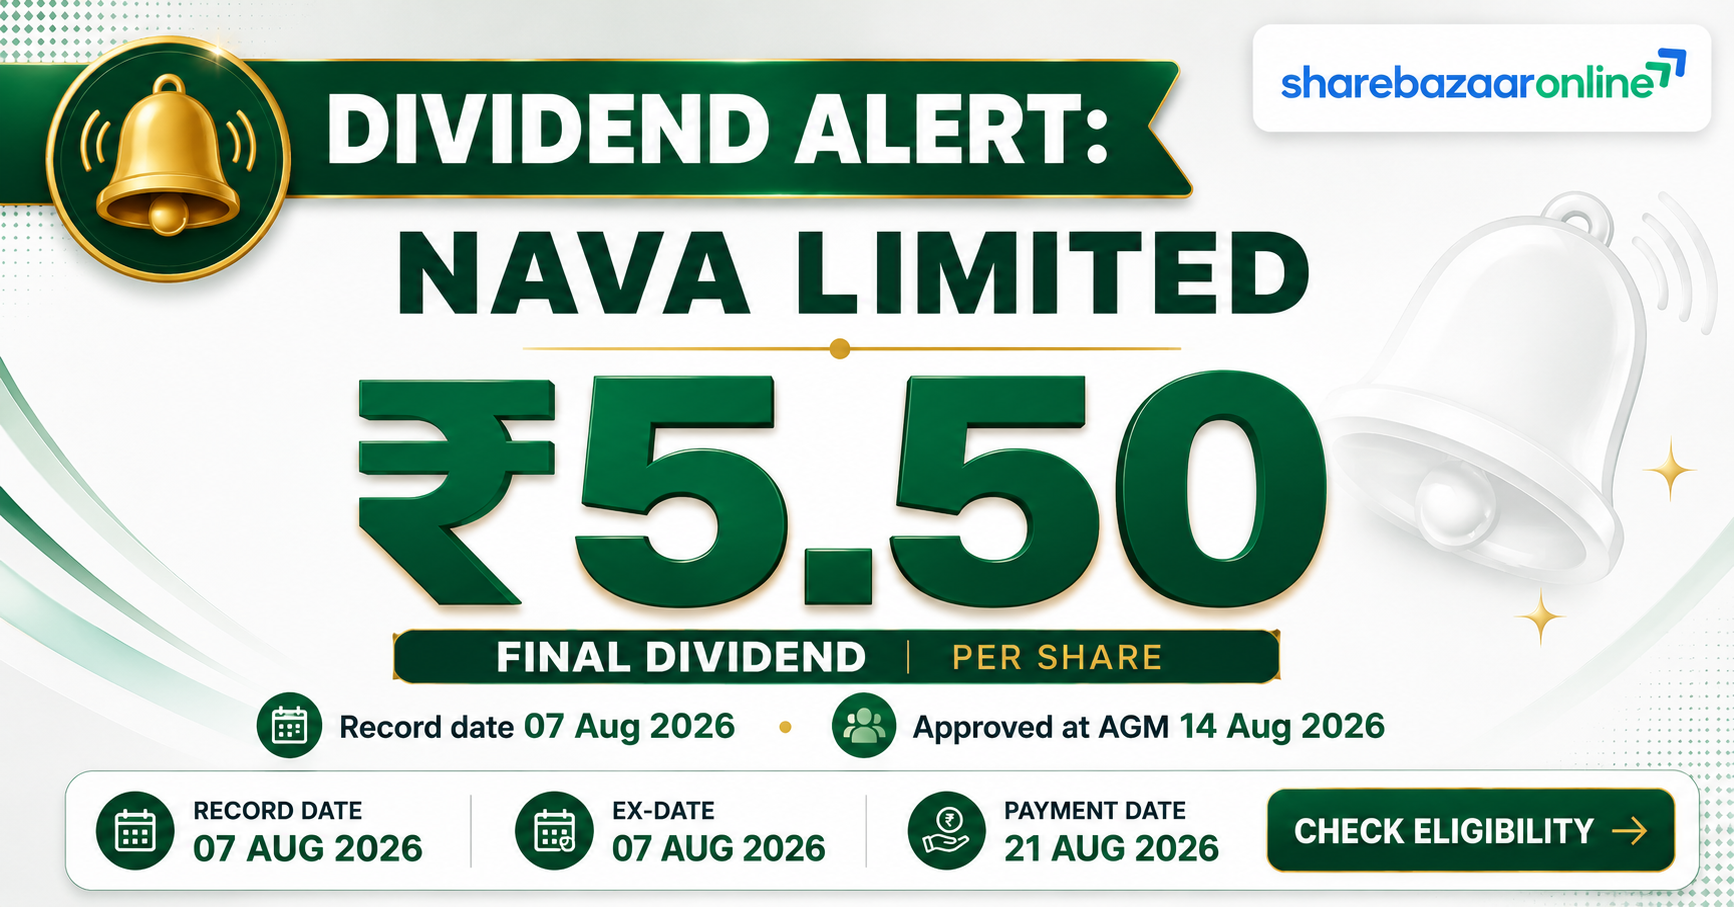
Dividend Snapshot
Nava Limited (NSE: NAVA | BSE: 513023 | ISIN: INE725A01030), the Hyderabad-based diversified conglomerate formerly known as Nava Bharat Ventures, has declared a final dividend of ₹5.50 per equity share for the financial year ended 31 March 2026. Because the face value of the share is just ₹1, the company describes this as a 550% dividend — a headline that sounds dramatic but is calculated on face value, not on the market price you actually pay.
On the current market price of ₹568.50 (NSE close, 15 August 2026), the ₹5.50 payout translates into a real Nava Limited dividend yield of about 0.97%. The total cash going out is roughly ₹155.72 crore. This report goes beyond the wire-service headline to examine whether the Nava Limited dividend is sustainable, how it compares with the company’s own history after its 2025 stock split, and what the cash flows really say.
Dividend Per Share
₹5.50
Final dividend, 550% of ₹1 face value
Real Dividend Yield
~0.97%
On CMP of ₹568.50 (re-verify before publishing)
Record Date
07 Aug 2026
Eligibility cut-off (Regulation 42 filing)
Dividend Outflow
~₹155.72 Cr
₹5.50 × ~28.31 crore shares
Dividend Announcement Summary
At its board meeting held on 15 May 2026, the Board of Directors of Nava Limited recommended a final dividend of ₹5.50 (Rupees Five and Fifty paise) per equity share of face value ₹1 each for FY2025-26, alongside the audited consolidated and standalone results. The recommendation was placed before shareholders at the 54th Annual General Meeting held via video-conferencing on 14 August 2026, where all nine resolutions — including the final dividend and director re-appointments — were approved.
What the company disclosed
- Dividend type: Final Dividend
- Amount: ₹5.50 per share (550%)
- Face value: ₹1
- Financial year: FY2025-26
- Payable within the statutory timeline after AGM approval
The non-obvious point
The “550%” figure is a percentage of the ₹1 face value, not of the share price. In cash terms it is ₹5.50. Aggregators often lead with the percentage; on the actual traded price of ₹568.50, the effective yield is under 1%. This is the classic face-value illusion retail investors should watch for.
Key Dates Timeline
| Event | Date | Source / Status |
|---|---|---|
| Board recommendation (announcement) | 15 May 2026 | Exchange filing (Reg 30/33) |
| Record date | 07 Aug 2026 (Fri) | Regulation 42 filing |
| Ex-dividend date | 07 Aug 2026 | Same as record date under T+1 (confirm vs NSE/BSE circular) |
| Register of members closed | 08–14 Aug 2026 | Company notice |
| 54th AGM (approval) | 14 Aug 2026 | Approved — all 9 resolutions passed |
| Payment date | Within 30 days of AGM | Company stated timeline; exact date Not Disclosed by Company |
Note: Because the record date (07 Aug 2026) has already passed, eligibility for this dividend was fixed on that date. Investors who held shares as of the close of 07 August 2026 were entitled to the payout; the company confirmed it would remit the dividend electronically within 30 days of the AGM.
Dividend Yield Analysis
Every yield figure depends on the price you use as the denominator. Here is the Nava Limited dividend yield computed three ways, so readers can see how the same ₹5.50 payout looks very different from the “550%” headline.
Yield on current market price
₹5.50 ÷ ₹568.50 = 0.97%
CMP as on 15 Aug 2026, NSE. All yields are price-dependent and must be re-verified before publication.
Yield on announcement-date price
₹5.50 ÷ ₹628.50 = 0.88%
NAVA closed near ₹628.50 on 15 May 2026, the announcement day.
Yield Reality Check
Nava’s trailing dividend yield on data aggregators appears higher (roughly 1.4–1.5%) because it reflects the larger ₹6.00 dividend paid during the previous cycle. On a forward basis, the newly declared ₹5.50 is a smaller per-share payout, and the share price has fallen from its 52-week high of ₹739.40 (11 May 2026) to ₹568.50. So the yield you see is a product of a modest dividend on a stock that has de-rated — not a sudden surge in shareholder generosity. Nava is fundamentally a growth-and-capex conglomerate, not a high-yield income stock.
Dividend History Analysis
This is where most coverage of the Nava Limited dividend history goes wrong. On 20 January 2025, Nava executed a 1:2 stock split, subdividing each ₹2 face-value share into two ₹1 shares. Any per-share dividend declared before that date was paid on a ₹2 face value and must be halved to compare fairly with the current ₹1-face-value payouts. Ignoring the split makes the dividend trend look far more explosive than it really is.
Dividend per share — split-adjusted to ₹1 face value
| Financial Year | As Reported | Face Value Then | Adjusted to ₹1 FV |
|---|---|---|---|
| FY2019-20 | ₹0.75 | ₹2 | ₹0.38 |
| FY2020-21 | ₹1.25 | ₹2 | ₹0.63 |
| FY2021-22 | ₹3.00 | ₹2 | ₹1.50 |
| FY2022-23 | ₹3.00 | ₹2 | ₹1.50 |
| FY2023-24 | ₹4.00* | ₹2 | ₹2.00 |
| FY2024-25 | ₹6.00 | ₹1 (post-split) | ₹6.00 |
| FY2025-26 | ₹5.50 | ₹1 | ₹5.50 |
*FY2023-24 figures are aggregated across multiple pay-outs and differ across data sources; the exact split of final vs special dividend should be verified against Nava’s official corporate-action records. Pre-FY25 amounts are split-adjusted by the analyst; they are Not Independently Verified against exchange circulars on an adjusted basis.
The finding aggregators miss
On a like-for-like ₹1 face-value basis, the FY26 dividend of ₹5.50 is actually 8.3% lower than the ₹6.00 paid for FY25. So despite the eye-catching “550%” headline, Nava has modestly trimmed its per-share dividend year-on-year — consistent with lower reported profit (discussed below). The long-run trend is still one of a rising payer over the decade, so Nava reads as a consistent but cyclical dividend payer rather than a steadily compounding income machine.
Financial Performance Analysis
The most striking feature of Nava Limited’s FY26 results is a divergence between the top line and the bottom line: consolidated revenue rose while attributable profit fell sharply. Understanding why is central to judging the dividend.
Consolidated results (₹ Crore)
| Metric | FY26 | FY25 | Change |
|---|---|---|---|
| Revenue from operations | 4,290.92 | 3,983.55 | +7.7% |
| PBT (continuing) | 1,502.02 | 1,608.49 | −6.6% |
| PAT (attributable) | 786.67 | 1,091.48 | −27.9% |
| EPS (basic) | ₹27.80 | ₹37.63 | −26.1% |
Why profit fell despite higher sales
Pre-tax profit dropped only 6.6%, but post-tax profit fell 27.9%. The gap is almost entirely a non-cash deferred tax charge. FY26 carried a deferred tax expense of ₹261.79 crore versus a ₹10.47 crore credit in FY25, pushing the effective tax rate from ~10.7% to ~30.8%. This arose largely from the appreciation of the Zambian Kwacha at step-down subsidiary Maamba Energy (MEL), which created a deferred tax liability on foreign-currency borrowings. In short, the profit “collapse” is largely an accounting/tax event, not an operating one.
Earnings-quality flag: the standalone one-off
Nava pays dividends out of its standalone entity, which reported PAT of ₹910.93 crore for FY26. But this includes a one-time exceptional gain of ₹403.95 crore (from a buy-back of shares by subsidiary Nava Global Pte and transfer of investment in Nava Resources CI) — roughly 38% of standalone pre-tax profit. Strip out that one-off and the recurring standalone earnings base is materially smaller. The dividend is comfortably covered either way, but investors should not read ₹910.93 crore as a repeatable run-rate.
Cash Flow Analysis
Reported profits are opinions; cash is fact. On the cash-flow test, Nava looks far healthier than the headline profit decline suggests. Operating cash flow (OCF) for FY26 was ₹2,312.33 crore — comfortably higher than reported profit, because that big deferred-tax charge is non-cash and because a large chunk of overdue MEL receivables was finally collected, releasing working capital.
Cash flow snapshot (₹ Crore, consolidated)
- Operating cash flow: ₹2,312.33
- Capex (PP&E purchase): ₹1,807.19
- Free cash flow (OCF − capex): ₹505.14
- Dividend outflow: ₹155.72
OCF vs profit
OCF of ₹2,312 crore against attributable PAT of ₹787 crore gives a cash-conversion ratio well above 100% — a healthy sign. The company’s debtor days also improved sharply from 129 to about 81, reflecting the MEL cash recovery. This is the opposite of the classic warning sign where profit is high but cash is thin.
How the dividend is funded
The ₹155.72 crore dividend is funded comfortably from current operations, not from borrowings or asset sales. Free cash flow of ₹505 crore covers it more than 3 times even after heavy capex. The reason FCF is lower than OCF is a large step-up in capital expenditure (₹1,807 crore) as Nava builds new capacity — capital-expansion spending, not dividend distress, is what consumes the cash.
Balance Sheet Strength
Nava enters this dividend cycle with an unusually strong liquidity position, even though its gross borrowings rose sharply during the year to fund expansion.
Key balance-sheet items (₹ Crore)
- Cash & cash equivalents: ₹2,098.52
- Current investments: ₹1,347.88
- Total liquidity: ₹3,446.40
- Gross borrowings (incl. lease): ₹2,226.41
- Net position: Net cash of ~₹1,220
- Book value per share: ~₹309
Debt rose — but for growth
Gross borrowings jumped from about ₹893 crore (FY25) to ₹2,226 crore (FY26). At first glance that looks alarming while paying a dividend. But capital work-in-progress simultaneously rose from ₹575 crore to ₹2,185 crore — the fresh debt is funding new plant and capacity, not the payout. Because liquidity (₹3,446 crore) still exceeds borrowings, Nava remains in a net-cash position. The dividend does not depend on this debt.
Dividend Sustainability Analysis
We test the Nava Limited dividend against four independent coverage yardsticks. On every one, the ₹155.72 crore payout is comfortably covered.
| Coverage test | Base amount | Cover | Verdict |
|---|---|---|---|
| Earnings (attributable PAT) | ₹786.67 Cr | 5.05× | Comfortable |
| Operating cash flow | ₹2,312.33 Cr | 14.8× | Very strong |
| Free cash flow | ₹505.14 Cr | 3.2× | Adequate |
| Liquidity (cash + investments) | ₹3,446.40 Cr | 22.1× | Ample |
Overall verdict: Sustainable
With a payout ratio of only ~19.8% of attributable profit (about 17.1% of standalone profit), a dividend covered five times by earnings, nearly 15 times by operating cash flow, and a large net-cash buffer, the FY26 dividend is clearly Sustainable. The genuine caveats are not about affordability but about direction: reported profit is declining, part of standalone earnings is a one-off, and the per-share dividend itself has been trimmed versus last year. A modestly lower dividend on a de-rating stock is affordable, but it is not a rising-income story.
Peer Comparison
Nava is a diversified play spanning ferro alloys, thermal power, mining, agribusiness and healthcare, so no single peer is a perfect match. The clearest comparable on the metals side is Maithan Alloys, a pure ferro-alloys producer. Cells left blank are Not Independently Verified in this session and should be completed by the desk before publication.
| Company | Div. Yield | Payout | ROE | ROCE |
|---|---|---|---|---|
| Nava Limited | ~0.97% | ~19.8% | ~9.3% | ~12.8% |
| Maithan Alloys | ~1.5% | — | ~22% | ~28% |
| NTPC (power peer) | — | — | — | — |
| Tata Power (power peer) | — | — | — | — |
Maithan Alloys figures per market data around August 2026. Nava ratios per consolidated FY26 data. Yields are price-dependent and must be re-verified. Blank cells indicate data Not Independently Verified.
What the comparison shows
Against a focused peer like Maithan Alloys, Nava screens as a lower-yield, lower-return-ratio, capital-intensive conglomerate. Its ROE (~9.3%) and ROCE (~12.8%) are below Maithan’s, partly because Nava carries a large, still-maturing asset base (including new capex) and a substantial minority-interest structure in Zambia. Nava’s appeal has historically been capital appreciation and diversification, not dividend yield.
Promoter Impact Analysis
As of the June 2026 shareholding pattern, promoters held about 50.03% of Nava Limited, with FIIs at ~10.22%, DIIs at ~0.56% and public/retail investors holding the balance (~39.18%).
Who receives the ₹155.72 crore
- Promoter group (~50.03%): ~₹77.91 Cr
- Public, FII & DII (~49.97%): ~₹77.81 Cr
Estimated on latest disclosed holding; actual receipts depend on holdings on the record date.
Distribution impact
With promoters just above 50%, roughly half the dividend flows to the promoter family and half to minority shareholders — a broadly balanced split. Because the payout ratio is modest (~19.8%), the bulk of profit is retained for reinvestment, which benefits all shareholders through book-value growth rather than immediate cash. Promoter holding has actually risen over recent years (from ~48.9% to ~50%), which some investors read as alignment of interest.
Taxation Analysis
Since the abolition of the Dividend Distribution Tax in 2020, dividends are taxed in the hands of the shareholder at their applicable income-tax slab rate. The company also deducts tax at source (TDS) before paying.
The rules in brief
- Dividend added to total income and taxed at your slab rate.
- TDS at 10% if total dividend from the company in the year exceeds ₹10,000 and a valid PAN is registered.
- TDS at 20% if PAN is missing or not linked to Aadhaar.
- No TDS if aggregate dividend stays within the ₹10,000 threshold for the year (per Nava’s own dividend notice).
- Form 15G/15H (or the equivalent nil-TDS declaration) can be filed by eligible investors below the taxable limit.
Worked example — 1,000 shares
- Gross dividend: 1,000 × ₹5.50 = ₹5,500
- TDS: ₹0 (below the ₹10,000 threshold)
- Tax at 30% slab: ₹1,650
- Net in hand: ₹3,850
- Effective post-tax yield (on ₹568.50 CMP): ~0.68%
A larger holder of 5,000 shares (gross ₹27,500) would see ₹2,750 TDS at 10% and, at a 30% slab, total tax of ₹8,250 (net ₹19,250). Consult a tax adviser for your situation.
Key Risks
- Zambia / MEL concentration & currency risk: A large slice of group profit comes from Maamba Energy in Zambia. The FY26 deferred-tax hit from Zambian Kwacha appreciation shows how sensitive reported earnings are to foreign-exchange swings. Overdue receivables from an MEL customer were about ₹259.90 crore at year-end (down from ₹1,374.78 crore), backed by a Zambian sovereign guarantee — but sovereign and collection risk remain.
- Commodity cyclicality: Ferro alloys (silico manganese) realisations are volatile and segment profits swing quarter to quarter, making dividends inherently cyclical.
- Rising leverage & execution: Gross debt roughly tripled to ₹2,226 crore to fund a large capex programme; capital work-in-progress ballooned to ₹2,185 crore. Delays or cost overruns on these projects would pressure returns.
- Earnings quality: FY26 standalone profit was flattered by a ₹403.95 crore one-off gain, while consolidated profit was depressed by a non-cash deferred-tax charge — the underlying run-rate is harder to read than headline numbers suggest.
- Regulatory, tax & litigation: New Labour Codes (notified November 2025), evolving cross-border tax treatment, power-sector regulation, and the sub-judice Brahmani Infratech (BIPL) vs MTPPL dispute with contingent liabilities all add uncertainty.
What To Monitor
- MEL / Zambia recovery and Kwacha trend: Pace of collection of the remaining ~₹259.90 crore receivable and any further currency-driven tax effects.
- Capex execution: Conversion of the ₹2,185 crore capital work-in-progress into revenue-generating assets, and clarity on Nava’s newer energy ambitions.
- Ferro-alloy spreads: Silico manganese realisations and input costs, which drive the metals segment’s profitability.
- Tax normalisation: Whether the effective tax rate reverts toward historical levels in FY27 once the deferred-tax distortion unwinds.
- Debt trajectory & net-cash buffer: Whether Nava preserves its net-cash position as capex ramps up.
- Per-share dividend direction: Whether the FY27 dividend recovers toward the ₹6.00 level or continues the modest FY26 trim.
Conclusion
Nava Limited’s FY2025-26 final dividend of ₹5.50 per share is a well-covered, easily affordable payout — but the “550%” headline flatters it. On the real market price the yield is under 1%, the per-share dividend is actually 8.3% lower than last year once the January 2025 stock split is accounted for, and headline profit fell nearly 28% (mostly on a non-cash deferred-tax charge, with standalone profit boosted by a one-off gain).
The positives are real: operating cash flow of ₹2,312 crore, free cash flow covering the dividend more than three times, a net-cash balance sheet, and a modest ~19.8% payout ratio that leaves ample room to keep paying. The negatives are equally real: declining reported profit, earnings-quality noise, cyclical commodity exposure, concentrated Zambian risk, and rising debt for expansion. Nava remains a growth-and-capex conglomerate that pays a small, sustainable dividend — not an income stock. We present the positives, negatives, risks and monitoring factors; the investment decision is yours.
Frequently Asked Questions
What dividend has Nava Limited announced for FY2025-26?
What is the Nava Limited dividend yield?
What is the record date for the Nava Limited dividend?
What is the ex-date for the Nava dividend?
When will Nava Limited pay the dividend?
Who is eligible for the Nava Limited dividend?
How is the Nava dividend taxed?
Is the Nava Limited dividend sustainable?
What is Nava Limited’s dividend history?
Why did the “550%” dividend not lift the share price much?
Why did Nava’s profit fall in FY26 even though revenue grew?
How much of the dividend goes to promoters?
What should investors monitor going forward?
Disclaimer
This article is published by ShareBazaar Online for informational and educational purposes only. It is financial journalism, not investment advice, and does not constitute a buy, sell or hold recommendation on Nava Limited or any other security. ShareBazaar Online is not registered with SEBI as an investment adviser or research analyst. Figures are drawn from Nava Limited’s audited FY2025-26 filings and publicly available market data; market prices and yields are price-dependent and change continuously. Some figures are inferred or cross-referenced and are marked accordingly. Readers should verify all data with primary sources and consult a SEBI-registered financial adviser and a tax professional before making any investment or tax decision. Investments in securities are subject to market risks; please read all related documents carefully.