
Dividend Snapshot
Rubicon Research Limited (NSE: RUBICON, BSE: 544578) has recommended a final dividend of ₹1.50 per equity share for the financial year ended 31 March 2026. On a face value of just ₹1, that headline reads as a 150% dividend — but the real, market-price dividend yield works out to only about 0.10%. This is Rubicon's first dividend as a listed company, coming barely seven months after its October 2025 stock market debut. This is a non-advisory, information-only analysis of the Rubicon Research dividend 2026.
Dividend Per Share
₹1.50
Face value ₹1 (150% on face value)
Real Dividend Yield (at CMP)
~0.10%
0.15% at the announcement-day price
Dividend Type
Final Dividend
Subject to AGM approval (26 Aug 2026)
Record Date
7 Aug 2026
Eligibility now closed
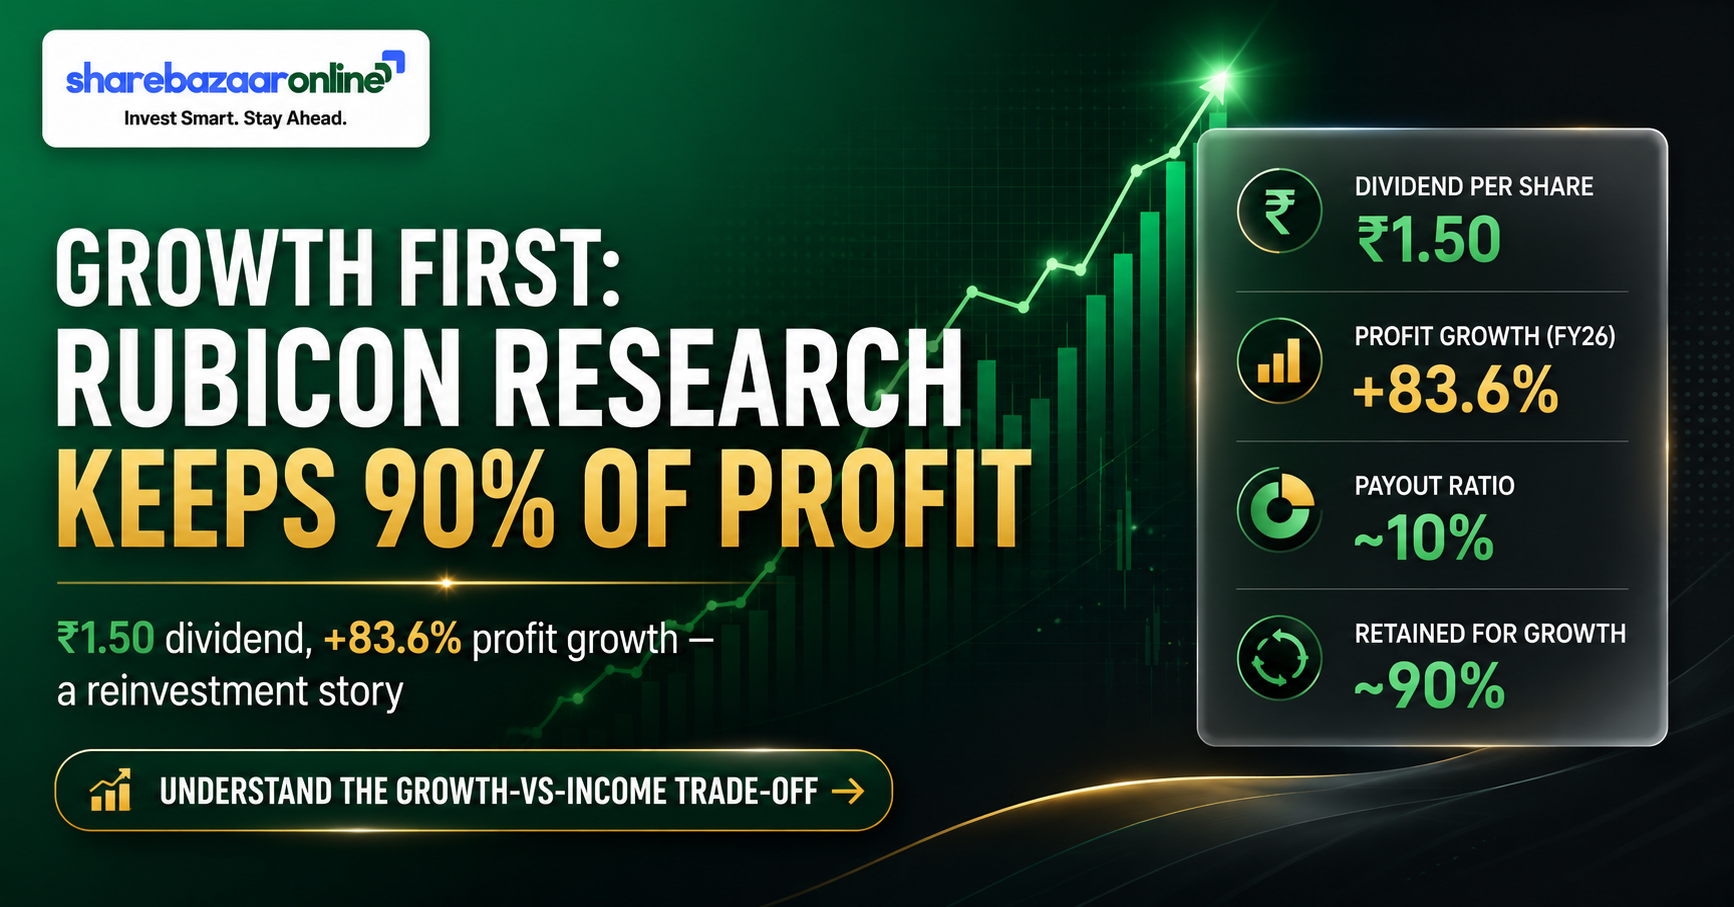
The one-line takeaway: Rubicon's payout is symbolically small — roughly ₹24.8 crore, about 10% of consolidated profit. The company is deliberately holding on to cash to fund a fast-moving growth and acquisition agenda rather than to reward shareholders with income. Investors reading "150% dividend" headlines should treat this as a token, growth-stage payout, not a yield play.
Dividend Announcement Summary
At its board meeting on 29 May 2026 (2:30 PM to 4:10 PM IST), the Board of Directors of Rubicon Research approved the audited standalone and consolidated financial results for the quarter and year ended 31 March 2026 and recommended a final dividend of ₹1.50 per equity share of face value ₹1 each, fully paid up. The recommendation is subject to approval by members at the ensuing Annual General Meeting, and the dividend is to be paid within 30 days of that approval.
Context that matters: Rubicon completed its IPO and listed on the NSE and BSE on 16 October 2025. As a newly public company, FY2025-26 is the first full year for which it is declaring a dividend to public shareholders. The statutory auditors, Deloitte Haskins & Sells LLP, issued an unmodified (clean) opinion on both the standalone and consolidated results.
Why the payout is small: The dividend was recommended alongside a strong earnings print — consolidated net profit rose about 83.6% to ₹246.7 crore. Yet management chose a token payout, keeping the bulk of profits to fund capacity, R&D and its recently closed acquisition of a 65% stake in Arinna Lifesciences.
Key Dates Timeline
Announcement (Board Meeting)
29 May 2026
Record Date
7 August 2026 (Friday)
Ex-Date
7 August 2026 (inferred under T+1; confirm against exchange circular)
TDS Document Deadline (company-set)
10 August 2026
27th Annual General Meeting
26 August 2026, 1:00 PM IST (via VC)
Payment Date
Within 30 days of AGM approval
Because the record date of 7 August 2026 has already passed, the shareholder list for this dividend is fixed. The dividend still requires shareholder approval at the AGM on 26 August 2026 before it can be paid. The company has flagged that valid tax documentation had to be submitted by 10 August 2026 to avoid standard TDS rates. The exact payment date has been described only as "within 30 days of declaration by members at the AGM" — a specific payment date was Not Disclosed by Company.
Dividend Yield Analysis
This is the single most important number for retail readers to understand. A "150% dividend" is not a 150% return — it simply means ₹1.50 on each ₹1 of face value. What actually lands in your bank account depends on the market price you pay, and that changes the picture completely.
Face-Value Coupon (the headline)
150%
₹1.50 ÷ ₹1 face value
Yield on Announcement-Day Price
0.15%
₹1.50 ÷ ₹1,005.60 (NSE close, 29 May 2026)
Yield at Current Market Price
~0.10%
At approx ₹1,491–₹1,553 (Aug 2026, verify at publish)
Sector Context
0.8%
Approx pharmaceuticals industry average yield
Yield reality check: Rubicon's yield is low for two clear reasons. First, the absolute dividend is tiny (₹1.50). Second, and more importantly, the share price has roughly tripled since the ₹485 IPO price to around ₹1,491–₹1,553. A rising share price mechanically pushes yield down. So the near-zero yield here reflects a strong, richly-valued growth stock paying a token dividend — not a distressed or declining business. This is the opposite of a "high-yield trap."
Dividend History Analysis
Rubicon Research has no public dividend track record. The company listed only in October 2025, and this ₹1.50 final dividend for FY2025-26 is its maiden dividend as a listed entity. There is therefore no multi-year history of consistency, growth, cuts or suspensions to review — a point that differentiates this analysis from established dividend payers.
Dividend History
| FY2025-26 | ₹1.50 (Final) |
| FY2024-25 | Nil (pre-listing) |
| FY2023-24 | Nil (pre-listing) |
| Earlier years | Not applicable (unlisted) |
Classification: New / First-time payer. With only one data point, no dividend-consistency verdict can be drawn yet. Whether Rubicon becomes a consistent payer will depend on how it balances heavy growth investment against shareholder returns in the coming years. Readers should not extrapolate a ₹1.50 recurring dividend from a single declaration.
Financial Performance Analysis
On a consolidated basis for FY2025-26, Rubicon delivered a strong set of numbers. This matters because the dividend was declared on the back of genuine operating growth, not accounting one-offs.
Revenue from Operations
₹1,753.96 cr
Up 36.6% from ₹1,284.27 cr in FY25
Consolidated Net Profit (PAT)
₹246.74 cr
Up 83.6% from ₹134.36 cr in FY25
EBITDA (ex other income)
~₹400 cr
Up ~51%; margin 22.8% vs 20.6%
Consolidated EPS (Basic)
₹15.52
Standalone EPS: ₹11.83
Operating leverage — the good kind: Revenue grew 36.6% while profit grew a far faster 83.6%, and EBITDA margin expanded from 20.6% to 22.8%. This is positive operating leverage — costs grew slower than sales, so more of each incremental rupee of revenue dropped to the bottom line. The Q4 print was even sharper: consolidated Q4 revenue rose 43.5% and Q4 net profit jumped about 111.8% year on year.
Earnings quality is high: Other income was only ₹7.73 crore — roughly 2.4% of pre-tax profit. In plain terms, almost all of Rubicon's profit came from its actual pharmaceutical business (US-focused generics and specialty formulations), not from treasury gains or one-time items. Standalone PAT was ₹188.17 crore; consolidated PAT was higher at ₹246.74 crore, meaning the group's overseas operating subsidiaries were net contributors even though a set of 11 smaller subsidiaries reported a combined net loss of about ₹22.45 crore.
Cash Flow Analysis
Reported profit is an accounting opinion; cash is a fact. This is where the dividend story gets more nuanced — and where ShareBazaar's analysis goes beyond the headline.
Operating Cash Flow (OCF)
₹205.05 cr
vs PAT of ₹246.74 cr
Capital Expenditure
₹194.89 cr
Plus ~₹34 cr on leasehold land/building
Free Cash Flow (OCF − Capex)
~₹10.15 cr
Turns negative if land spend is included
Dividend Outflow
₹24.76 cr
FCF coverage only ~0.41x
The key finding — how is this dividend actually funded? Rubicon's FY26 free cash flow was razor-thin (about ₹10 crore) because it ploughed almost all of its ₹205 crore operating cash back into capex. That free cash flow does not cover the ₹24.76 crore dividend on its own. So the payout is being funded from the company's large cash reserves — substantially built up from its October 2025 IPO fresh-issue proceeds — rather than from the current year's surplus cash generation.
A cash-flow watch item: OCF (₹205 cr) trailed PAT (₹247 cr), and the balance sheet shows working capital absorbing cash — inventories rose sharply (a build of roughly ₹207 crore) and trade receivables climbed (about ₹180 crore). Working-capital days have been rising. For a fast-growing exporter this is not unusual, but it is the reason profit is not fully converting into cash, and it is worth monitoring.
Balance Sheet Strength
Cash & Bank Balances
₹346.02 cr
Cash ₹185.65 cr + other bank ₹160.36 cr
Total Borrowings
₹259.37 cr
Debt-to-equity of just 0.20
Net Cash Position
~₹86.65 cr net cash
Liquid balances exceed total debt
Return Ratios (Screener)
ROE 27.0% | ROCE 28.4%
Book value ~₹78/share (consolidated)
The balance sheet is comfortably placed. Rubicon used part of its IPO proceeds to repay borrowings, and it now sits in a modest net-cash position with a low debt-to-equity ratio of 0.20. High returns on equity and capital employed (both around 27–28% per Screener) show the business earns well on the capital it deploys. From an affordability standpoint, the tiny dividend poses no strain on this balance sheet whatsoever. Return ratios sourced from Screener.in; verify at publish.
Dividend Sustainability Analysis
We assess sustainability across four coverage tests. Because the dividend is so small relative to the company's size, most tests pass comfortably — the exception is the free-cash-flow test.
1. Earnings Coverage
10.35x (PASS)
Consol EPS ₹15.52 vs DPS ₹1.50; payout ~10%
2. Operating Cash Flow Coverage
~8.3x (PASS)
OCF ₹205 cr vs dividend ₹24.76 cr
3. Free Cash Flow Coverage
~0.41x (FAIL)
FCF ~₹10 cr < dividend; funded from reserves
4. Cash / Liquidity Coverage
~14x (PASS)
Cash & bank ₹346 cr vs dividend ₹24.76 cr
Verdict: Sustainable (in absolute terms), but growth-constrained by design. Three of four tests pass with large margins. The FCF test "fails" only because the company is in an aggressive capex-and-acquisition phase that consumes most of its operating cash — a deliberate structural choice, not a sign of stress. Given the ₹346 crore liquidity cushion and negligible payout ratio, the ₹1.50 dividend is easily affordable. The real question is not whether Rubicon can pay, but whether it will grow the dividend meaningfully while it prioritises reinvestment. On current evidence, income-focused investors should expect this to remain a token payout for some time.
Peer Comparison
Dividend yield & payout vs selected pharma peers (approximate, verify at publish)
| Company | Div Yield | Payout Ratio | ROE |
|---|---|---|---|
| Rubicon Research | ~0.10% | ~10% (consol) | ~27.0% |
| Ajanta Pharma | ~0.8–1.0% | ~33–36% | |
| Gland Pharma | ~0.9–1.3% | ~37–46% | |
| Laurus Labs | ~0.11% | ~6.6% | |
| Pharma sector avg | ~0.8% |
Peer figures sourced from public aggregators and are approximate; blank cells are intentionally left unverified. Peer prices/yields move daily.
Rubicon's yield sits at the very bottom of the peer set, alongside Laurus Labs — another R&D-heavy, reinvestment-focused player. More mature formulators such as Ajanta Pharma and Gland Pharma return a larger slice of profit as dividends (payout ratios in the 33–46% range). Rubicon's ~10% consolidated payout is markedly lower, consistent with a company still early in its listed life and prioritising growth over income.
Promoter Impact Analysis
Promoter Holding (Mar 2026)
~59.9%
FII ~7.5% | DII ~10.1% | Public ~22.6%
Estimated Promoter Dividend
~₹14.83 cr
Public & institutions share ~₹9.93 cr
Of the total ₹24.76 crore payout, an estimated ₹14.83 crore flows to the promoter group (holding roughly 59.9%), with the remaining ₹9.93 crore going to public shareholders, FIIs and DIIs. Because the payout is small and the ownership split is unremarkable, there is no evidence here of a dividend being used to disproportionately channel cash to promoters — a red flag ShareBazaar routinely checks for. Promoter holding stepped down from about 62% at listing to ~59.9%, reflecting normal post-IPO churn and ESOP allotments rather than large promoter exits. Shareholding sourced from public aggregators (Mar 2026); verify at publish.
Taxation Analysis
Since the abolition of the Dividend Distribution Tax, dividends in India are taxed in the hands of the shareholder at their applicable income-tax slab rate. The company deducts TDS under Section 194 at 10% for resident shareholders where the total dividend paid in a financial year exceeds ₹10,000 (the threshold was raised from ₹5,000 with effect from FY2025-26). If a valid PAN is not available, TDS is deducted at 20%. Non-resident shareholders face TDS around 20% (subject to any applicable tax treaty / DTAA relief).
Worked example — retail investor holding 1,000 shares
| Shares held | 1,000 |
| Dividend per share | ₹1.50 |
| Gross dividend | ₹1,500 |
| TDS u/s 194 (below ₹10,000 threshold) | ₹0 |
| Tax at 30% slab (payable via ITR) | ₹450 |
| Net dividend after tax | ₹1,050 |
| Effective post-tax yield (at ₹1,491) | ~0.07% |
For this holder, no TDS is deducted (the ₹1,500 gross is below the ₹10,000 threshold), but the ₹1,500 is still added to total income and taxed at the slab rate — here 30%, leaving ₹1,050 in hand. After tax, the effective yield on a ~₹1,491 share is close to 0.07%. The practical point: at these price levels, the dividend's cash value to a retail investor is negligible compared with the stock's price movements.
Key Risks
- US market concentration: Rubicon derives the overwhelming majority of revenue (around 99.5% in a recent quarter) from the United States generic and specialty market. Any US pricing pressure, customer concentration or channel disruption directly hits earnings — and therefore future dividend capacity.
- USFDA regulatory risk: As a US-focused formulator, Rubicon is exposed to USFDA inspections and observations. A recent facility inspection reportedly resulted in procedural observations; any escalation to warning letters or import alerts could materially affect revenue.
- Rich valuation: The stock trades at a very high P/E (roughly 96–100x) and around 19–20x book value. Elevated multiples leave little room for earnings disappointment, and the near-zero yield offers no valuation cushion.
- Working capital & cash conversion: Inventories and receivables have grown faster than usual, working-capital days have risen (from ~69 to ~104 days per Screener), and free cash flow is thin. If this trend continues, cash generation could lag reported profit.
- Acquisition integration risk: The recently completed 65% acquisition of Arinna Lifesciences (~₹176 crore) and the proposed KIA Health Tech merger add integration and execution risk. Some subsidiaries are still loss-making (11 subs posted a combined ~₹22.45 crore loss in FY26).
- Currency risk: With revenue predominantly in US dollars and a domestic cost base, rupee-dollar swings can affect reported margins.
What To Monitor
- Dividend trajectory: Whether the FY27 dividend grows beyond ₹1.50 or stays token — the clearest signal of management's shift (or not) toward shareholder returns.
- Free cash flow conversion: Watch whether OCF and FCF start catching up with reported profit as the current capex cycle matures. A widening gap is a warning sign.
- US business momentum & new approvals: Product filings, approvals and commercialisation rates in the US pipeline, which drive the revenue engine.
- USFDA inspection outcomes: Any change in the status of facility observations, which can swing the stock materially.
- Acquisition performance: How Arinna Lifesciences and other subsidiaries perform post-integration, and whether loss-making units turn around.
- Working-capital days and margin trend: Continuation of the EBITDA margin expansion (currently ~22.8%) versus any reversal from cost inflation.
Conclusion
Rubicon Research's maiden dividend of ₹1.50 per share is best understood as a symbolic gesture from a young, fast-growing, richly-valued pharmaceutical company — not as an income opportunity. The "150% dividend" headline masks a real yield of about 0.10%.
The Positives
- Strong FY26: revenue +36.6%, PAT +83.6%, margin expansion
- High earnings quality (other income just ~2.4% of PBT)
- Net-cash balance sheet, low D/E of 0.20, ROE/ROCE ~27–28%
- Dividend easily affordable; ~14x cash coverage
The Negatives / Watch-outs
- Near-zero yield (~0.10%); token payout (~10%)
- FCF (₹10 cr) does not cover the dividend — funded from reserves
- Very high valuation (P/E ~96–100x)
- Heavy US concentration and USFDA regulatory exposure
In short: a financially healthy business paying a deliberately minimal dividend while it reinvests for growth. Income seekers will find little here; the dividend is a footnote to a growth-and-valuation story. As always, ShareBazaar presents the facts — positives, negatives and risks — and leaves the decision to you.
Frequently Asked Questions
What dividend has Rubicon Research announced for FY2025-26?
What is the Rubicon Research dividend yield?
What is the record date for the Rubicon Research dividend?
What is the ex-date for this dividend?
When will the Rubicon Research dividend be paid?
Who is eligible for the Rubicon Research dividend?
How is the Rubicon Research dividend taxed?
Is the Rubicon Research dividend sustainable?
What is Rubicon Research's dividend history?
What is the total dividend payout and how much goes to promoters?
Why is the dividend so small despite strong profits?
What should investors monitor going forward?
How did Rubicon Research perform financially in FY2025-26?
Disclaimer
ShareBazaar Online is not a SEBI-registered investment adviser or research analyst. This article is for informational and educational purposes only and does not constitute investment advice or any buy, sell or hold recommendation. Figures are derived from Rubicon Research Limited's exchange filing dated 29 May 2026 and from publicly available third-party sources (Screener.in, NSE/BSE aggregators, news reports); market-price-dependent figures such as yield must be re-verified against live data before acting. Dividend declaration is subject to shareholder approval at the AGM. Securities markets carry risk; past performance is not indicative of future results. Please consult a SEBI-registered adviser and read all offer/company documents before making any investment decision.