
Dividend Snapshot
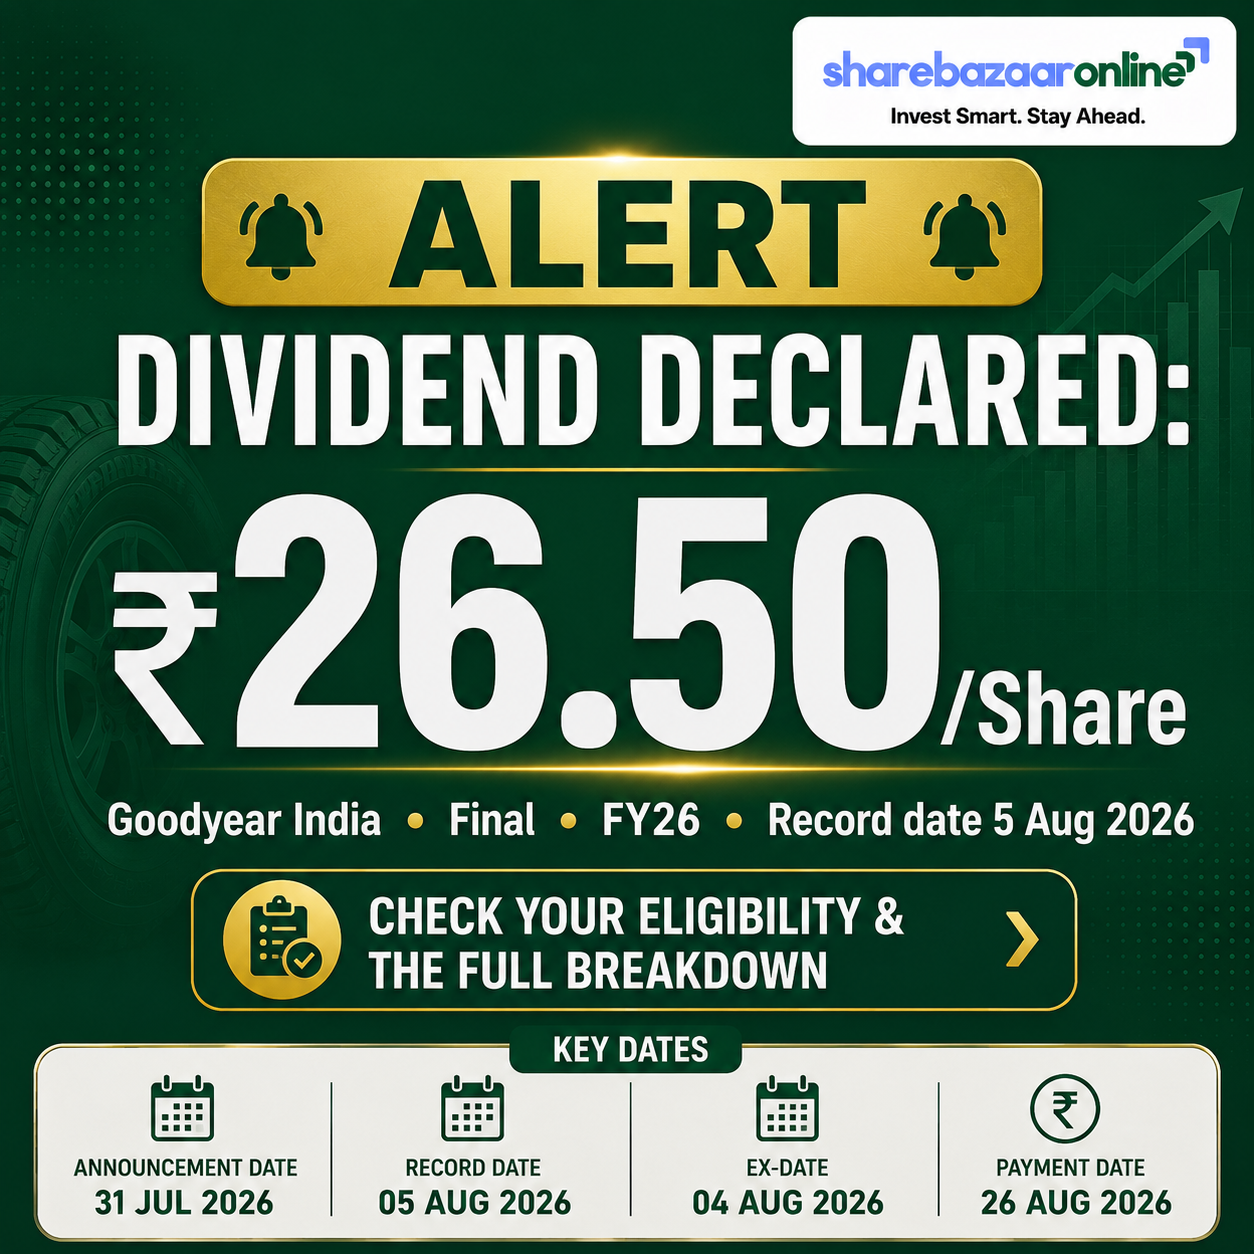
Dividend Per Share
₹26.50
Final Dividend • FY2025–26 • 265% of ₹10 face value
Dividend Yield (at CMP ₹781)
3.39%
Computed as ₹26.50 ÷ ₹781
Total Dividend Outflow
₹61.13 Crore
On ~2.31 crore shares (per company filing: ₹6,113 lakh)
Dividend Payout Ratio
99.4%
Of standalone FY26 net profit of ₹61.50 crore
| Company | Goodyear India Limited |
| ISIN | INE533A01012 |
| NSE / BSE | GOODYEAR / 500168 |
| Sector | Auto Components – Tyres & Rubber |
| Face Value | ₹10 |
| Dividend Type | Final Dividend |
| Financial Year | FY2025–26 (ended 31 Mar 2026) |
Dividend Announcement Summary
At its board meeting held on 28 May 2026, the Board of Directors of Goodyear India recommended a final dividend of ₹26.50 per equity share of face value ₹10 each, for the financial year ended 31 March 2026. The recommendation was made alongside the audited FY26 results and was placed for shareholder approval at the 65th Annual General Meeting held on 12 August 2026 (via video conference), where it was approved.
The dividend aggregates to ₹6,113 lakh (₹61.13 crore). It follows a full-year standalone net profit of ₹61.50 crore, up 11.6% from ₹55.12 crore in FY25 — the profit recovery came despite a fall in revenue, a point we analyse in the operating-leverage section below.
Alongside the results, the board also noted:
- Appointment of Mr Rohitashv Sharma as Whole-Time Director (KMP), effective 1 June 2026.
- A Q4FY26 exceptional charge of ₹19.83 crore (₹1,983 lakh) linked to implementation of the new Labour Codes.
- Resignation of the Internal Auditor, Mr Anurag Krishna.
Source: BSE Regulation 30/33/42 filings, board meeting 28 May 2026. Chairman & MD: Sandeep Mahajan.
Key Dates Timeline
| Event | Date | Status |
|---|---|---|
| Board Meeting / Announcement | 28 May 2026 | Completed |
| Ex-Dividend Date | 05 August 2026 | Passed |
| Record Date | 05 August 2026 | Passed |
| Annual General Meeting (65th) | 12 August 2026 | Approved |
| Payment Date | Within statutory 30 days of AGM | Not separately disclosed by company |
Because the record date (5 August 2026) has already passed, eligibility is now fixed. Shareholders whose names appeared in the Register of Members on the record date were entitled to the dividend. The exact payment/credit date was not separately disclosed by the company; under the Companies Act, 2013 dividend must be paid within 30 days of declaration at the AGM.
Dividend Yield Analysis
The 265% headline vs the real yield
Companies quote dividends as a percentage of face value. Goodyear’s “265% dividend” simply means ₹26.50 on a ₹10 face value. What lands in your bank account depends on the price you paid, not the face value. On the current market price the real yield is far lower:
“Coupon” on face value
265%
₹26.50 ÷ ₹10 — the misleading number
Real yield on market price
3.39%
₹26.50 ÷ ₹781 (CMP, 13 Aug 2026)
Yield reality check — why the yield looks high
A 3.39% yield is unusually high for a tyre stock. Two forces are at work. First, Goodyear has adopted a near-100% payout policy, distributing almost all of its profit. Second, the share price has fallen roughly 20% over the past year (from a 52-week high near ₹1,022 to about ₹781). A falling price mechanically lifts the yield even if the rupee dividend is flat. So part of this attractive yield is a symptom of price weakness, not just generosity — a distinction income investors should keep in mind.
At the approximate announcement-date price of ~₹750, the yield worked out to ~3.53%. Live CMP must be re-checked, as all yield figures move with price.
Dividend History Analysis
| FY | Ordinary / Final | Special | Total DPS | Payout % |
|---|---|---|---|---|
| FY26 | ₹26.50 | — | ₹26.50 | 99% |
| FY25 | ₹23.90 | — | ₹23.90 | 100% |
| FY24 | ₹15.00 | ₹26.00 | ₹41.00 | 100% |
| FY23 | ₹26.50 | — | ₹26.50 | 50% |
| FY22 | ₹20.00 | ₹80.00 | ₹100.00 | 224% |
| FY21 | ₹18.00 + ₹80.00 interim | ₹80.00 | ₹178.00 | 301% |
| FY20 | ₹13.00 | — | ₹13.00 | 34% |
| FY19 | ₹13.00 | — | ₹13.00 | 29% |
| FY18 | ₹13.00 | — | ₹13.00 | 23% |
| FY17 | ₹12.50 | — | ₹12.50 | 23% |
Dividends grouped by financial year of declaration. Source: exchange corporate-action records & Screener payout ratios (which reconcile with the DPS above).
What the history tells us
Goodyear India is a consistent payer — it has paid a dividend every single year for well over a decade. But the profile is lumpy, not steadily growing. The huge FY21–FY22 numbers (₹178 and ₹100) were inflated by one-time special dividends of ₹80 each that returned surplus cash to shareholders; they are not the recurring rate.
Strip out the specials and the picture is clearer: the base/final dividend has ranged between ₹12.50 and ₹26.50 over the last decade. This is why some data providers show a negative multi-year dividend growth rate — the base is being compared against the special-heavy peak years. The FY26 ₹26.50 is at the top of the ordinary range and up from ₹23.90 in FY25.
Financial Performance Analysis
| Metric (₹ Cr, standalone) | FY24 | FY25 | FY26 |
|---|---|---|---|
| Revenue | 2,552 | 2,608 | 2,476 |
| Operating Profit | 171 | 117 | 141 |
| OPM % | 7% | 4.5% | 5.7% |
| Net Profit (PAT) | 95 | 55 | 62 |
| EPS (₹) | 41.12 | 23.90 | 26.66 |
Operating leverage: profit up even as revenue fell
Here is the analytical headline most wire reports miss. In FY26, revenue fell about 5.1% (₹2,608 cr → ₹2,476 cr), yet operating profit rose about 20.5% (₹117 cr → ₹141 cr) and net profit grew 11.6%. Operating margin expanded from 4.5% to roughly 5.7%.
The reason is cost/margin recovery rather than volume growth — softer raw-material (natural rubber and crude-linked) costs and a better product mix lifted margins off the depressed FY25 base. That is a genuine positive: the earnings recovery is operational, not a one-off gain. Importantly, this happened despite a ₹19.83 crore Q4 exceptional charge for the new Labour Codes and a swing in “other income” to slightly negative for the year — so the underlying operating improvement was even larger than the reported PAT suggests.
The multi-year caveat
Zoom out and the trend is less flattering. Over five years, sales growth has been a modest ~6.7% and profit has actually compounded negatively — FY26 PAT of ₹62 cr is well below the ₹95–136 cr range seen in FY21–FY24. Return on equity has slipped to about 12.6% (3-year) and ROCE to about 17.4%, respectable but down from the 25%+ ROCE of earlier years. The FY26 result is a recovery off a weak base, not a return to peak earnings.
Cash Flow Analysis
Reported profit is an accounting opinion; cash is fact. Goodyear’s cash generation comfortably backs the dividend:
Operating Cash Flow (FY26)
₹112 Cr
vs PAT of ₹62 cr — healthy cash conversion
Free Cash Flow (FY26)
₹99 Cr
After ~₹13 cr capex — capex-light business
Is the dividend cash-funded? Yes.
The ₹61.13 crore dividend is covered 1.83x by operating cash flow and 1.62x by free cash flow. In other words, the company generated enough cash from operations, after capital spending, to pay the dividend and still retain a buffer. The dividend is funded by current cash generation, not by borrowings (the company is nearly debt-free) or by selling assets.
Cash conversion (OCF ÷ operating profit) was ~99% in FY26 — profits are converting into real cash. Receivables (debtor days ~42) and inventory (~54 days) are stable, with no red flag of profits being locked up in unpaid bills.
Balance Sheet Strength
Net Worth (Mar 2026)
₹606 Cr
Book value ~₹263/share
Net Cash Position
~₹236 Cr
Borrowings only ~₹27 cr — effectively debt-free
Strong — but the cash cushion is thinning
Goodyear India runs a fortress-style, near-debt-free balance sheet, and a net cash pile of about ₹236 crore gives it more than enough to defend the dividend. That is the good news.
The watch-point: net cash has fallen from about ₹384 crore (Mar 2025) to about ₹236 crore (Mar 2026) — a ~₹149 crore drop in a single year. With near-100% payouts, an income-tax demand of ₹30.31 crore (order received January 2026), and reserves that have drifted lower since FY20, the surplus is being drawn down rather than rebuilt. The balance sheet is strong today, but the direction of travel matters for how long specials or full payouts can continue.
Dividend Sustainability Analysis
| Coverage Test | Value | Result |
|---|---|---|
| Earnings coverage (EPS ÷ DPS) | 1.01x | Pass — razor thin |
| Operating cash flow coverage | 1.83x | Pass |
| Free cash flow coverage | 1.62x | Pass |
| Cash / liquidity coverage (net cash) | 3.85x | Pass |
Verdict: Moderately Sustainable
All four coverage tests technically pass, and cash flow plus the ₹236 crore net-cash buffer give the dividend a solid floor. But the earnings buffer is essentially zero: at a 99.4% payout, the company is distributing almost every rupee it earns. In FY24 and FY25 the payout hit 100%. That leaves no cushion for a bad year — any dip in profit (as in FY25) mathematically pushes the payout above 100%, funded from reserves.
So we classify it as Moderately Sustainable: cash-covered and balance-sheet-backed, but reliant on a near-full-payout policy with a shrinking cash surplus rather than on rising earnings. The dividend is safe on current cash; its growth depends squarely on an earnings recovery holding.
Peer Comparison
| Company | Div Yield | Payout | P/E | Debt |
|---|---|---|---|---|
| Goodyear India | ~3.4% | ~99% | ~29 | Debt-free |
| Apollo Tyres | ~1.3–1.4% | ~24 | Moderate | |
| CEAT | ~0.8–1.0% | ~27–31 | Moderate | |
| Balkrishna Inds (BKT) | ~1% | ~29 | Low | |
| MRF | ~0.1–0.3% | ~32 | Low |
Peer figures are approximate market data (mid-2026) and rounded; blank cells indicate figures not independently verified for this report. Yields move with price — verify before use.
On dividend yield, Goodyear India stands out as the highest-yielding listed tyre stock — roughly 3.4% against ~1.3% for Apollo, ~1% for CEAT and BKT, and a fraction of a percent for MRF (whose ultra-high share price crushes its yield despite large rupee dividends).
But the reason is structural, not a sign of superiority. Peers like Apollo, CEAT and BKT retain most of their earnings to fund growth and capacity expansion; Goodyear India, a mature single-plant farm-tyre specialist with limited capex needs, instead returns almost everything as dividend. High yield here reflects a low-growth, high-payout profile — attractive for income, less so for capital appreciation.
Promoter Impact Analysis
To Promoter (74%)
₹45.24 Cr
Goodyear parent (The Goodyear Tire & Rubber Co. group)
To Public + Institutions (26%)
₹15.89 Cr
Retail (~18%), DIIs (~8%), FIIs (~0.3%)
The US parent holds a stable 74% promoter stake, so nearly three-quarters of the ₹61.13 crore payout — about ₹45.24 crore — flows to the foreign promoter, with ₹15.89 crore shared among Indian retail and institutional holders. This alignment cuts both ways: the promoter benefits directly from high payouts (a reason the near-100% policy is likely to continue), but it also means the dividend policy is effectively a channel for the parent to repatriate India profits. Minority shareholders ride along on the same yield, but have little influence over whether cash is returned or reinvested for growth.
Taxation Analysis
How dividends are taxed in India (FY2025–26)
- Since April 2020 (DDT abolished), dividends are fully taxable in the shareholder’s hands at their slab rate under “Income from Other Sources”.
- TDS under Section 194 at 10% applies if total dividend from one company exceeds ₹10,000 in a financial year (threshold raised from ₹5,000 in Budget 2025). Without a valid PAN, TDS is 20%.
- TDS is only an advance credit — final tax is settled at your slab rate when you file your return.
- Only deduction allowed: interest on money borrowed to buy the shares, capped at 20% of the dividend (Section 57).
Worked example — 1,000 shares, 30% slab
| Gross dividend (1,000 × ₹26.50) | ₹26,500 |
| TDS deducted at source @10% (>₹10,000) | ₹2,650 |
| Total tax @31.2% (30% + 4% cess) | ₹8,268 |
| Net dividend after full tax | ₹18,232 |
| Effective post-tax yield (at CMP ₹781) | ~2.33% |
Illustrative; ignores surcharge for very high incomes and any Section 57 interest deduction. A 5% or 20% slab investor keeps more. Tax outcomes are individual — consult a qualified tax adviser.
Key Risks
- Near-100% payout leaves no earnings buffer. At a 99.4% payout ratio, a single weak year (like FY25) mechanically pushes the payout above 100%, forcing the dividend to be topped up from reserves.
- Raw-material and margin volatility. Natural rubber and crude-linked input prices swing sharply; FY25’s margin collapse to 4.5% shows how fast profitability can erode. The FY26 recovery depends on inputs staying benign.
- Demand cyclicality. Goodyear India is concentrated in farm/tractor tyres, which are tied to rural income, monsoon and agri-cycles; a weak farm cycle hits volumes directly, as seen in the soft FY26 top line.
- Tax and regulatory exposure. An income-tax demand of ₹30.31 crore (order in Jan 2026) and a ₹19.83 crore Labour Codes charge in Q4FY26 show the earnings can absorb sizeable one-off hits.
- Shrinking cash surplus. Net cash fell ~₹149 crore in FY26; if the drawdown continues, the room for special dividends or sustained full payouts narrows.
- Low growth & price weakness. Five-year sales growth of ~6.7% and negative profit CAGR, plus a ~20% share-price fall over the year, mean total returns lean heavily on the dividend rather than capital appreciation.
What To Monitor
- Operating margin trajectory. Watch whether OPM holds/improves above the FY26 ~5.7% — the Q1FY27 print (OPM ~1.3% on an exceptional-heavy quarter) is a reminder margins remain fragile.
- Natural rubber & crude prices. The single biggest swing factor for tyre profitability; falling inputs supported FY26, rising inputs would squeeze the payout capacity.
- Net cash trend. Track whether the ~₹236 crore net-cash balance stabilises or keeps falling — it underwrites the dividend’s safety.
- Payout ratio & any special dividend. Whether the board holds the near-100% policy, and whether surplus cash is returned via specials or retained.
- Farm/rural demand and tractor-tyre volumes. The core end-market; monsoon and rural sentiment drive Goodyear’s volume base.
- Resolution of the ₹30.31 crore tax matter and any further contingent liabilities in the annual report notes.
Conclusion
Goodyear India’s ₹26.50 final dividend delivers a genuinely attractive ~3.39% yield — the highest among listed tyre makers — and it is comfortably cash-funded, covered 1.6–1.8x by free and operating cash flow and backed by a near-debt-free balance sheet with ~₹236 crore of net cash.
Positives: consistent payer, strong cash conversion, debt-free, FY26 profit recovery driven by real margin gains, and a promoter (74%) structurally motivated to keep returning cash.
Negatives / risks: a razor-thin 99.4% earnings payout with no buffer, lumpy dividend history flattered by past specials, low multi-year growth, margin/input volatility, a shrinking cash surplus, and pending tax/regulatory charges.
Net: a solid income-yield story with limited growth. The dividend looks safe on current cash, but its future growth hinges on the earnings recovery sticking. We present the facts, positives and risks — the decision is yours.
Frequently Asked Questions
What dividend has Goodyear India announced for 2026?
What is the Goodyear India dividend yield?
What was the record date for the Goodyear India dividend?
What was the ex-dividend date?
When will the Goodyear India dividend be paid?
Who was eligible for the dividend?
How is the Goodyear India dividend taxed?
Is the Goodyear India dividend sustainable?
What is Goodyear India’s dividend history?
What is the dividend payout ratio?
Why did profit rise when revenue fell in FY26?
How much of the dividend goes to the promoter?
What should investors monitor going forward?
Disclaimer
ShareBazaar Online is not a SEBI-registered investment adviser or research analyst. This article is for informational and educational purposes only and does not constitute investment, financial, legal or tax advice, nor a buy/sell/hold recommendation. Figures are computed from company filings and publicly available data believed reliable but not guaranteed; all market prices, yields and dates should be independently verified before acting. Dividend declarations and payments are subject to statutory approvals and taxation rules that may change. Investments in securities are subject to market risks. Please read all related documents carefully and consult a SEBI-registered adviser and a qualified tax professional before making any investment decision. ShareBazaar Online and its authors accept no liability for any loss arising from the use of this information.