
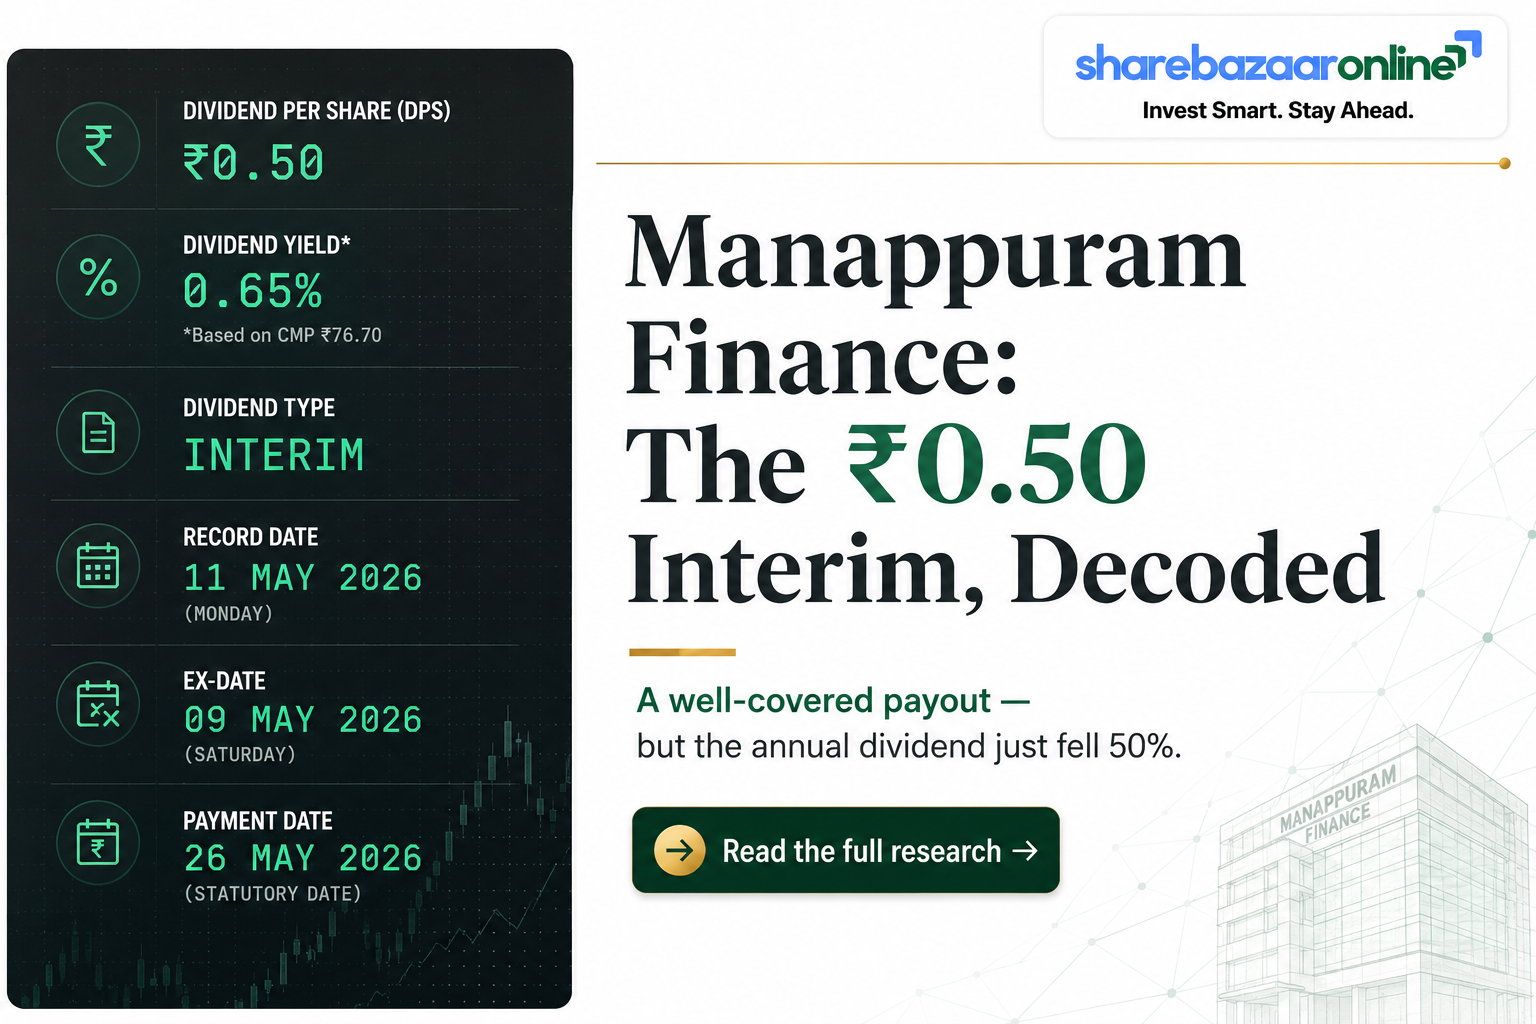
Dividend Snapshot
Manappuram Finance Limited has declared a 4th interim dividend of ₹0.50 per equity share (25% on face value of ₹2) for the financial year 2025-26. This is the final leg of the FY26 payout cycle, announced alongside the audited Q4 and full-year results on 4 May 2026. The headline number many trackers miss: the company has halved its quarterly dividend versus last year, taking the full-year FY26 payout down to ₹2.00 per share from ₹4.00 in FY25.
Dividend Per Share
₹0.50
Interim (25% of ₹2 face value)
Interim Dividend Yield
~0.14%
On latest CMP ~₹363.60 (this instalment only)
FY26 Total Dividend
₹2.00
Four interims (down from ₹4.00 in FY25)
FY26 Trailing Yield
~0.55%
₹2.00 ÷ ~₹363.60 latest CMP
Record Date
11 May 2026
Ex-date also 11 May 2026 (T+1)
Payout Ratio (FY26)
~18.7%
On consolidated PAT attributable to owners
The one-line takeaway: This is a well-covered, conservative payout from a cash-rich gold-loan lender — but investors chasing "yield" should note the per-share dividend has been cut 50% year-on-year, reflecting a weaker consolidated profit (dragged by the microfinance subsidiary) and a deliberate shift towards conserving capital after a large equity infusion from Bain Capital.
Dividend Announcement Summary
At its board meeting held on 4 May 2026 (11:00 a.m. to 4:15 p.m.), the Board of Directors of Manappuram Finance Limited approved the audited standalone and consolidated financial results for Q4 and the year ended 31 March 2026, and declared a 4th interim dividend of ₹0.50 per equity share of face value ₹2 each. The intimation was filed with BSE (Scrip Code 531213), NSE (MANAPPURAM) and India International Exchange under Regulations 30, 42, 51 and 52 of the SEBI Listing Regulations.
Key facts from the filing
- Dividend type: Interim (does not require AGM approval)
- Amount: ₹0.50 per share (25%)
- Face value: ₹2
- Record date: Monday, 11 May 2026
- This is the 4th interim for FY26; three earlier interims totalling ₹1.50 were already paid
Why it is an "interim", not "final"
Manappuram has moved to a quarterly interim dividend model. Because all four FY26 payouts are interim dividends declared by the Board, no separate shareholder/AGM approval is required for the dividend itself. The 34th AGM (scheduled 12 August 2026) will ratify accounts but does not need to approve these interim dividends.
Not Disclosed by Company: A specific dividend payment/dispatch date was not stated in the board outcome. Under the Companies Act, 2013, an interim dividend must be paid within 30 days of declaration — i.e., on or before approximately 3 June 2026 as a statutory outer limit, not a company-confirmed date.
Key Dates Timeline
Announcement Date
04 May 2026
Board meeting & Q4/FY26 results
Ex-Dividend Date
11 May 2026
Buy before this date to qualify
Record Date
11 May 2026
Shareholders on register are eligible
Payment Date
On/before ~03 Jun 2026
Statutory 30-day limit (Not Disclosed by Company)
Note on ex-date = record date: Under India's T+1 settlement cycle, the ex-date and record date fall on the same day (11 May 2026). To receive this dividend, an investor must have purchased the shares on or before 8 May 2026 (the last cum-dividend trading day, allowing for weekends). Selling on or after 11 May 2026 still preserves eligibility.
Dividend Yield Analysis
Yield tells you what cash return the dividend represents relative to the share price. Because Manappuram's stock has rallied sharply — up roughly 45% over the past year to a 52-week high near ₹381 — the yield looks compressed. A rising price shrinks the yield even when the rupee dividend is unchanged. Here, both effects work against yield: a lower dividend and a higher price.
This interim (₹0.50)
- At latest CMP ~₹363.60: ~0.14%
- At announcement CMP ~₹313: ~0.16%
FY26 full-year (₹2.00)
- At latest CMP ~₹363.60: ~0.55%
- At announcement CMP ~₹313: ~0.64%
Yield reality check
Several data aggregators still show a trailing yield of 1.0–1.4% for Manappuram. That figure is backward-looking — it blends in the higher ₹1.00-per-quarter payments from FY25. On a forward, run-rate basis (₹0.50 × 4 = ₹2.00), the yield is closer to ~0.55%. Manappuram is not a high-yield stock; the payout is a modest, symbolic return of cash, with the equity thesis resting on gold-loan growth, not income.
Dividend History Analysis
Manappuram has a long, consistent record of paying dividends, having moved to a quarterly cadence in recent years. But FY26 marks a clear step-down in the per-share amount — the quarterly dividend was cut from ₹1.00 to ₹0.50, the first meaningful reduction in years.
Dividend per share by financial year (face value ₹2)
| Financial Year | Total DPS (₹) | Cadence | Trend |
|---|---|---|---|
| FY2025-26 | 2.00 | 4 × ₹0.50 interim | Cut ~50% |
| FY2024-25 | 4.00 | 4 × ₹1.00 interim | Peak |
| FY2023-24 | 3.30 | ₹0.75/0.80/0.85/0.90 | Rising |
| FY2022-23 | ~3.00 | Quarterly | Steady |
| 10-yr history | ₹1.50 (FY13) → ₹4.00 (FY25) | Long-term growth | ~8.5% CAGR |
Figures compiled from exchange dividend records and third-party dividend trackers; per-share amounts on the current ₹2 face value. FY26 total reflects company disclosure (three interims of ₹1.50 paid + 4th interim ₹0.50).
Classification
Manappuram is a Consistent Payer with an uninterrupted multi-year record. However, FY26 introduces a watch flag: the payment is consistent, but the amount was reduced, so the recent trajectory is best described as "consistent frequency, reduced quantum."
Why the cut matters
The reduction is not a distress signal from the gold-loan core — it lines up with (a) a weaker consolidated profit due to microfinance losses, (b) a much larger share count after the Bain Capital equity issue, and (c) a preference to conserve capital for growth. It is a deliberate capital-allocation choice rather than an inability to pay.
Financial Performance Analysis
Manappuram reports two very different pictures. The standalone parent (the gold-loan business) is healthy and highly profitable. The consolidated group is weighed down by Asirvad Micro Finance, the microfinance subsidiary that posted large losses. Reading only the consolidated headline — or only the standalone — gives a misleading view.
Key numbers (₹ Crore, year ended 31 March)
| Metric | FY26 | FY25 | Change |
|---|---|---|---|
| Consolidated total income | 9,524.68 | 10,031.15 | -5.0% |
| Consolidated PAT (owners) | 1,003.30 | 1,216.15 | -17.5% |
| Standalone total income | 7,653.42 | 6,914.46 | +10.7% |
| Standalone PAT | 1,524.65 | 1,783.26 | -14.5% |
| Consolidated EPS (basic) | ₹11.72 | ₹14.22 | Lower |
| Standalone EPS (basic) | ₹17.99 | ₹21.07 | Lower |
Segment profit before tax (₹ Crore) — the real story
| Segment | FY26 PBT | FY25 PBT | Read |
|---|---|---|---|
| Gold loan & others | 2,105.96 | 2,476.65 | Profitable, softened ~15% |
| Microfinance | (835.78) | (811.01) | Deep loss — the drag |
The gold-loan engine earned over ₹2,100 crore of PBT; the microfinance arm lost over ₹800 crore, pulling group profit down.
Operating leverage read
On a standalone basis, revenue rose +10.7% yet PAT fell -14.5%. The gap is explained mainly by higher finance costs (standalone finance costs up to ₹3,028 crore from ₹2,376 crore, +27%) as borrowings expanded to fund a fast-growing loan book, plus higher impairment and employee costs. In short: the business is growing volumes but paying more to borrow, squeezing the bottom line even as the top line expands. Note that FY26 also recovered strongly in Q4 — consolidated Q4 PAT of ₹404 crore reversed a ₹191 crore loss in the year-ago quarter.
Cash Flow Analysis
This is where retail investors most often misread an NBFC. Manappuram's consolidated operating cash flow for FY26 was negative ₹20,237.74 crore. For a manufacturing company that would be alarming. For a lender, it is normal and even a sign of growth.
Why OCF is deeply negative
In an NBFC, loan disbursements are classified within operating activities. Manappuram's consolidated loan book grew ~48.7%, from ₹42,252 crore to ₹62,844 crore — roughly ₹20,592 crore of net new lending. That cash going out the door as loans is what makes OCF negative. It is capital deployed into an income-earning asset, not cash lost.
How the dividend is actually funded
The ₹169.29 crore of dividend paid in FY26 (cash flow statement) is funded out of current profits and the financing pool — fresh borrowings (₹+17,619 crore net) and the ₹2,740 crore Bain Capital equity infusion. This is standard NBFC treasury practice; the dividend is a small fraction of the group's liquidity.
The correct lens for a lender
For NBFCs, free cash flow (FCF) and OCF coverage are structurally meaningless for judging dividend affordability — lending disbursements dominate the operating line. The right affordability metrics are capital adequacy, earnings, and liquidity buffers, all of which are strong here (standalone Capital Adequacy Ratio 21.30% and Liquidity Coverage Ratio 306.45%). Do not read negative OCF as an inability to pay the dividend.
Balance Sheet Strength
Manappuram enters FY27 with a materially stronger balance sheet after the Bain Capital capital raise. Consolidated total assets stand at ₹74,559 crore, up from ₹49,205 crore a year earlier.
Cash + Bank + Investments (cons.)
~₹8,200 Cr
Cash ₹5,048 Cr + bank ₹1,101 Cr + investments ₹2,051 Cr
Net Worth (standalone)
₹15,937.51 Cr
Up from ₹11,793 Cr (Bain infusion)
Debt-Equity (standalone)
3.18x
Comfortable for an NBFC; consolidated ~3.6x
Capital Adequacy (standalone)
21.30%
Well above regulatory minimum
Cash coverage of the dividend
Consolidated cash, bank balances and investments of ~₹8,200 crore cover this ₹46.97 crore interim outflow roughly 175 times over, and the full FY26 dividend outflow of ~₹188 crore about 44 times over. Affordability is not in question. The one balance-sheet caveat is the note-6 disclosure that subsidiary Asirvad Micro Finance breached certain covenants (NNPA and quarterly profitability) on its debentures as at 31 March 2026 — a subsidiary-level stress point to monitor.
Dividend Sustainability Analysis
We apply a four-test framework, adapted for an NBFC (where FCF/OCF coverage is not meaningful and is replaced by capital and liquidity tests).
Test 1 — Earnings coverage
Pass. FY26 payout ratio is ~18.7% on consolidated PAT (owners) and just ~12.3% on standalone PAT. Coverage is 5.9x consolidated and 9.0x standalone (EPS ÷ DPS). Deeply covered.
Test 2 — Capital adequacy (NBFC proxy for OCF/FCF)
Pass. Standalone CRAR of 21.30% is comfortably above the regulatory floor, and the Bain infusion adds a fresh buffer. Paying the dividend does not threaten capital.
Test 3 — Liquidity coverage
Pass. Standalone LCR of 306.45% and ~₹8,200 crore of cash/investments cover the FY26 dividend ~44x. Liquidity is abundant.
Test 4 — Earnings trend
Watch flag. Consolidated PAT fell 17.5% and the dividend was already halved. The trend, not the coverage, is the concern.
Verdict: Sustainable (with a growth-trend watch flag)
The current ₹0.50 quarterly / ₹2.00 annual dividend is very comfortably affordable from earnings, capital and liquidity. The risk is not that the company cannot pay — it is that management has already shown willingness to cut the per-share amount when consolidated profit weakens. Sustainability of the rupee amount depends heavily on the microfinance subsidiary returning to profit.
Peer Comparison
Manappuram vs Muthoot Finance (primary gold-loan peer)
| Parameter | Manappuram | Muthoot Finance |
|---|---|---|
| FY26 dividend per share | ₹2.00 (FV ₹2) | ~₹30.00 (FV ₹10) |
| Approx. dividend yield | ~0.55% | ~0.85% |
| Dividend trajectory | Cut vs FY25 | Raised vs FY25 |
| Payout ratio (approx.) | ~18-19% (cons.) | ~20% |
| Recent profit trend | Declined (micro drag) | Strong growth |
| Business mix | Gold + micro + others | Predominantly gold |
| ROE (approx.) | ~11% standalone / ~7% cons. | High-teens / low-20s% |
Peer figures sourced from public market data and are approximate; cells left qualitative where an exact, verified figure was not available. Muthoot has a higher face value (₹10) so its rupee DPS is not directly comparable to Manappuram's.
The peer takeaway
The contrast is instructive: in FY26, Muthoot raised its dividend on the back of strong gold-loan-led profit growth, while Manappuram cut its dividend as microfinance losses dragged the group. Both run conservative payout ratios around 18-20%, but the direction of the payout signals divergent momentum. Neither is a high-yield income stock; both are growth-plus-modest-income plays on gold lending.
Promoter Impact Analysis
The promoter group's stake changed materially in FY26 because Bain Capital became a joint promoter following its ~₹2,740 crore equity infusion (part of a larger ~₹4,385 crore commitment for an 18% fully-diluted stake). Latest available data puts total promoter holding at approximately 41.7%.
Shareholding (latest available)
- Promoters (incl. Bain): ~41.7%
- FII/FPI: ~22.3%
- DII: ~14.9%
- Public/retail: ~21.2%
Percentages are from third-party trackers for the most recent reported quarter and may shift as new filings are released.
Promoter dividend income (estimate)
- From this ₹0.50 interim: ~₹19.6 crore
- From FY26 total (₹2.00): ~₹78.3 crore
Estimated as promoter % × total dividend outflow (₹46.97 cr interim; ~₹187.87 cr full-year on year-end share count).
Alignment read
Roughly 42 paise of every rupee distributed flows to promoters (including Bain), and the balance to public, FII and DII shareholders. Because the payout is modest and pro-rata, minority shareholders receive the same per-share dividend as promoters — there is no preferential distribution. With a large new financial-sponsor promoter (Bain), future capital-return policy may lean towards reinvestment for growth over generous distributions, consistent with the FY26 dividend cut.
Taxation Analysis
Since the abolition of the Dividend Distribution Tax (FY2020-21), dividends are taxed in the hands of the investor at their applicable income-tax slab rate. The company also deducts TDS before payment in certain cases.
The rules in brief
- Dividend added to "Income from Other Sources", taxed at your slab rate
- TDS at 10% under Section 194 applies only if total dividend from the company in a financial year exceeds ₹5,000
- No TDS if you submit Form 15G/15H (where eligible) or PAN is furnished and threshold not crossed
- Without PAN, TDS is deducted at 20%
Worked example — 1,000 shares, 30% slab
- Gross dividend (this interim): 1,000 × ₹0.50 = ₹500
- TDS: NIL (₹500 is below the ₹5,000 threshold)
- Tax at 30% slab: ₹500 × 30% = ₹150
- Net in hand after tax: ₹350
- Effective post-tax yield on ₹363.60 price: ~0.10%
Full-year view: On 1,000 shares, the FY26 total dividend of ₹2.00/share = ₹2,000 gross — still below the ₹5,000 TDS threshold, so no TDS would apply for a typical small investor. A 30%-slab investor would pay ₹600 tax and keep ₹1,400. Tax rules are general and individual liability depends on total income; consult a tax adviser for your specific situation.
Key Risks
- Microfinance (Asirvad) drag: The subsidiary posted a segment loss of ~₹836 crore in FY26 and breached certain debenture covenants (NNPA, quarterly profitability). Continued microfinance stress directly threatens consolidated profit and the rupee dividend amount.
- Dividend-cut precedent: Management has already halved the per-share dividend once (FY25 ₹4.00 → FY26 ₹2.00). This shows a clear willingness to reduce distributions when profits soften, so the payout is not a fixed commitment.
- Rising funding costs: Standalone finance costs jumped ~27% year-on-year to ₹3,028 crore. If borrowing costs keep climbing faster than lending yields, net interest margins — and dividend capacity — compress.
- Gold-price and regulatory sensitivity: As a gold-loan lender, earnings are exposed to gold-price swings (loan-to-value and auction recoveries) and to RBI rule changes on gold lending, LTV caps and provisioning.
- Yield compression / valuation: The stock trades near its 52-week high after a ~45% one-year run. A modest ~0.55% yield offers little downside cushion if growth disappoints, and the equity story is priced for continued expansion.
- Ownership transition: Bain Capital's arrival as a co-promoter (with a mandatory open offer for a further stake) introduces governance and strategy changes whose capital-return implications are still unfolding.
What To Monitor
- Asirvad microfinance turnaround: Watch quarterly microfinance segment PBT and NPA trends — a return to profit is the single biggest driver of whether the group dividend can rise again.
- Standalone gold-loan AUM and margins: Track gold-loan book growth, net interest margin and the gap between lending yields and rising finance costs.
- Dividend cadence and quantum: Note whether the quarterly interim stays at ₹0.50 or is restored towards prior levels — the trajectory signals management's capital-return intent.
- Capital adequacy and leverage: Follow CRAR and consolidated debt-equity as the loan book scales and as the remaining Bain warrant money (~₹1,644 crore) is called.
- Asset quality (GNPA/NNPA): Monitor group and subsidiary NPA ratios; covenant compliance at Asirvad is a specific item to track quarter-on-quarter.
- Bain Capital integration: Watch the open-offer completion, board/strategy changes and any stated capital-allocation policy from the new promoter group.
Conclusion
Manappuram's 4th interim dividend of ₹0.50 per share is a comfortably affordable, conservatively covered payout from a cash-rich, capital-strong gold-loan lender. On every affordability test that matters for an NBFC — earnings coverage (~5.9x), capital adequacy (21.30%), liquidity (LCR 306.45%, ~44x cash cover) — the dividend passes clearly.
The subtler story — the one aggregators miss — is that the per-share dividend has been halved (FY25 ₹4.00 → FY26 ₹2.00) even as the balance sheet strengthened. That reflects a genuine 17.5% fall in consolidated profit driven by microfinance losses, a larger post-Bain share count, and a deliberate tilt towards conserving capital for growth. The gold-loan core remains a ₹2,100-crore-plus profit engine; the microfinance arm is the swing factor.
Positives • Negatives at a glance
Positives
- Very well-covered, low-payout dividend (~18.7%)
- Strong liquidity and capital after Bain infusion
- Long, consistent dividend-paying record
- Gold-loan core highly profitable, Q4 recovery strong
Negatives / watch-outs
- Dividend cut 50% year-on-year
- Consolidated PAT down 17.5%; microfinance losses
- Low forward yield (~0.55%); stock near highs
- Subsidiary covenant breach; rising funding costs
This piece presents the facts, the analysis and the risks so you can decide for yourself. It does not contain any buy, sell or hold recommendation.
Frequently Asked Questions
What dividend has Manappuram Finance announced?
What is the dividend yield?
What is the record date for this dividend?
What is the ex-dividend date?
When will the dividend be paid?
Who is eligible to receive this dividend?
How is this dividend taxed?
Is the dividend sustainable?
What is Manappuram's dividend history?
Why did Manappuram cut its dividend this year?
Why is the operating cash flow negative if the company is profitable?
How does Manappuram compare with Muthoot Finance on dividends?
Does this interim dividend need AGM approval?
What should investors monitor going forward?
Disclaimer
This article is published by ShareBazaar Online for informational and educational purposes only. It is not investment advice and does not constitute a buy, sell or hold recommendation. ShareBazaar Online is not a SEBI-registered investment adviser or research analyst. Figures sourced from the company's exchange filings are stated as disclosed; market prices, yields, shareholding percentages and peer metrics are drawn from third-party sources, are approximate, and change continuously — all yield figures are price-dependent and go stale quickly. Items that could not be independently verified from primary sources are labelled accordingly (e.g., "Not Disclosed by Company"). Investors should verify the live market price, confirm dates against the official exchange corporate-action circular, and consult a SEBI-registered adviser and a qualified tax professional before making any decision. Investments in securities are subject to market risks; please read all related documents carefully.