
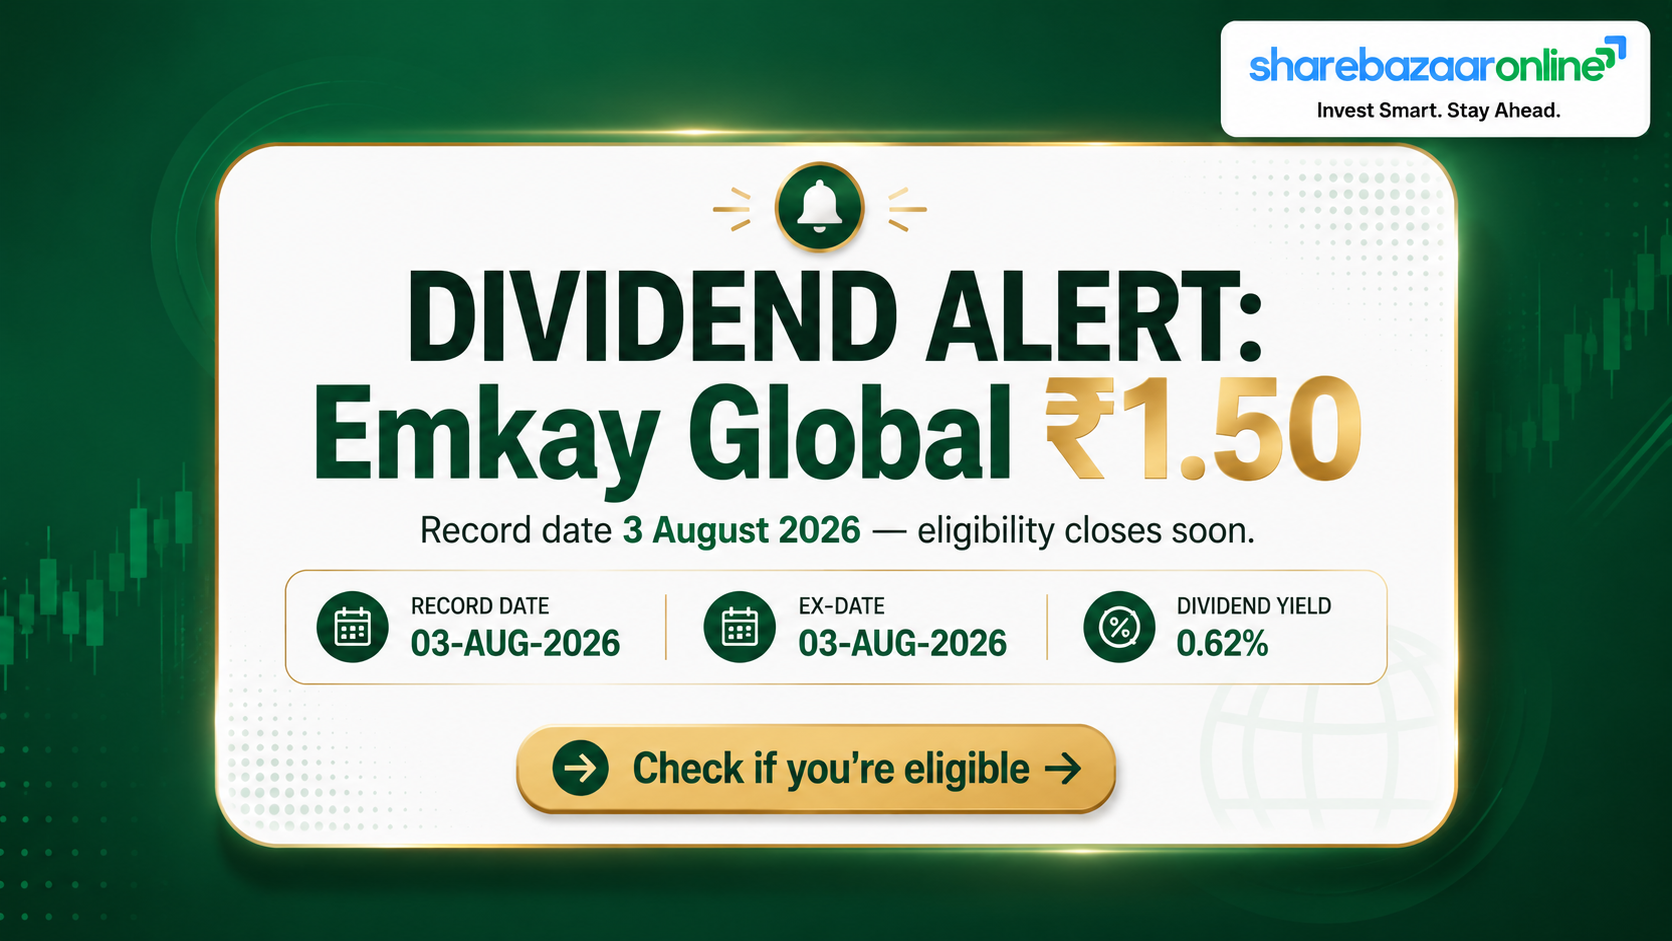
Dividend Snapshot
Dividend Per Share
₹1.50 (15% on ₹10 face value)
Type: Final Dividend · Financial Year: FY2025-26
Dividend Yield (approx.)
~0.62%
At CMP ₹243 (Not Independently Verified — re-verify at publish)
Record Date
03 August 2026
Ex-date 03 August 2026 (under T+1, ex-date = record date)
Approval Status
Subject to AGM
32nd AGM: 10 August 2026 (via VC/OAVM)
The one line most reports miss: This ₹1.50 payout is a 62.5% cut from the ₹4.00 per share paid for FY2024-25 — declared in a year when consolidated net profit fell 73% to ₹15.20 crore even as revenue grew 12%. Emkay is signalling caution, not distress: the dividend is still covered 3.95 times by earnings, and the company sits on roughly ₹85 crore of its own liquid resources against a ₹4 crore payout.
Dividend Announcement Summary
At its board meeting on 15 May 2026, the Board of Directors of Emkay Global Financial Services Limited recommended a final dividend of ₹1.50 per equity share (15% on the ₹10 face value) for the year ended 31 March 2026. In the same intimation to NSE and BSE (under SEBI LODR Regulations 30, 33 and 52), the Board also approved audited standalone and consolidated results, the issuance of Non-Convertible Debentures (NCDs) up to ₹100 crore, and an increase in borrowing limits to ₹1,000 crore — both of the latter subject to shareholder approval.
Company Identifiers
- NSE Symbol: EMKAY
- BSE Code: 532737
- ISIN: INE296H01011
- CIN: L67120MH1995PLC084899
- Sector: Capital Markets / Broking
Board Commentary (as disclosed)
The filing states the dividend is "payable subject to the approval of the shareholders at the ensuing Annual General Meeting." No separate management narrative on the dividend rationale was disclosed in the outcome letter. (No qualitative dividend-policy commentary disclosed by the company.)
Key Dates Timeline
Announcement (Board Meeting)
15 May 2026
Record Date
03 August 2026 (Monday)
Ex-Dividend Date
03 August 2026
Under India's T+1 settlement, ex-date and record date now fall on the same day.
AGM (Shareholder Approval)
10 August 2026, 4:30 PM (VC/OAVM)
e-Voting Window
07–09 August 2026
Payment Date
Not Disclosed by Company
Statutory outer limit: within 30 days of AGM declaration (i.e., on or before ~09 September 2026). In prior years Emkay paid around 7–10 September.
Dividend Yield Analysis
Yield at Current Price
~0.62%
₹1.50 ÷ ₹243 CMP (re-verify at publish)
Yield on Announcement Date
~0.77%
₹1.50 ÷ ₹195.45 (NSE/BSE close, 15 May 2026)
Yield Reality Check
At roughly 0.62%, Emkay is not an income/dividend stock — the yield sits well below a bank fixed deposit. Importantly, this modest yield is not the "high-yield-from-a-falling-price" trap: even though the share has fallen more than 40% from its 52-week high of ₹409.90, the yield stayed low because the company simultaneously reduced the dividend from ₹4.00 to ₹1.50. In other words, the payout cut offset the price fall. The stock is owned for potential capital appreciation in a recovering broking cycle, not for income.
Dividend History Analysis
| Financial Year (paid) | Dividend / Share | Type |
|---|---|---|
| FY26 (2026) | ₹1.50 | Final |
| FY25 (2025) | ₹4.00 | Final |
| FY24 (2024) | ₹1.50 | Final |
| FY23 (2023) | ₹1.00 | Final |
| FY22 (2022) | ₹1.25 | Final |
| FY21 (2021) | ₹1.00 | Final |
| FY20 (2020) | NIL | Skipped (COVID) |
| FY19 (2019) | ₹1.00 | Final |
| FY18 (2018) | ₹2.00 | Final |
Source: TipRanks / exchange corporate-action records. FY25 ₹4.00 figure independently cross-checked against the ₹10.23 crore "dividend paid" line in the FY26 consolidated cash-flow statement (₹4.00 × ~2.56 crore shares ≈ ₹10.24 crore). Some aggregators show ₹1.50 or ₹2.50 for FY25 — treat those as data errors.
Classification: Cyclical Payer
Emkay has paid a dividend in most years since 2016, but the amount tracks the broking cycle rather than a fixed policy: it skipped FY20 entirely, ranged between ₹1.00 and ₹2.00 through the mid-cycle, spiked to ₹4.00 in the strong FY25, and has now been pulled back to ₹1.50 in the weak FY26. This is the behaviour of a profit-linked, discretionary payer — investors should not assume ₹1.50 (or any figure) is a floor.
Financial Performance Analysis
| Consolidated (₹ crore) | FY26 | FY25 | Change |
|---|---|---|---|
| Revenue from Operations | 376.96 | 336.17 | +12.1% |
| Total Income | 396.29 | 361.24 | +9.7% |
| Total Expenses | 375.10 | 300.51 | +24.8% |
| Profit Before Tax | 21.19 | 60.73 | −65.1% |
| Net Profit (owners) | 15.20 | 56.83 | −73.3% |
| EPS (Basic) | ₹5.92 | ₹22.80 | −74.0% |
| Operating Margin | 5.62% | 18.07% | −12.5 pp |
| Net Profit Margin | 4.03% | 15.91% | −11.9 pp |
Operating Leverage: revenue rose, profit collapsed — here's exactly why
This is the single most important thing to understand about Emkay's FY26. Revenue actually grew 12%, but profit fell 73%. The gap is pure margin compression, driven by three cost lines rising far faster than income:
- Fees & commission expense surged +156.7% — from ₹30.04 crore to ₹77.10 crore. This is the dominant drag and points to a shift in business mix (higher pass-through / distribution costs).
- Finance costs rose +86% — from ₹6.97 crore to ₹12.96 crore, reflecting higher borrowings and NCD interest.
- Employee benefits rose +10.4% — from ₹170.86 crore to ₹188.64 crore, still the largest single cost bucket.
The pain was front-loaded: quarterly consolidated profit collapsed to ₹0.46 crore in Q2 (Sep 2025, −98% YoY) before recovering to ₹4.30 crore in Q3 and ₹5.66 crore in Q4. Segment data confirms the story — the core Advisory & Transactional segment's profit fell ~77% (₹53.19 crore → ₹12.49 crore), while the tiny Financing & Investment arm contributed ₹8.70 crore, or 41% of the ₹21.19 crore total segment PBT.
Cash Flow Analysis
Operating Cash Flow (FY26, consol)
−₹71.73 cr
vs Net Profit of +₹15.20 cr
Free Cash Flow (OCF − capex)
−₹80.49 cr
Capex ₹8.76 cr
Don't panic at the negative number — read it correctly
A negative operating cash flow next to a positive profit would normally be a serious red flag. For a stockbroker, it usually is not. The FY26 negative OCF is almost entirely a working-capital artifact of a growing broking book, not cash being burned:
- Bank balances (other than cash) rose ₹374.6 crore — a cash outflow in the statement.
- This was matched by a ₹373.2 crore rise in "other financial liabilities" — largely client/fiduciary payables — a cash inflow.
- These two lines essentially net each other out: the company is holding more client money and parking it in banks. That inflates the balance sheet on both sides without reflecting the firm's own operating health.
Bottom line: conventional FCF-coverage tests are unreliable for broking businesses. The dividend of roughly ₹4 crore is trivial against the company's own liquid resources of about ₹85 crore (cash ₹47.49 cr + investments ₹37.97 cr). Do not read "dividend not covered by FCF" as "dividend unaffordable" here.
Balance Sheet Strength
Net Worth (Consolidated)
₹380.67 cr
+25.6% YoY (from ₹303.17 cr)
Debt-to-Equity
0.24
Up from 0.15 — still conservative
Current Ratio
1.29
Comfortable short-term liquidity
Book Value / Share
~₹145
Net worth ÷ shares outstanding
The balance sheet strengthened even as profits fell — net worth grew 25.6%, boosted by preferential warrant issuance to promoters (₹239.50 per warrant, ₹56.88 crore already received against warrants) and ongoing equity infusions. Debt remains low at a D/E of 0.24. The flip side of that capital raising is dilution and rising finance costs, and the AGM will separately seek approval to raise borrowing limits to ₹1,000 crore and issue up to ₹100 crore of NCDs. Note the company also carries contingent liabilities of about ₹436 crore (per Screener) — standard for a broker, but worth monitoring.
Dividend Sustainability Analysis
1. Earnings Coverage
EPS ₹5.92 ÷ DPS ₹1.50 = 3.95× cover (payout 25.3%). PASS. Even after a 73% profit fall, earnings comfortably fund the reduced dividend.
2. Operating Cash Flow Coverage
OCF was negative (−₹71.73 cr). NOT MEANINGFUL for a broker — distorted by client-balance movements (see Cash Flow section).
3. Free Cash Flow Coverage
FCF negative on the same working-capital basis. NOT MEANINGFUL as a stand-alone test for this business model.
4. Balance-Sheet / Cash Coverage
Own liquid resources ~₹85 cr ÷ ₹4 cr outflow = ~21.8× cover. STRONG PASS.
Verdict: Sustainable (at the reduced level)
The ₹1.50 dividend is easily affordable — covered nearly 4× by earnings and ~22× by own cash. The genuine caveat is not affordability but direction: management has already shown it will cut sharply when profits fall (₹4.00 → ₹1.50). Watch flag: if FY27 earnings stay depressed, the dividend could be trimmed again; if broking activity recovers, it could rise. Treat the payout as variable and profit-linked, not fixed.
Peer Comparison
| Company | Div. Yield | Payout | ROE (FY26) | Notes |
|---|---|---|---|---|
| Emkay Global | ~0.62% | 25.3% | ~4–5%* | Small-cap; profit reset in FY26 |
| Motilal Oswal | ~0.73% | — | 14.9% | Diversified; ₹6 final + ₹6 interim |
| Angel One | ~1.98% | 25.9% | — | Discount broker; ₹34.7 total |
| Geojit Financial | ~2.62% | — | — | Higher-yield retail broker |
| IIFL Securities | — | — | — | Data not independently verified |
Blank cells left intentionally where figures could not be verified from primary sources. *Emkay FY26 ROE approximated from PAT ÷ average net worth; its 3-year average ROE is ~12% (Screener), so FY26 is a depressed, atypical year. ROCE is not shown as it is not a meaningful metric for a financial-services intermediary.
Emkay's yield sits at the bottom of the broking pack. Retail-focused peers such as Geojit (~2.6%) and Angel One (~2.0%) offer materially more income. Emkay is closer to the growth-oriented Motilal Oswal on yield, but without Motilal's scale, diversification, or FY26 profitability. For income seekers, Emkay is the least attractive of this group; the investment case rests on a cyclical earnings recovery, not the dividend.
Promoter Impact Analysis
Promoter Holding
~72.8%
Rising (72.21% in Mar-26) via warrant conversions
Estimated Promoter Dividend Income
~₹3.02 cr
72.8% of ~₹4.14 cr total outflow
Of the estimated ₹4.14 crore total dividend outflow (on the enlarged, record-date share count), roughly ₹3.02 crore flows to promoters and about ₹1.13 crore to the ~27% public float. With promoter holding of ~72.8% (FII 0.84%, DII ~0.05%), this is a highly promoter-concentrated company. Two nuances matter for minority holders: (1) promoters have recently increased their stake via preferential warrants at ₹239.50 — a vote of confidence, but also a source of dilution for existing holders; (2) because promoters own nearly three-quarters of the equity, dividend policy overwhelmingly serves promoter cash needs, and the sharp FY26 cut shows the payout is managed tightly around profitability rather than to reward the small public float.
Taxation Analysis
Since April 2020, dividends in India are taxed in the hands of the investor. Key rules:
- Dividend is added to your total income and taxed at your applicable income-tax slab rate.
- TDS under Section 194 applies at 10% only if total dividend from a company exceeds ₹5,000 in a financial year (20% if PAN is not provided).
- Resident individuals can file Form 15G/15H to avoid TDS if their income is below the taxable limit.
- Non-residents are taxed at 20% (plus surcharge/cess), subject to DTAA relief.
Worked Example — retail investor, 1,000 shares, 30% slab
| Gross dividend (1,000 × ₹1.50) | ₹1,500 |
| TDS under Sec 194 | ₹0 (below ₹5,000 threshold) |
| Tax at 30% + 4% cess | ₹468 |
| Net dividend in hand | ₹1,032 |
| Effective post-tax yield (@ ₹243) | ~0.42% |
Because a 1,000-share holding produces only ₹1,500 of dividend — below the ₹5,000 TDS threshold — no tax is withheld at source; the investor still owes slab tax when filing their return. After a 30% slab, the effective yield shrinks to roughly 0.42%.
Key Risks
1. Cyclical earnings. Broking revenue and profit swing with market volumes and sentiment. FY26 profit fell 73%, and quarterly profit nearly vanished in Q2. A weak market can quickly compress earnings — and the dividend with it.
2. Margin compression. Fees & commission expense jumped 157% and finance costs 86% in FY26. If cost pass-throughs and interest stay elevated, margins remain under pressure even if revenue grows.
3. Regulatory & STT/tax risk. SEBI rule changes (F&O curbs, brokerage caps) and Budget measures such as STT hikes directly hit broking economics across the sector.
4. Equity dilution. Ongoing warrant conversions, ESOPs and a proposed ₹100 crore NCD programme grow the share/debt base, diluting per-share metrics and raising interest costs.
5. Low liquidity & promoter concentration. With ~72.8% promoter holding and a thin public float, trading volumes are low and the stock can be volatile; minority influence on policy is limited.
6. Credit rating. NCDs carry an [ICRA]BBB+ / stable-band rating — investment grade but modest. Any downgrade would raise borrowing costs for a company already increasing leverage.
What To Monitor
1. Quarterly margin trend. Watch whether operating margin recovers from the 5.62% FY26 trough back toward its ~18% FY25 level — the clearest signal of an earnings turnaround.
2. Fees & commission expense ratio. The +157% jump is the biggest profit drag; track whether it normalises as a share of revenue.
3. Segment mix. Follow the Advisory & Transactional segment's recovery versus the small Financing & Investment arm that propped up FY26 PBT.
4. Next year's dividend decision. Given the cut, the FY27 recommendation will reveal whether ₹1.50 was a floor or a stepping-stone lower/higher.
5. Debt & NCD utilisation. Track D/E (0.24 and rising), NCD issuance up to ₹100 crore, and finance-cost growth against the new ₹1,000 crore borrowing ceiling.
6. AMC / wealth & IB traction. Growth in asset management, wealth and investment-banking fee pools is the structural offset to volatile retail broking.
Conclusion
Positives
- Dividend still covered ~3.95× by earnings; ~22× by own cash.
- Net worth up 25.6%; D/E low at 0.24.
- Revenue grew 12% — the top line is not the problem.
- Promoters increased their stake at ₹239.50 via warrants.
Negatives & Cautions
- Dividend cut 62.5% (₹4.00 → ₹1.50); profit down 73%.
- Operating margin collapsed 18.07% → 5.62%.
- Yield of ~0.62% is the lowest among broking peers.
- Cyclical, discretionary payer — no dividend floor.
Emkay's FY26 dividend is best understood as a conservative reset, not a warning of financial stress. The company remains well-capitalised and low on debt, and the reduced payout is comfortably affordable. But the headline story is the earnings collapse behind the cut — a 73% profit fall driven by margin compression, not weak revenue. For income investors, the ~0.62% yield offers little. For those interested in a cyclical broking recovery, the dividend is a footnote to the real question: whether margins rebound in FY27. We present the facts; the decision is yours.
Frequently Asked Questions
What dividend has Emkay Global announced for FY26?
What is the dividend yield?
What is the record date for the Emkay dividend?
What is the ex-dividend date?
When will the dividend be paid?
Who is eligible for the dividend?
How is the dividend taxed?
Is the Emkay dividend sustainable?
Why did Emkay cut the dividend from ₹4.00 to ₹1.50?
What is Emkay's dividend history?
Does negative operating cash flow mean the dividend is unaffordable?
How much of the dividend goes to promoters?
What should investors monitor going forward?
Where can I confirm these dividend details?
Disclaimer
This article is published by ShareBazaar Online for informational and educational purposes only and does not constitute investment, financial, legal or tax advice, nor any recommendation to buy, sell or hold any security. ShareBazaar Online is not a SEBI-registered investment adviser or research analyst. Figures are compiled from the company's audited FY26 results, exchange filings and publicly available third-party sources; certain items are labelled "Not Independently Verified," "Not Disclosed by Company," or "Inferred." The dividend is subject to shareholder approval at the AGM. Market prices and yields change continuously and must be re-verified before any decision. Investments in securities are subject to market risks; please read all related documents carefully and consult a SEBI-registered adviser and a qualified tax professional before investing. ShareBazaar Online and its authors accept no liability for any loss arising from the use of this content.