
Dividend Snapshot
Company
Sai Silks (Kalamandir) Limited
NSE: KALAMANDIR | BSE: 543989 | CIN: L52190TG2008PLC059968
Dividend Declared
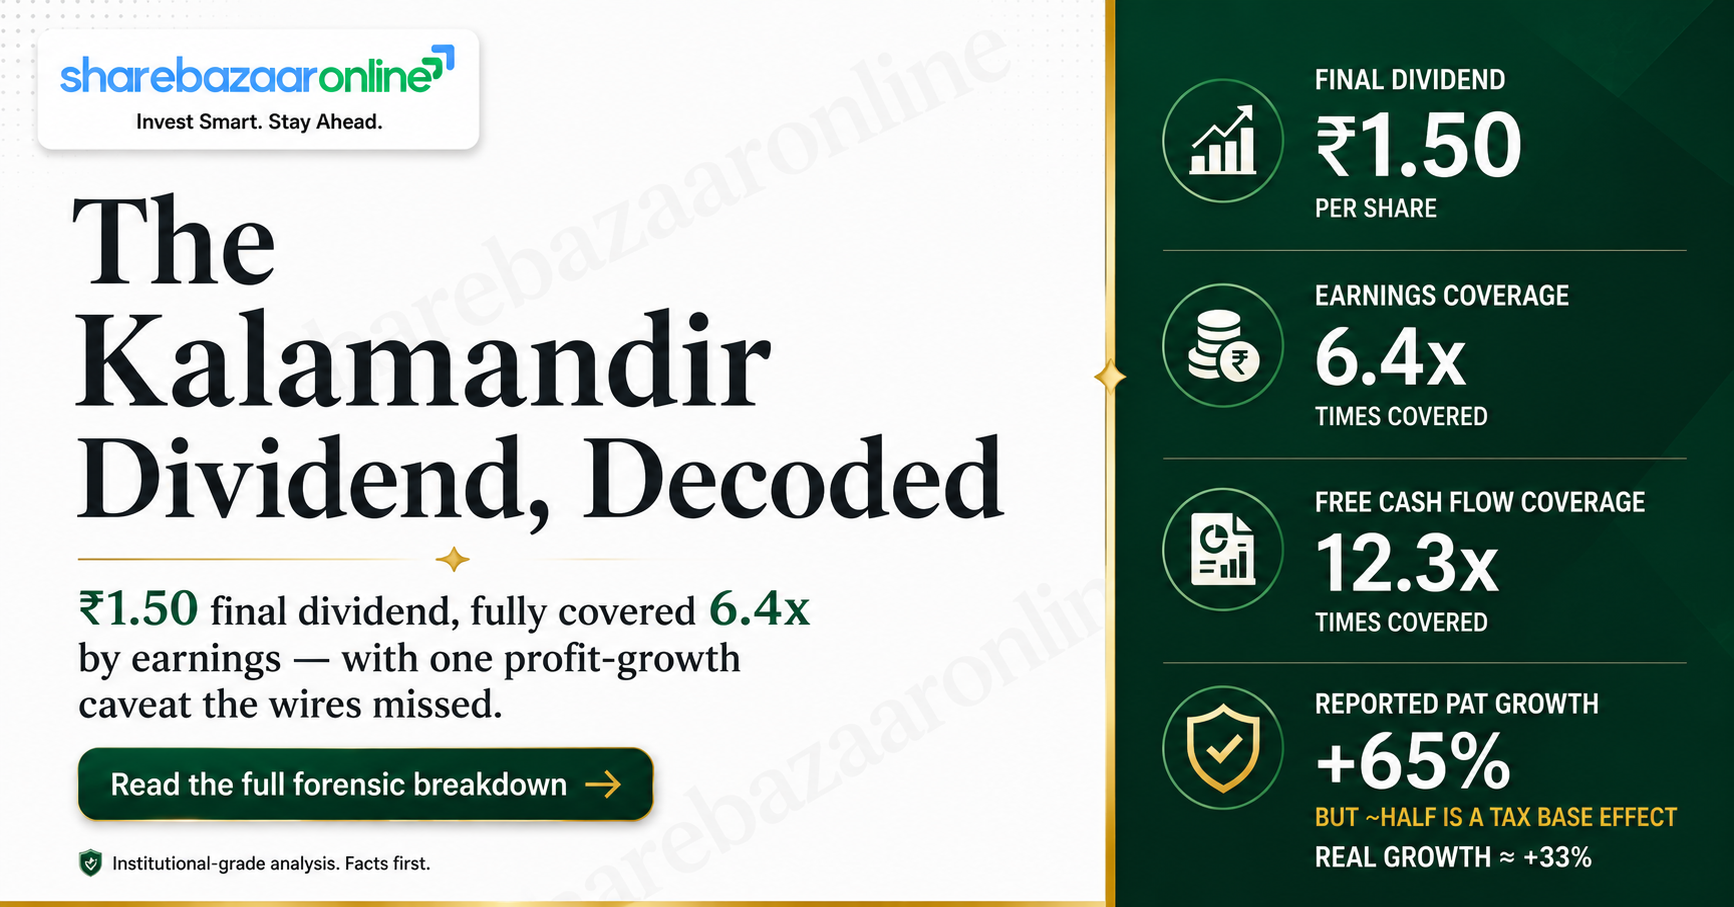
₹1.50 per share (75% of ₹2 face value)
Final Dividend · FY 2025-26 · subject to AGM approval
Dividend Yield
1.69% at CMP ₹88.50
1.28% at the ~₹117 price around the 12 May announcement
Payout & Coverage
15.7% payout · 6.4x earnings coverage
FCF coverage 12.3x · Cash coverage 15.8x
The one-line thesis: Kalamandir is comfortably under-distributing. A ₹1.50 dividend costs the company just ₹22.10 crore against ₹140.92 crore of profit and ₹271.89 crore of free cash flow. The dividend is small but rising (up 50% from ₹1.00 last year), and the higher optical yield owes as much to a ~50% fall in the share price over the past year as to the larger payout.
Dividend Announcement Summary
On 12 May 2026, the Board of Sai Silks (Kalamandir) Limited recommended a final dividend of ₹1.50 per equity share — equal to 75% of the ₹2 face value — for the financial year ended 31 March 2026. The payout is a recommendation, not yet a paid distribution: it becomes payable only after shareholders approve it at the Annual General Meeting.
What the Board approved (same meeting)
- FY2025-26 audited standalone results — unmodified audit opinion
- Final dividend of ₹1.50/share (subject to AGM)
- Appointment of Mr. Bharadwaj Rachamadugu as CEO (w.e.f. 12 May 2026) — son-in-law of the Managing Director & Promoter
- Board and committee reconstitution; one Independent Director resignation noted
Why it matters
The company has no subsidiaries, associates or joint ventures, so its standalone accounts are effectively consolidated — there is no hidden leverage or profit sitting in unconsolidated entities. That makes the dividend easy to assess against a single, clean cash-generating retail business.
Key Dates Timeline
Announcement (Board recommendation)
12 May 2026
Record Date
03 August 2026
Fixed by Board on 15 July 2026; no book-closure period
Ex-Dividend Date
03 August 2026
Under T+1 settlement, ex-date and record date fall on the same day
Payment Date
Not separately disclosed
Payable after the 18th AGM on 10 Aug 2026; statutory outer limit is 30 days from AGM approval (i.e. by ~09 Sep 2026)
Eligibility rule: to receive this dividend you must hold shares in your demat account as of the 03 August 2026 record date, which means buying on or before 01 August 2026 (one trading day before the ex-date under T+1). Buying on or after the ex-date means the seller keeps the dividend.
Dividend Yield Analysis
The yield maths
- Dividend ₹1.50 ÷ CMP ₹88.50 = 1.69%
- Dividend ₹1.50 ÷ ~₹117 (announcement week) = 1.28%
- 52-week range: ₹223.03 high / ~₹86 low
Yield reality check
The yield looks better than it did a year ago for two reasons pulling in the same direction: the dividend genuinely rose (₹1.00 → ₹1.50, up 50%), and the share price roughly halved from its 52-week high. A big chunk of the “improved yield” is therefore a falling-price artifact, not a richer payout.
Context: even at 1.69%, this is a modest yield — a value-apparel retailer in expansion mode is not a yield stock. It sits below fixed-deposit returns and is best read as a shareholder-friendliness signal rather than an income stream. CMP must be re-verified at publish time — the yield moves with the price.
Dividend History Analysis
| Financial Year | Dividend / Share | % of Face Value | Record Date | Payment Date |
|---|---|---|---|---|
| FY2025-26 (current) | ₹1.50 | 75% | 03 Aug 2026 | Post-AGM (n/d) |
| FY2024-25 | ₹1.00 | 50% | 22 Aug 2025 | 28 Sep 2025 |
| FY2023-24 (first post-IPO) | ₹1.00 | 50% | 20 Sep 2024 | 27 Oct 2024 |
Dividend history sourced from exchange/registrar corporate-action records; IPO listed 27 Sep 2023.
Classification: Consistent Payer (Early-Stage)
Kalamandir has paid a dividend in all three years since listing — never skipped, never cut, and now growing. The track record is short (the company IPO'd in September 2023), so it has not yet been tested through a full demand downcycle, but the direction of travel is clearly shareholder-friendly.
The growth signal
The step-up from a flat ₹1.00 (held for two years) to ₹1.50 is the first increase in the company's listed life. It is a small absolute rise but a meaningful 50% jump, signalling growing confidence in recurring cash generation.
Financial Performance Analysis
| Metric (₹ Cr, standalone) | FY2025-26 | FY2024-25 | Growth |
|---|---|---|---|
| Revenue from operations | 1,653.67 | 1,462.01 | +13.1% |
| EBITDA | 279.45 | 235.71 | +18.6% |
| Profit before tax | 189.55 | 142.72 | +32.8% |
| Net profit (PAT) | 140.92 | 85.39 | +65.0% |
| Basic EPS (₹) | 9.56 | 5.80 | +64.8% |
Non-obvious finding: the “profit doubled” headline is a base-effect illusion
Reported PAT jumped 65%, but that overstates the operating improvement. The comparison year (FY25) carried a one-time prior-year tax charge of ₹20.87 crore, which pushed FY25's effective tax rate to an abnormal 40.2%. In FY26 the effective rate normalised to 25.7%. Strip out that base distortion and PAT grew about 33% — closely matching the 32.8% PBT growth. In other words, roughly half of the headline PAT growth is a tax base effect, not fresh operating strength. This is the single most important nuance the wire-service coverage misses.
Operating leverage check
Revenue +13.1%, EBITDA +18.6% — EBITDA grew faster than sales, so there is genuine operating leverage. Employee cost rose to ₹226 Cr (from ₹198 Cr) and finance costs actually fell (₹40.3 Cr → ₹30.9 Cr) as short-term debt was repaid, both helping margins.
The FY27 caution flag
Early FY27 data already points to a slowdown: Q1 FY27 revenue slipped to ~₹375 Cr (from ~₹379 Cr) even as the store count expanded. The FY26 dividend rests on a strong year that may not repeat at the same pace.
Cash Flow Analysis
Reported profit is an opinion; cash is fact. Here the cash story is strong but flattered by working capital.
Operating cash flow vs profit
- OCF FY26: ₹322.53 Cr vs PAT ₹140.92 Cr → 2.29x
- OCF FY25: ₹106.78 Cr vs PAT ₹85.39 Cr → 1.25x
- Capex FY26: ₹50.64 Cr → FCF = ₹271.89 Cr
Non-obvious finding: OCF is working-capital-boosted
OCF at 2.29x of PAT is unusually high for a retailer. The main driver is a ₹137 crore release from trade payables (stretched vendor credit), not pure earnings. A payables swing of this size is not fully repeatable — part of this year's bumper cash generation borrows from timing rather than durable operations.
How is the dividend funded? Even after normalising for the payables swing, the ₹22.10 Cr dividend is dwarfed by ongoing earnings and cash generation. It is funded from current-year operating cash, not from reserves, asset sales or borrowings — the healthiest possible source. Trade receivables are a negligible ₹2.38 Cr (this is a cash-and-carry retail model), so there is no receivables-inflation risk lurking behind the profit number.
Balance Sheet Strength
Liquidity & leverage (31 Mar 2026)
- Cash + bank balances: ₹348.42 Cr
- Total borrowings: ₹20.22 Cr (down from ₹166.5 Cr)
- Net cash (ex-lease): ₹328.20 Cr
- Debt / equity: 0.02 — effectively debt-free
The lease caveat
As a store-based retailer, the real fixed obligation is ₹341 crore of lease liabilities (Ind AS 116) plus ₹816 Cr of inventory. These are operating commitments, not financial debt, but they mean the “net cash” label should not be read as a fortress balance sheet — it is a lean, inventory-heavy retail balance sheet with negligible borrowings.
Note on the cash drop: headline “cash & cash equivalents” fell from ₹85.3 Cr to ₹19.4 Cr, which looks alarming in isolation. It is not — the money moved into “bank balances other than cash equivalents” (₹329 Cr, largely deposits) while the company repaid ~₹142 Cr of short-term borrowings. Total liquidity actually strengthened.
Dividend Sustainability Analysis
| Sustainability Test | Metric | Result | Verdict |
|---|---|---|---|
| Earnings coverage | EPS ₹9.56 ÷ DPS ₹1.50 | 6.37x | Very comfortable |
| Operating-cash coverage | OCF ₹322.5 Cr ÷ ₹22.1 Cr | 14.59x | Very comfortable |
| Free-cash coverage | FCF ₹271.9 Cr ÷ ₹22.1 Cr | 12.30x | Very comfortable |
| Cash / balance-sheet coverage | Cash ₹348.4 Cr ÷ ₹22.1 Cr | 15.76x | Very comfortable |
Overall verdict: Sustainable
The dividend passes all four tests with wide margins. At a 15.7% payout, PAT would have to fall by more than 80% before earnings alone stopped covering ₹1.50 — and even then, ₹348 Cr of cash provides a multi-year buffer. There is no funding stress around this payout.
Watch flags (not red flags)
- This year's FCF is partly a one-off payables release; normalised FCF is lower
- Earnings coverage is flattered by the FY25 tax base effect
- Aggressive store expansion could raise capex and compress future FCF
Peer Comparison
| Company | Div. Yield | Payout | ROE | ROCE | Balance sheet |
|---|---|---|---|---|---|
| Sai Silks (Kalamandir) | 1.69% | 15.7% | ~11.2% | — | Net cash ₹328 Cr |
| Vedant Fashions (Manyavar) | ~1.3% | ~50% | ~26.4% | ~39.6% | Net cash |
| Go Fashion (Go Colors) | 0.0% | Nil | ~8.9% | ~11.5% | Net cash |
Peer figures are latest available (FY26) from public sources; blank cells are left blank where the metric could not be verified from primary sources. Yields move with price — treat as indicative.
Reading the table: Kalamandir sits between two archetypes. Vedant Fashions is the mature, high-return payer that distributes roughly half its profit; Go Fashion is the growth-first retailer that pays nothing. Kalamandir's low 15.7% payout looks more like Go Fashion's philosophy (retain to expand), but it has chosen to pay a token, rising dividend. Its returns (ROE ~11%) trail Vedant's ~26% — a reminder that a rising dividend does not, by itself, make it a superior capital allocator.
Promoter Impact Analysis
Who receives the ₹22.10 Cr
- Promoter group (~60.97%): ₹13.48 Cr
- Public / institutions (~39.03%): ₹8.63 Cr
- FII ~0.6% · DII ~6.3% (latest quarter)
Is this a promoter cash-out?
At a 15.7% payout, no. The promoter family draws ₹13.5 Cr while leaving the vast majority of profit inside the company. Given the promoter also earns salary/remuneration (and the new CEO is the MD's son-in-law), governance-minded readers should track related-party flows, but the dividend itself is proportionate and not extractive.
Minority-shareholder angle: because the payout ratio is low, minority holders benefit more from any future re-rating of retained earnings than from the dividend cheque. The dividend is a signal of intent; the real value lever remains how well management redeploys the ~84% of profit it keeps.
Taxation Analysis
How dividends are taxed in India (post-2020 rules)
Since the abolition of Dividend Distribution Tax, dividends are taxed entirely in the shareholder's hands at their applicable income-tax slab rate. The company deducts TDS under Section 194 at 10% only if a resident shareholder's total dividend from that company in the year exceeds ₹10,000 (higher threshold under recent Finance Act changes; historically ₹5,000). Submitting Form 15G/15H can avoid TDS for those below the taxable limit; non-residents face different rates subject to DTAA.
Worked example — a retail investor holding 1,000 shares
| Gross dividend (1,000 × ₹1.50) | ₹1,500 |
| TDS under Section 194 | ₹0 (gross ₹1,500 is below the TDS threshold) |
| Tax payable @ 30% slab | ₹450 |
| Net dividend in hand (30% slab) | ₹1,050 |
| Post-tax yield @ CMP ₹88.50 (30% slab) | ~1.19% |
Illustrative; excludes surcharge/cess. A 5% or 20% slab investor keeps more. This is general information, not tax advice — consult a qualified advisor for your situation.
Key Risks
- Revenue momentum is fading. Q1 FY27 sales fell year-on-year despite new-store additions, suggesting weak same-store growth. A sustained top-line stall would pressure the profit base the dividend rests on.
- Earnings quality overstated by the tax base effect. The 65% PAT jump is roughly half base-effect; the market may have anchored to an inflated growth number that will not recur.
- Working-capital-dependent cash flow. A ₹137 Cr payables release drove this year's bumper OCF. A reversal (vendors tightening credit) could sharply cut future free cash flow.
- Inventory-heavy, discretionary model. ₹816 Cr of inventory in a wedding/festive-led ethnic-wear business exposes the company to fashion, seasonality and demand-cycle risk; write-downs would hit both profit and cash.
- Sharp share-price derating & governance watch-items. The stock has fallen ~50% from its 52-week high; concentrated promoter control (~61%) plus a family CEO appointment and related-party dynamics warrant ongoing governance monitoring.
What To Monitor
- Same-store sales growth (SSSG) in FY27 quarters — the truest read of demand, stripped of new-store noise.
- Normalised free cash flow once the payables swing washes out — does FCF stay comfortably above the ₹22 Cr dividend?
- Payout-ratio trajectory — whether management lifts the payout toward peer levels or keeps retaining for expansion.
- Capex intensity and store economics — new-store paybacks and the FY27 target of ~1,00,000 sq ft of additions and 17.5-18% EBITDA margin.
- Working-capital and inventory days — rising inventory or lengthening payables would signal cash-flow stress ahead.
Conclusion
The positives
A rising, well-covered dividend (up 50% to ₹1.50), three consecutive years of payments since IPO, an effectively debt-free balance sheet with ₹328 Cr of net cash, and real operating leverage (EBITDA +18.6% on revenue +13.1%). The payout is funded from current cash and is not extractive to minorities.
The negatives & caveats
The headline profit growth is roughly half a tax base effect; this year's cash flow is flattered by a one-off payables release; the yield's improvement is partly a falling-price story; and FY27 revenue is already softening. Returns (ROE ~11%) trail the best-in-class peer. The dividend is a positive signal but a small one — this remains a growth-and-expansion story, not an income story.
Bottom line: the ₹1.50 dividend is safe and sustainable, but investors should size their expectations to the reality — a ~1.7% yield from a discretionary retailer whose reported growth flatters the underlying trend. We present the evidence; the decision is yours.
Frequently Asked Questions
What dividend has Sai Silks (Kalamandir) announced?
What is the dividend yield?
What is the record date?
What is the ex-dividend date?
When will the dividend be paid?
Who is eligible for the dividend?
How is this dividend taxed?
Is the dividend sustainable?
What is Sai Silks' dividend history?
Did the company's profit really grow 65%?
How much of the dividend goes to promoters?
Why has the stock fallen so much?
What should investors monitor from here?
Disclaimer
This article is published by ShareBazaar Online for informational and educational purposes only. It is not investment advice and does not constitute a buy, sell or hold recommendation. ShareBazaar Online is not a SEBI-registered investment adviser or research analyst. All financial figures are drawn from the company's audited FY2025-26 standalone results and exchange filings dated 12 May 2026; market prices, yields, shareholding and peer data are from public sources and were accurate around the time of writing but change continually — the current market price and dividend dates must be independently re-verified before acting. Dividend figures are subject to shareholder approval at the AGM. Ratios are computed by ShareBazaar Online and rounded. Securities markets carry risk; please read all related documents carefully and consult a qualified financial and tax adviser before investing. ShareBazaar Online accepts no liability for decisions taken on the basis of this content.