
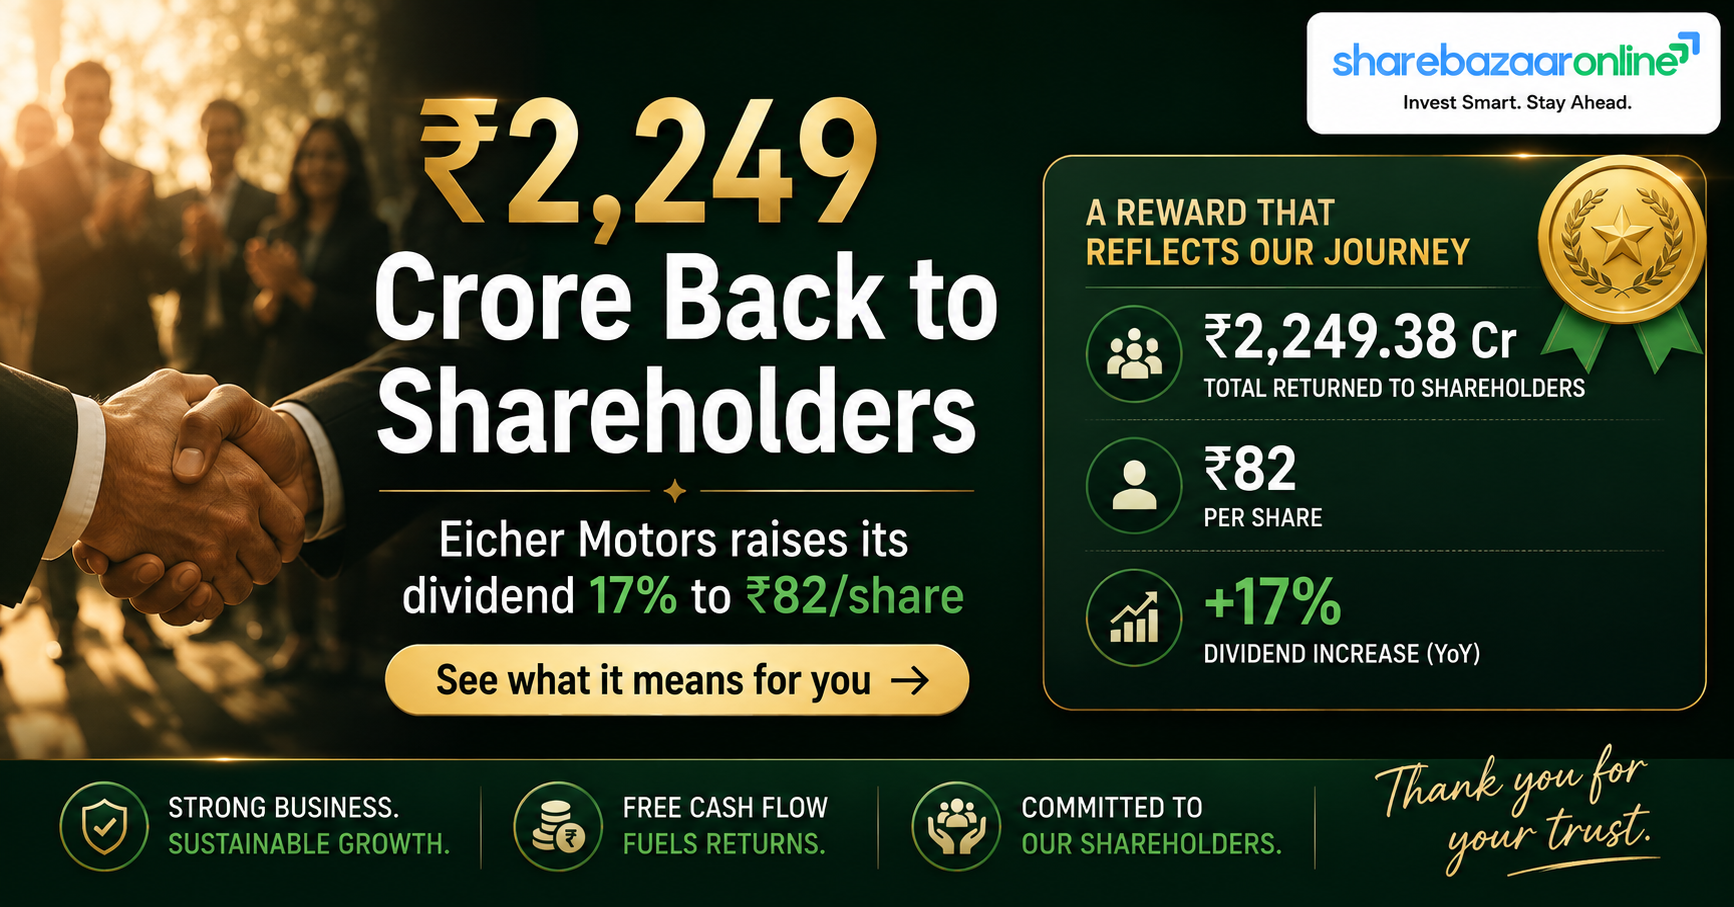
Dividend Snapshot
Dividend Per Share
₹82.00
Final dividend, FY2025-26 (8,200% of ₹1 face value)
Dividend Yield (at latest CMP)
1.05%
₹82 ÷ ₹7,833.50 (NSE, 31-Jul-2026). Re-verify at publish.
Total Dividend Outflow
₹2,249.38 crore
Company-disclosed aggregate on 27.43 crore shares
Dividend Classification
Consistent & Growing Payer
Uninterrupted annual payout; 5-yr DPS CAGR ~37%
One-line takeaway: A record ₹82 dividend (up 17.1% from ₹70) but a modest ~1.05% yield — Eicher remains a growth compounder that pays a rising dividend, not an income stock. The payout is comfortably funded by ₹3,530 crore of free cash flow and backed by a ₹13,688 crore net-cash balance sheet.
Dividend Announcement Summary
At its board meeting on 22-May-2026 (convened 11:00 a.m., concluded 3:40 p.m.), the Board of Directors of Eicher Motors Limited — the maker of Royal Enfield motorcycles and 50% owner of the VE Commercial Vehicles (VECV) joint venture with AB Volvo — recommended a final dividend of ₹82 per equity share of face value ₹1 for the financial year ended 31-March-2026. The recommendation was made under Regulations 30 and 33 of SEBI (LODR) Regulations, 2015, alongside audited standalone and consolidated results carrying an unmodified audit opinion from S.R. Batliboi & Co. LLP.
What the board approved
- Final dividend of ₹82/share (previous year: ₹70)
- Aggregate outflow of ₹2,249.38 crore
- Subject to member approval at the 44th AGM
- Payment within 30 days of AGM approval
Context notes
- No interim dividend was paid in FY26 — this is the sole annual payout
- A ₹55.45 crore one-time provision for the new Labour Codes was booked as an exceptional item
- Face value has been ₹1 since the 10:1 split of Aug-2020
Key Dates Timeline
| Event | Date | Source / Basis |
|---|---|---|
| Board announcement | 22-May-2026 | Company filing (BSE/NSE) |
| Record date | 31-Jul-2026 | Reg. 42 intimation (exchange corporate action) |
| Ex-dividend date | 31-Jul-2026 | Same as record date under current settlement |
| 44th AGM (approval) | 20-Aug-2026 | Via video conferencing, 4:30 p.m. IST |
| Payment (outer limit) | On/before ~19-Sep-2026 | Within 30 days of AGM approval; exact date Not Disclosed by Company |
Eligibility note: Since the record date of 31-July-2026 has passed, only shareholders on the register that day are entitled. Anyone buying on or after the ex-date will not receive this dividend. Actual payment still hinges on the 20-August AGM vote.
Dividend Yield Analysis
Yield at latest CMP
1.05%
₹82 ÷ ₹7,833.50 (31-Jul-2026)
Yield at announcement CMP
1.17%
₹82 ÷ ₹6,981.50 (22-May-2026)
Yield reality check — why the yield is low despite a record dividend
The yield fell from 1.17% at announcement to 1.05% today not because the dividend shrank, but because the share price rose ~12% (from ₹6,981 to ₹7,834) over the same window. A low yield here is a symptom of a re-rating growth stock, not weak generosity. Investors are pricing Eicher on earnings growth and its 50-DMA of ~₹7,396; the dividend is a secondary consideration. Contrast this with Hero MotoCorp, whose ~3.6-4.9% yield reflects a value-style stock trading at a lower multiple.
Dividend History Analysis
All figures split-adjusted to the current ₹1 face value (10:1 split effective 25-Aug-2020). Pre-split years shown on an equivalent basis.
| Financial Year | DPS (₹, adj.) | YoY change |
|---|---|---|
| FY2025-26 | 82.00 | +17.1% |
| FY2024-25 | 70.00 | +37.3% |
| FY2023-24 | 51.00 | +37.8% |
| FY2022-23 | 37.00 | +76.2% |
| FY2021-22 | 21.00 | +23.5% |
| FY2020-21 | 17.00 | +36.0% |
| FY2019-20 | 12.50 | 0.0% |
| FY2018-19 | 12.50 | +13.6% |
| FY2017-18 | 11.00 | +10.0% |
| FY2016-17 | 10.00 | — |
History sourced from exchange records via TipRanks/aggregators — Not Independently Verified against each original circular.
Verdict: Consistent Payer with a strong growth trend
Over the last decade there have been no dividend cuts or suspensions — even through FY20-FY21 (COVID), the payout held at ₹12.50 then rose. The 5-year DPS CAGR is ~37% (₹17 in FY21 to ₹82 in FY26), far outpacing a typical mature auto payer. This is a company steadily lifting distributions as its cash pile grows, not a lumpy or special-dividend-driven story.
Financial Performance Analysis (Consolidated)
| Metric (₹ crore) | FY26 | FY25 | Growth |
|---|---|---|---|
| Revenue from operations | 23,407.56 | 18,870.35 | +24.0% |
| Operating EBITDA (excl. other income) | 5,785.07 | — | margin 24.7% |
| Other income | 1,486.53 | 1,304.90 | +13.9% |
| Share of JV profit (VECV) | 797.81 | 699.81 | +14.0% |
| Exceptional item (Labour Codes) | (55.45) | — | one-time |
| Net profit (owners) | 5,515.23 | 4,734.44 | +16.5% |
| Basic EPS (₹) | 201.09 | 172.76 | +16.4% |
⚠ Non-obvious finding: operating leverage did NOT expand this year
Revenue jumped 24.0% but net profit rose only 16.5% — profit grew markedly slower than sales. The gap is explained by cost of raw materials & components consumed rising to ₹12,502 crore, a sharp jump in purchase of traded goods to ₹835 crore (from ₹507 crore), higher employee costs (+17.7%), and the ₹55.45 crore Labour-Code provision. In other words, the top-line surge was partly volume/consolidation-led and did not drop through to the bottom line at the same rate. Aggregators report only the headline "record profit"; the operating-leverage compression is the more useful signal.
Quality-of-earnings note
Of the ₹5,515 crore consolidated profit, ₹1,487 crore is "other income" and ₹798 crore (14.5%) is the equity-accounted VECV joint-venture share. A material portion of reported profit therefore comes from treasury/investment income and a non-operating JV rather than from selling motorcycles. This is a legitimate, high-quality mix — but it means Royal Enfield's core operating profit is smaller than the headline suggests.
Cash Flow Analysis (Consolidated)
Operating Cash Flow
₹4,804.84 cr
FY25: ₹3,979.92 cr (+20.7%)
Free Cash Flow (OCF − Capex)
₹3,529.58 cr
Capex of ₹1,275.26 cr deducted
Cash conversion & dividend funding
Cash conversion (OCF ÷ PAT) is a healthy 87% — most reported profit turns into real cash, though the sub-100% figure reflects the non-cash JV profit and treasury gains discussed above. Crucially, the ₹2,249 crore dividend is funded 1.57× by this year's free cash flow alone — it does not require dipping into reserves, selling assets, or borrowing. This is the single most important sustainability signal in the whole analysis.
Working-capital watch: Inventories rose ₹404 crore and trade payables/other liabilities absorbed part of that, keeping operating cash healthy. There were no receivable red flags at the consolidated level (trade receivables actually declined). The dividend is being paid out of genuinely earned cash, not accounting profit.
Balance Sheet Strength
Cash + Investments (liquid)
₹14,006.74 cr
₹234 cr cash + ₹2,832 cr current inv + ₹10,940 cr other inv
Net Cash Position
₹13,687.73 cr
Total borrowings only ₹319 cr — effectively debt-free
Total equity ₹25,100 cr | ROE ~22% (year-end) / ~24% (avg equity)
Eicher runs one of the strongest balance sheets in the auto sector: net cash of ₹13,688 crore against a token ₹319 crore of borrowings. The dividend consumes only ~16% of that liquid pile. This fortress balance sheet is exactly why the ₹82 dividend is easily affordable — but it also raises a capital-allocation question addressed later: is holding ₹14,000 crore of treasury the best use of shareholder capital?
Dividend Sustainability Analysis
| Sustainability Test | Metric | Result |
|---|---|---|
| Earnings coverage (EPS ÷ DPS) | 2.45× | Strong |
| OCF coverage (OCF ÷ outflow) | 2.14× | Strong |
| FCF coverage (FCF ÷ outflow) | 1.57× | Comfortable |
| Cash coverage (cash+inv ÷ outflow) | 6.23× | Very Strong |
Overall verdict: SUSTAINABLE
All four independent tests pass with room to spare. Earnings cover the dividend 2.45×, free cash flow covers it 1.57×, and the cash pile covers it more than six times over. The payout ratio (~40.8% consolidated) has stayed remarkably flat even as the dividend rose 17%, showing discipline. Watch flag: because ~14.5% of profit is the non-cash VECV share, headline earnings coverage slightly overstates operating-cash coverage — but even the pure FCF test clears comfortably.
Peer Comparison
| Company | FY26 DPS (₹) | Approx. Yield | Payout | Balance Sheet |
|---|---|---|---|---|
| Eicher Motors | 82.00 | ~1.05% | ~40.8% | Net cash ₹13,688 cr |
| Bajaj Auto | 150.00 (+ buyback) | NIV | ~100% (div+buyback) | Net cash |
| Hero MotoCorp | 185.00 (110 int + 75 fin) | ~3.6% | NIV | Debt-free, net cash |
| TVS Motor | NIV | NIV | NIV | Modest leverage |
NIV = Not Independently Verified from primary sources; peer cells left unfilled where exchange-grade confirmation was unavailable. Yields move with price — re-verify at publish.
Read-across: Among two-wheeler majors, Eicher offers the lowest yield despite a record dividend, because it commands the highest growth multiple. Bajaj Auto returned ~100% of FY26 PAT via a combined dividend-plus-buyback (a centenary-year move), and Hero MotoCorp's higher ~3.6% yield reflects a value-style re-rating. Eicher's differentiator is not yield but a fortress net-cash position and a still-rising dividend curve.
Promoter Impact Analysis
Promoter holding (Mar-2026)
~49.06%
Lal family / Simran Siddhartha Tara Benefit Trust; no pledge
Estimated promoter dividend income
~₹1,103.55 cr
49.06% × ₹2,249.38 cr outflow
The promoter group is estimated to receive roughly ₹1,104 crore of the total payout, with the remaining ~₹1,146 crore flowing to public and institutional shareholders — FII ~26.8% and DII/mutual funds ~10.3% (aggregator figures, Not Independently Verified against the primary filing; classifications differ across sources). Because promoter holding is well below the levels seen in family-controlled firms that use dividends as a cash-extraction tool, and the payout ratio is a modest ~41%, this looks like a balanced distribution rather than a promoter-skewed one. No pledged promoter shares are reported.
Taxation Analysis
Since April 2020, dividends are taxable in the hands of the shareholder at their applicable income-tax slab rate (Dividend Distribution Tax was abolished). Under Section 194, the company deducts TDS at 10% if total dividend paid to a resident in a financial year exceeds ₹5,000 (₹10,000 threshold under some provisions; verify current limit). This TDS is a credit adjustable against final tax. Investors with income below the exemption limit can file Form 15G/15H to avoid TDS. Non-residents are taxed per Section 195 and any applicable DTAA.
Worked example — retail investor holding 1,000 shares
| Gross dividend (1,000 × ₹82) | ₹82,000 |
| TDS @ 10% (Section 194) | ₹8,200 (credit adjustable) |
| Amount received after TDS | ₹73,800 |
| Final tax @ 30% slab + 4% cess | ₹25,584 |
| Net dividend in hand | ₹56,416 |
| Post-tax effective yield (@ ₹7,833.50) | ~0.72% |
Illustrative only; surcharge (for incomes above ₹50 lakh) and individual circumstances not modelled. Not tax advice.
Key Risks
- Operating-leverage compression: FY26 already showed profit (16.5%) lagging revenue (24%). If raw-material costs and traded-goods purchases keep rising, margins could stay pressured.
- Premium-motorcycle demand cyclicality: Royal Enfield sits in a discretionary, cyclical segment; a slowdown in the 350cc+ category or rising competition (Triumph, Harley-Hero, Bajaj-Triumph) can dent volumes.
- Reliance on treasury & JV income: ~₹1,487 cr other income and ₹798 cr non-cash VECV share flatter reported profit; a weak investment year or VECV downturn would hit consolidated earnings.
- Regulatory/cost overhangs: The new Labour Codes (₹55.45 cr provision already booked) and the End-of-Life Vehicle (ELV) EPR rules carry as-yet-unquantified future cost obligations.
- Low yield cushion: At ~1.05%, the dividend offers little downside protection if the growth narrative falters and the ~40× P/E de-rates.
- Export/FX exposure: Royal Enfield's international subsidiaries (US, UK, Thailand, Brazil, Europe) expose earnings to currency and demand swings in overseas markets.
What To Monitor
- Monthly Royal Enfield volumes — especially the new-model mix (Himalayan, Guerrilla, Classic 650) and whether premiumisation sustains realisations.
- Gross-margin trajectory — track cost of raw materials as a % of revenue to see if the FY26 leverage compression reverses.
- VECV (commercial-vehicle JV) performance — its ₹798 cr profit share and cash up-streaming (only ₹218 cr came up as cash in FY26).
- Capital-allocation signals — any move toward a buyback, special dividend, or large capex/acquisition that deploys the ₹14,000 cr treasury.
- Export ramp & EV roadmap — Royal Enfield's overseas growth and its electric (Flying Flea) commercialisation timeline.
- AGM outcome on 20-Aug-2026 — formal shareholder approval that converts the recommended dividend into a payable one.
Conclusion
Positives
- Record ₹82 dividend, up 17.1%, with a ~37% five-year CAGR
- Fully funded by ₹3,530 cr FCF (1.57× cover)
- Fortress ₹13,688 cr net-cash balance sheet
- Disciplined ~40.8% payout, unbroken payment record
Negatives / Watch-points
- Profit (16.5%) grew slower than revenue (24%)
- ~₹2,285 cr of profit is treasury + non-cash JV income
- Very low ~1.05% yield offers little income cushion
- Idle ₹14,000 cr treasury raises capital-efficiency questions
Eicher Motors' FY26 dividend is a textbook growth-stock payout: large in absolute terms, small in yield, and unquestionably sustainable. The real analytical story is not the dividend itself but the operating-leverage compression beneath a "record profit" headline and the enormous, under-deployed treasury. Income seekers will find the yield thin; the payout is best read as a signal of management's cash-generation confidence rather than a reason to own the stock for income. We present the facts; the decision rests with the reader.
Frequently Asked Questions
What dividend has Eicher Motors announced for FY26?
What is the dividend yield?
What is the record date?
What is the ex-dividend date?
When will the dividend be paid?
Who is eligible to receive the dividend?
How is this dividend taxed?
Is the dividend sustainable?
What is Eicher Motors' dividend history?
What should investors monitor going forward?
Why did profit grow slower than revenue this year?
How much of the dividend goes to promoters?
Is Eicher Motors a good income (dividend) stock?
Disclaimer
This article is published by ShareBazaar Online for informational and educational purposes only and does not constitute investment, financial, legal or tax advice, nor any buy/sell/hold recommendation. ShareBazaar Online is not a SEBI-registered investment adviser or research analyst. Company-disclosed figures are drawn from Eicher Motors Limited's exchange filing dated 22-May-2026; market prices, shareholding percentages, peer metrics and dividend-history data are sourced from public aggregators and are marked "Not Independently Verified" where primary confirmation was unavailable. Market prices and yields change continuously and must be re-verified before acting. Dividend payment remains subject to shareholder approval at the 44th AGM. Securities-market investments are subject to market risks; read all related documents carefully. Readers should consult a qualified, registered adviser and make their own independent decisions.