
Dividend Snapshot
Company
Indian Metals & Ferro Alloys Ltd
NSE: IMFA · BSE: 533047 · ISIN: INE919H01018
Dividend
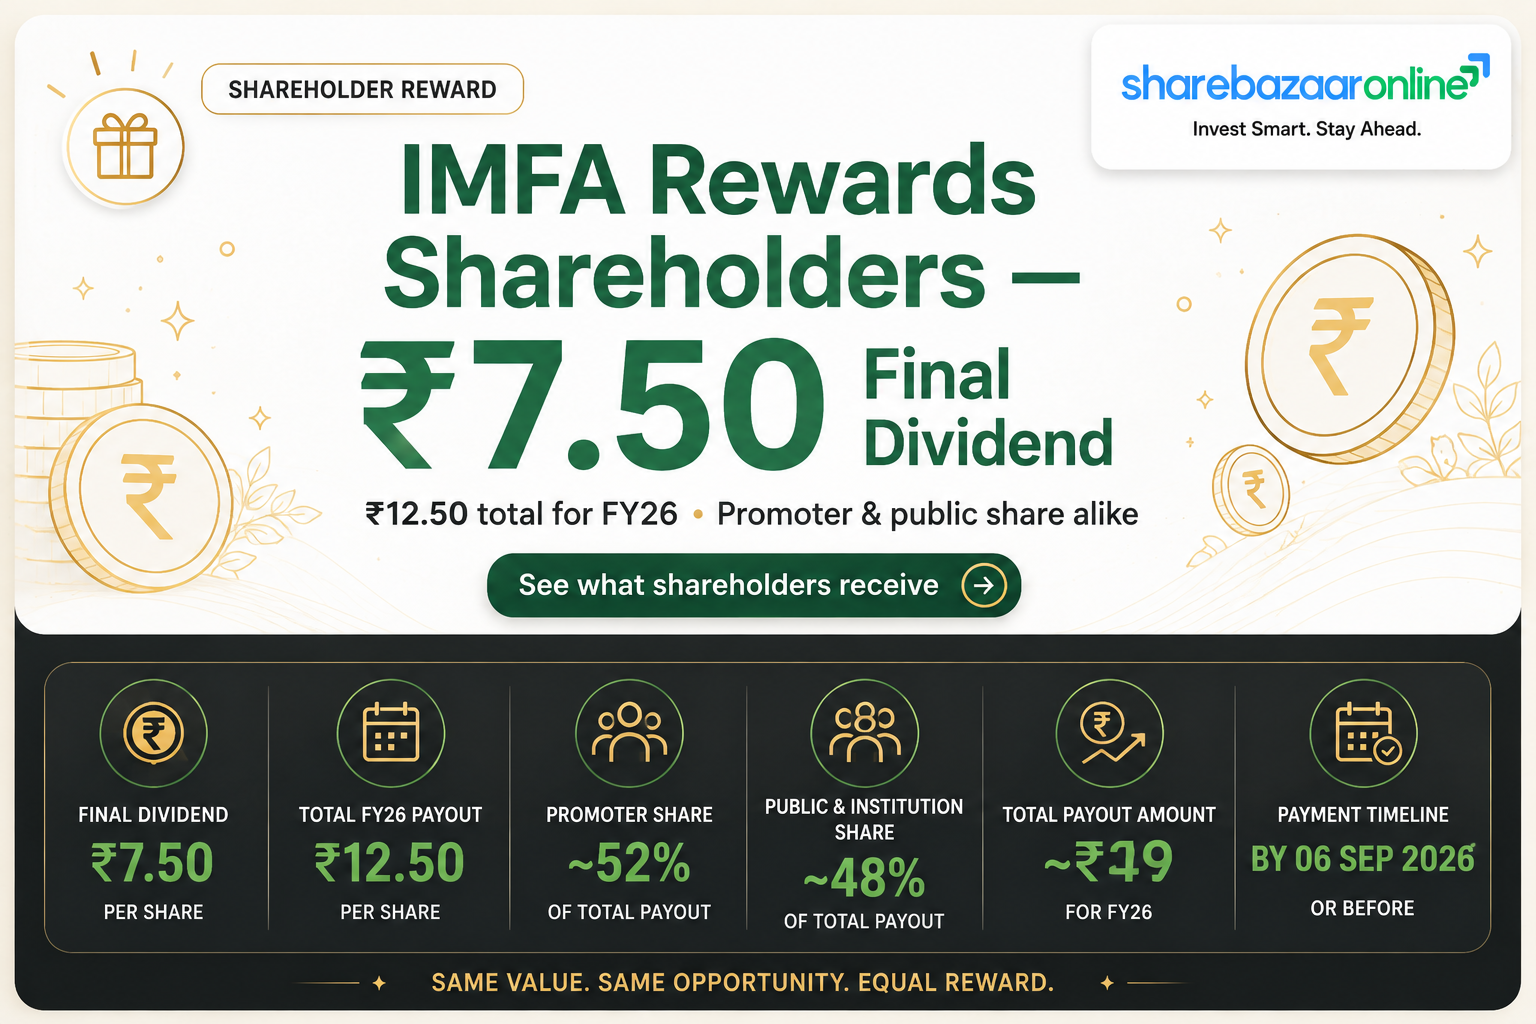
₹7.50 / share (Final, FY26)
75% of ₹10 face value · Full-year FY26: ₹12.50
Final DPS Yield
~0.56%
at CMP ₹1,344
FY26 Total Yield
~0.93%
₹12.50 / CMP
Earnings Cover
10.5x
EPS ₹78.64 / ₹7.50
Payout (Final)
~9.5%
of consol PAT
Payer profile: Consistent dividend payer with a cyclical amount — IMFA has paid every year for over a decade, but the per-year total moves with the ferro-chrome cycle and, this year, with a deliberate step-down to fund growth. FY26 full-year payout of ₹12.50 is lower than FY25's ₹20.00, even though profit rose ~12%.
Dividend Announcement Summary
At its Board meeting held on Wednesday, 27 May 2026, the Board of Directors of IMFA approved the audited standalone and consolidated results for the quarter and year ended 31 March 2026 and recommended a final dividend of ₹7.50 per equity share of ₹10 each, subject to shareholder approval at the forthcoming Annual General Meeting.
What the Board approved
- Final dividend of ₹7.50/share (75%), subject to AGM approval
- Audited FY26 results (standalone & consolidated), unmodified audit opinion
- 64th AGM convened for 4 August 2026
- Record date fixed at 31 July 2026 (Reg. 42 intimation)
Backdrop to the payout
- FY26 revenue at a record ₹2,826.31 cr (up ~10%)
- Consolidated PAT ₹424.72 cr (up ~12%)
- KNR2 acquisition from Tata Steel (₹610 cr) fully operational
- KNR1 greenfield expansion & a 120 kLD ethanol plant under execution
Key Dates Timeline
Announcement Date
27 May 2026
Board recommendation (Reg. 30)
Ex-Date
30 July 2026
Verified via exchange data
Record Date
31 July 2026
Reg. 42 intimation (today)
AGM Date
4 August 2026
64th AGM · dividend approval
Payment Date
Not Disclosed by Company
Statutory outer limit: within 30 days of AGM approval (i.e. on/before ~3 Sep 2026 — inferred, not company-stated)
Books Closure
1–4 Aug 2026
Transfer books closed for AGM & dividend
Note: Payment date is not stated in the company's filing. The date shown is a statutory outer limit inferred from the Companies Act (dividend payable within 30 days of declaration at AGM), not a company-disclosed date. Ex-date is derived from exchange corporate-action data.
Dividend Yield Analysis
At the current market price of about ₹1,344 (28 July 2026), the final dividend of ₹7.50 works out to a yield of only ~0.56%. Counting the full FY26 payout of ₹12.50, the trailing yield is ~0.93%. Both are well below the Basic Materials sector average of roughly 1.7%.
Yield Reality Check — why the yield looks thin
The low yield is not a distress signal. IMFA's share price has risen roughly 90% over the past year (52-week range ₹700–₹1,680), so the same-or-higher rupee dividend divides into a much larger price. On top of that, the company deliberately trimmed the per-year payout from ₹20.00 to ₹12.50 to retain cash for a large capex cycle. A rising price plus a lower payout mechanically compresses the yield.
Yield at different price points
| Reference | Price | Final | FY26 |
|---|---|---|---|
| Latest CMP | ₹1,344 | 0.56% | 0.93% |
| Announce-period | ~₹1,446 | 0.52% | 0.86% |
| 52-week low | ₹700 | 1.07% | 1.79% |
CMP is research-time and must be re-verified against live NSE/BSE quotes before publication. Announcement-period price (~₹1,446, 1 June 2026) is approximate and not the exact 27 May closing.
Dividend History Analysis
Dividend paid by ex-date (per exchange corporate-action records)
| Ex-Date | Type | DPS (₹) |
|---|---|---|
| 30 Jul 2026 | Final (FY26) | 7.50 |
| 11 Nov 2025 | Interim | 5.00 |
| 25 Jul 2025 | Interim/Final | 5.00 |
| 05 Feb 2025 | Interim | 5.00 |
| 14 Nov 2024 | Interim | 10.00 |
| 22 Jul 2024 | Final | 7.50 |
| 08 Apr 2024 | Special/Interim | 15.00 |
| 10 Nov 2023 | Interim | 7.50 |
| 21 Jul 2023 | Final | 5.00 |
| 03 Nov 2022 | Interim | 5.00 |
| 21 Jul 2022 | Final | 7.50 |
Per-financial-year total (company presentation)
- FY26: ₹12.50 (₹5.00 interim + ₹7.50 final)
- FY25: ₹20.00
Aggregator sites tally ~₹25 on an ex-date basis for FY25; the company's own per-FY figures (₹12.50 / ₹20.00) are used here, with the timing difference flagged.
What the pattern shows
A long, unbroken record of paying dividends — no cuts to zero, no suspensions — but the annual amount is cyclical and clearly subordinate to the capex plan. The FY26 step-down to ₹12.50 lines up exactly with the year IMFA funded the ₹610 cr Tata Steel plant acquisition and ramped up the greenfield build. This is a consistent payer with a deliberately variable payout.
Financial Performance Analysis
FY26 vs FY25 (Consolidated, ₹ crore)
| Metric | FY26 | FY25 | YoY |
|---|---|---|---|
| Revenue from operations | 2,826.31 | 2,564.57 | +10.2% |
| EBITDA | 587.23 | 530.51 | +10.7% |
| EBITDA margin | 20.78% | 20.69% | +9 bps |
| PAT (consolidated) | 424.72 | 379.32 | +12.0% |
| Basic EPS (₹) | 78.64 | 70.19 | +12.0% |
Operating Leverage — profit outgrew sales
Revenue rose 10.2%, EBITDA 10.7% and PAT 12.0% — profit growing a touch faster than the top line, a sign of positive operating leverage driven by firm ferro-chrome realisations (~₹1,03,353/tonne in FY26) and cost efficiency. Q4 was especially strong: quarterly EBITDA margin jumped to 20.84% from 12.43% a year earlier.
The cost items to watch
Power & fuel rose 14.2% and other expenses 17.2% (standalone), the latter inflated by a ₹27.97 cr mark-to-market notional forex loss in Q4 as the rupee weakened from ₹89.92 to ₹94.65/USD. The company notes the matching forex gain on export sales sits inside revenue, so the headline "other expense" spike overstates the real cost drag.
Standalone and consolidated are near-identical for IMFA (two small subsidiaries + one associate). Consolidated PAT ₹424.72 cr vs standalone ₹424.36 cr. This analysis uses consolidated figures unless stated.
Cash Flow Analysis
The single most important finding in this report
Reported profit was ₹424.72 cr, but free cash flow in FY26 was deeply negative at roughly −₹1,017 cr. Operating cash flow was healthy at ₹318 cr, but capital expenditure (including the ₹610 cr Tata Steel plant acquisition and the KNR1 greenfield build) was a massive ₹1,335 cr. This means the FY26 final dividend is not being funded out of current-year free cash flow — it is funded from earnings and the balance-sheet cash pile, while the company simultaneously borrowed to finance growth.
Operating Cash Flow
₹318 cr
Capex FY26
₹1,335 cr
Free Cash Flow
−₹1,017 cr
Cash Conversion
~75%
OCF / PAT
Cash conversion quality
OCF of ₹318 cr against PAT of ₹425 cr is a cash conversion of ~75% — decent but not stellar, dragged by a ~₹230 cr build-up in receivables and higher inventory as the acquired KNR2 capacity ramped. Profits are backed by real cash, but working capital absorbed a meaningful chunk of it this year.
How the dividend is really funded
With FCF negative, the ₹40.5 cr final outflow is covered by current earnings and cash reserves, not by surplus cash generation. The heavy investing outflow was part-financed by new borrowing (total debt rose from ~₹373 cr to ~₹924 cr). So this is a growth-phase dividend paid alongside a debt-funded expansion — sustainable given the earnings base, but not a "cash overflowing" story.
Balance Sheet Strength
Total Equity
₹2,726 cr
Total Borrowings
₹924 cr
vs ₹373 cr FY25
Net Debt
~₹520 cr
was net-cash before
Debt / Equity
~0.34
The balance sheet remains comfortable — D/E of ~0.34 is modest and the company carries an AA credit rating (ICRA). The important shift is directional: IMFA moved from a net-cash to a net-debt position (~₹520 cr) during FY26 as it funded the acquisition and greenfield project. Cash and current investments stand at ~₹404 cr against total borrowings of ~₹924 cr. This is a well-capitalised company leaning into a growth cycle, not an over-leveraged one — but the debt trajectory is now something to watch rather than ignore.
Dividend Sustainability Analysis
Verdict: Sustainable
Low payout · high earnings & cash coverMulti-metric test
- Earnings cover (final): 10.5x — very strong
- Earnings cover (full FY26): 6.3x — strong
- Cash + investments cover (final): ~10x
- Payout ratio (full FY26): ~15.9% — conservative
- FCF cover: negative this year (heavy capex)
The honest nuance
On earnings and cash cover, the dividend is comfortably sustainable — the payout is only about a sixth of profit. The one caveat is that FY26 free cash flow was negative because of the expansion, and net debt has appeared. The dividend is safe because it is small relative to profit, not because the company is throwing off surplus cash right now. If the capex cycle over-runs or ferro-chrome prices soften, the per-year amount could stay muted — as it already has (₹12.50 vs ₹20.00).
Peer Comparison
| Company | P/E | P/B | Div Yield | ROE (approx) | Net Cash/Debt |
|---|---|---|---|---|---|
| IMFA | ~17.1 | ~2.7 | ~0.93% | ~16.7% | Net debt ~₹520 cr |
| Maithan Alloys | |||||
| Sandur Manganese & Iron Ores | |||||
| Godawari Power & Ispat | |||||
| Sector average (Basic Materials) | ~1.7% |
Peer cells left blank where a verified figure from a primary/reliable source was not available at research time (per ShareBazaar policy of not populating unverified data). IMFA's own figures are web-verified and require a live CMP re-check pre-publish. Editor to fill peer columns from Screener/Trendlyne before publishing.
Read-through: IMFA's dividend yield (~0.93%) sits below the ~1.7% sector average, reflecting its strong 1-year price run and a growth-first payout policy rather than a weaker business. Its ROE (~16–17%) and AA rating are healthy for the ferro-alloys space, where it is India's largest fully-integrated producer.
Promoter Impact Analysis
Promoter Holding
58.69%
FII Holding
~3.9%
DII Holding
~0.8%
Public
~36.6%
Who gets the ₹40.5 cr final payout
- Promoter group (58.69%): ~₹23.7 cr
- Public / institutions (~41.3%): ~₹16.7 cr
- Promoter share of full FY26 payout: ~₹39.6 cr
Alignment read
With the promoter family (Panda group) holding a majority stake, the bulk of the dividend flows to insiders — but the more telling signal is that the promoters chose to reduce the per-year payout to fund growth rather than maximise their own near-term dividend income. That is generally read as alignment with long-term value creation over cash extraction.
Taxation Analysis
Since April 2020, dividends in India are taxed in the hands of the investor. The dividend is added to your total income and taxed at your applicable income-tax slab rate. The company deducts TDS at 10% (Section 194) if your total dividend from that company in a financial year exceeds ₹5,000 (TDS is 20% without a valid PAN). You can claim the TDS as credit when filing your return.
Worked example — 1,000 shares, final dividend ₹7.50, 30% slab
| Gross dividend (1,000 × ₹7.50) | ₹7,500 |
| TDS @10% (dividend > ₹5,000) | ₹750 |
| Tax at 30% slab | ₹2,250 |
| Net dividend in hand (after full tax) | ₹5,250 |
| Effective post-tax yield (at CMP ₹1,344) | ~0.39% |
TDS is an advance deduction, not an extra tax — it is adjusted against the ₹2,250 slab liability. A ₹5,000 refund of TDS would apply only if slab tax is lower. Surcharge/cess and slab specifics vary by investor.
Key Risks
1. Ferro-chrome price cyclicality
Realisations (~₹1,03,353/tonne FY26) track the global stainless-steel cycle. A downturn would hit margins and could keep the per-year dividend muted.
2. Execution & integration risk
The KNR1 greenfield (commissioning from July 2026) and integration of the acquired KNR2 plant must ramp on schedule; delays would strain the ₹1,335 cr capex payback.
3. Rising debt & negative FCF
Borrowings jumped from ~₹373 cr to ~₹924 cr and FY26 FCF was −₹1,017 cr. Prolonged negative FCF plus rising rates would pressure the balance sheet.
4. Forex / export concentration
~80% of sales are exports (Far East). Rupee moves cause MTM swings (₹27.97 cr notional loss in Q4) and tariff/geopolitical shifts can disrupt demand.
5. Regulatory / mining overhang
Pending Supreme Court matters on state levies on mineral-bearing land, the Utkal coal compensation dispute, and evolving labour codes create contingent liabilities.
6. Working-capital drag
Receivables rose ~₹230 cr in FY26. If collections lag as new capacity sells, cash conversion could weaken further.
What To Monitor
1. KNR1 commissioning cadence — Furnace 1 (July 2026) and Furnace 2 (Sept 2026) timelines and capacity utilisation toward the 5 lakh tpa target.
2. Free cash flow turn — whether FCF returns to positive in FY27 once the capex peak passes; the key test for future dividend headroom.
3. Net debt trajectory — direction of the ~₹924 cr borrowings and ~₹520 cr net debt as the ethanol and greenfield projects draw down funds.
4. Ferro-chrome realisation — the per-tonne price trend, which drives margins and the size of future payouts.
5. Renewable-energy mix — progress toward ~40% renewable sourcing (135 MW contracted + 65 MW hybrid), a lever on the power cost line.
6. Chrome-ore raising — scaling toward the 1.2 mn tpa mining target that underpins backward integration and cost advantage.
Conclusion
IMFA's FY26 final dividend of ₹7.50 is a small, comfortably-covered payout from a company in the middle of its biggest-ever growth push. Earnings and cash cover are strong (10.5x and ~10x on the final dividend), and the payout ratio is a conservative ~16% for the full year. The low headline yield (~0.93%) reflects a share price that nearly doubled in a year and a deliberate decision to cut the per-year payout from ₹20.00 to ₹12.50 — not any weakness in the business.
The nuance a wire-service report would miss: FY26 free cash flow was deeply negative (−₹1,017 cr) and the company shifted from net-cash to ~₹520 cr net debt while funding the ₹610 cr Tata Steel acquisition and the greenfield expansion. The dividend is safe because it is small relative to profit, not because surplus cash is overflowing right now. The story to follow is execution: if the new capacity ramps and free cash flow turns positive in FY27, both the growth and the dividend have room to build.
Frequently Asked Questions
What dividend has IMFA announced for FY2026?
What is the dividend yield on IMFA shares?
What is the record date for the IMFA dividend?
What is the ex-date and can I still buy to qualify?
When will the IMFA dividend be paid?
Who is eligible for the dividend?
How is the IMFA dividend taxed?
Is the IMFA dividend sustainable?
Why did IMFA reduce its full-year dividend versus last year?
What is IMFA's dividend history?
How much dividend income goes to the promoters?
What should investors monitor going forward?
How did IMFA perform financially in FY26?
Is IMFA a good dividend stock?
Disclaimer
This article is for informational and educational purposes only and does not constitute investment advice or a recommendation to buy, sell or hold any security. ShareBazaar Online is not a registered investment adviser. Figures are drawn from IMFA's audited FY26 exchange filings and publicly available market data; market price, yield and some peer figures are as of the research date and must be independently verified against live NSE/BSE data before acting. Dividend approval, record date and payment are subject to AGM outcomes and statutory timelines. Tax treatment depends on individual circumstances — consult a qualified professional. Investments in securities are subject to market risk; please do your own research or consult a SEBI-registered adviser before investing.