
Dividend Snapshot
Key finding: The dividend is held flat at ₹1.50 versus last year. The payout ratio only looks higher (rising to ~15% from ~13%) because earnings per share fell 15% — not because the company turned more generous. Revenue grew but profit declined, a divergence explained in the analysis below.
Dividend Announcement Summary
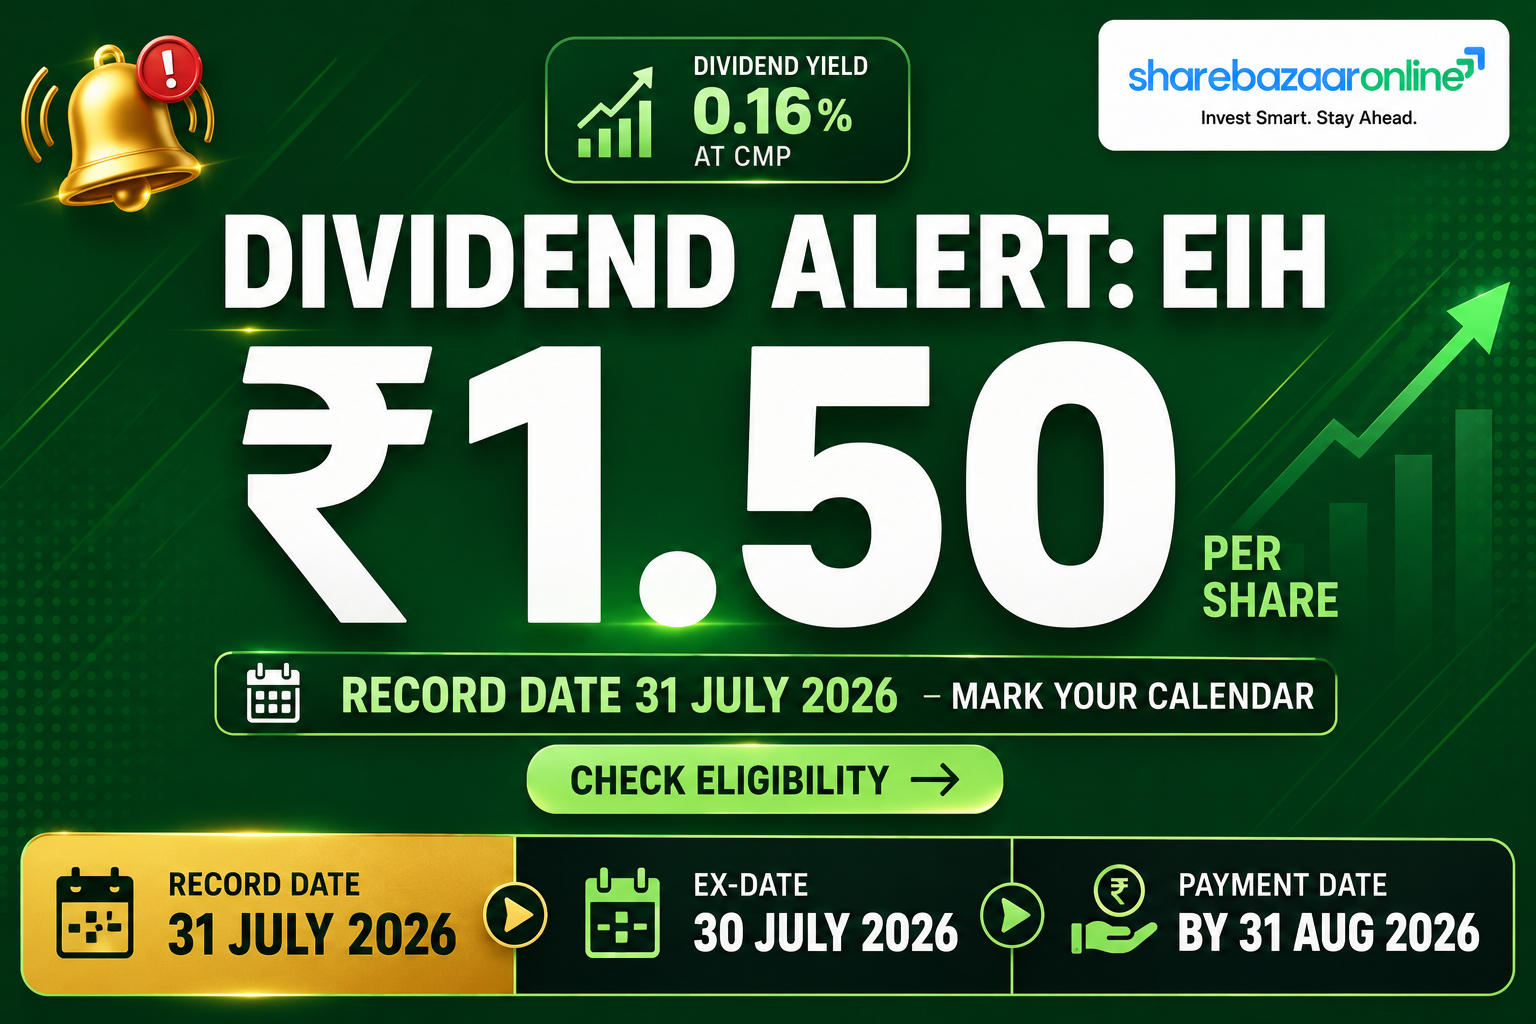
On 26 May 2026, the Board of Directors of EIH Limited — the flagship listed company of The Oberoi Group — recommended a final dividend of ₹1.50 per equity share (75% of the ₹2 face value) for the financial year 2025–26.
The dividend is a recommendation, not yet an entitlement. It becomes payable only if approved by shareholders at the Company’s 76th Annual General Meeting on 7 August 2026. One nuance worth flagging: the record date (31 July 2026) falls before the AGM (7 August 2026) — so the shareholder list is frozen first, and formal approval follows.
Payment is stated to be made on or before Monday, 31 August 2026, subject to deduction of tax at source (TDS). The filing was made under Regulation 42 of SEBI (LODR) Regulations, 2015.
Key Dates Timeline
Note on Ex-Date: The company disclosed only the record date (31 July 2026). The ex-date of 30 July 2026 is inferred using standard T+1 settlement logic (record date minus one trading day) and is corroborated by third-party data providers. It is not an exchange-confirmed figure in the filing. To be eligible, shares must be held before the ex-date.
Dividend Yield Analysis
Yield reality check: A ~0.45% yield is low in absolute terms — typical for a capital-intensive luxury hospitality business that reinvests rather than distributes. This is a total-return / growth stock, not an income stock.
The yield is low for the “good” reason (a premium share price and heavy reinvestment), not the “bad” reason (a collapsing dividend). The dividend itself is modest by design.
Dividend History Analysis
| Financial Year | DPS (₹) | Payout % | Remark |
|---|---|---|---|
| FY2025–26 | 1.50 | ~15% | Flat vs last year |
| FY2024–25 | 1.50 | ~13% | Peak DPS |
| FY2023–24 | 1.20 | ~12% | Recovery |
| FY2022–23 | 1.10 | ~22% | Dividend resumed |
| FY2019–20 to FY2021–22 | NIL | 0% | Suspended (COVID losses) |
| FY2018–19 | 0.88 | ~39% | Pre-COVID |
| FY2016–17 / 17–18 | 0.88 | ~29–50% | Pre-COVID |
Classification: Cyclical / Recovering Payer — NOT a consistent payer. EIH suspended its dividend entirely for three years (FY20–FY22) when COVID pushed the business into losses. It resumed in FY23 at ₹1.10 and grew to ₹1.50 by FY25. The 3-year DPS growth (FY23–FY26) is ~10.9% CAGR, but the latest year is flat (0% YoY). Investors seeking uninterrupted dividends should note the payout is tied to the hospitality cycle.
Financial Performance Analysis (Consolidated)
| Metric (₹ Cr) | FY24–25 | FY25–26 | Change |
|---|---|---|---|
| Revenue | 2,743 | 2,940 | +7.2% |
| Operating Profit | 1,028 | 1,024 | −0.4% |
| OPM % | 37.5% | 34.8% | −2.6 pp |
| Other Income | 156 | 91 | −₹65 Cr |
| Effective Tax Rate | ~25% | ~31% | +6 pp |
| Net Profit | 770 | 657 | −14.7% |
| EPS (₹) | 11.82 | 10.05 | −15.0% |
The headline divergence wire services miss: Revenue rose +7.2% but net profit fell −14.7%. Here is exactly why:
- Operating leverage worked against EIH. Costs grew faster than revenue — expenses rose ~11.7% while sales rose 7.2% — so operating profit was flat and OPM compressed 2.6 percentage points (37.5% → 34.8%).
- Other (non-operating) income fell ₹65 Cr (₹156 Cr → ₹91 Cr), directly hitting pre-tax profit.
- The effective tax rate jumped ~6 points (~25% → ~31%), amplifying the fall at the net level.
In short, the profit decline was driven mostly by below-the-operating-line items (lower other income and higher tax), not by a collapse in the core hotel business, whose revenue kept growing.
Cash Flow Analysis
Cash tells a more reassuring story than profit. Reported profit is an opinion; cash is fact. Even as net profit fell 15%, operating cash flow actually rose 20% to ₹993 Cr, and cash conversion hit an excellent 121% (CFO exceeds operating profit). This confirms the profit dip was driven by non-cash and below-operating-line items, not by cash leaking out of the business.
Free cash flow was lower (₹302 Cr vs ₹346 Cr) only because investing outflow more than doubled to ₹1,057 Cr — the company is in an expansion phase (new Oberoi and Trident properties, cruises, renovations). Crucially, the tiny ₹93.8 Cr dividend is funded comfortably out of current operating cash flow, not from borrowings or asset sales. FCF still covers the dividend 3.2x over.
Balance Sheet Strength
EIH runs an almost debt-free balance sheet with borrowings of just ₹252 Cr against reserves of ₹5,137 Cr. Its cash conversion cycle is strongly negative (~−295 days) — guests and travel partners effectively pre-fund operations while suppliers are paid later, a structurally favourable working-capital position. This financial strength means the small dividend poses no strain on the balance sheet.
Not Independently Verified: the exact standalone cash & bank balance is not broken out on the summary screen used here; the ₹656 Cr shown is the balance-sheet “Investments” line. Confirm precise cash + liquid investments against the FY26 annual report before publication.
Dividend Sustainability Analysis
On every coverage test the ₹1.50 dividend is comfortably safe: earnings cover it 6.7x, operating cash flow 10.6x and free cash flow 3.2x, all against an almost debt-free balance sheet. The payout ratio of ~14–15% leaves ample headroom.
The one caveat is cyclicality, not affordability. EIH cut its dividend to zero during the COVID downturn. The current dividend is safe in normal conditions, but hospitality earnings are demand-sensitive, so the payout’s durability is tied to the travel cycle rather than to any financial weakness today.
Peer Comparison
| Company | Div Yield | Payout | ROE | ROCE | Debt |
|---|---|---|---|---|---|
| EIH Ltd | ~0.45% | ~15% | ~15% | ~21% | Almost nil |
| Indian Hotels | ~0.3% | Low | — | — | Low |
| Chalet Hotels | Negligible | Low | ~16.4% | — | High (D/E ~1.5) |
| Lemon Tree | Negligible | Low | ~15.4% | ~12.8% | Moderate (D/E ~0.26) |
| EIH Assoc. Hotels* | ~1.08% | ~24% | — | — | Low |
*Group company (Oberoi Group subsidiary), shown for reference, not a true competitor. Peer figures are indicative and require verification against latest filings.
Take-away: Indian hospitality is a growth-and-capex sector, not a dividend sector. Most listed hotel peers pay little or nothing. EIH stands out on capital efficiency (ROCE ~21%) and a debt-free balance sheet — superior to leveraged peers like Chalet — while its yield remains modest. Investors comparing on yield alone will find slim pickings across the entire sector.
Promoter Impact Analysis
The Oberoi promoter group holds 32.85% and will receive an estimated ₹30.8 Cr of the total ~₹93.8 Cr payout. Notably, the public / retail float (46.65%) receives the largest single slice (~₹43.8 Cr), so this is a broadly distributed dividend rather than one skewed toward insiders. Promoter holding has been stable at 32.85% since FY23 (it stepped down from ~35.7% earlier), signalling no recent promoter selling pressure around the dividend.
Taxation Analysis
Since April 2020, dividends in India are taxed in the hands of the investor at their applicable income-tax slab rate (added to “Income from Other Sources”). The company no longer pays Dividend Distribution Tax.
TDS rule: The company deducts TDS at 10% if total dividend paid to a resident shareholder in a financial year exceeds ₹5,000 (20% if PAN is not furnished). Below ₹5,000, no TDS is deducted.
Worked Example — Investor with 1,000 shares (30% tax slab)
| Shares held | 1,000 |
| Dividend per share | ₹1.50 |
| Gross dividend | ₹1,500 |
| TDS @10% (only if > ₹5,000) | ₹0 (below threshold) |
| Tax payable @30% slab | ₹450 |
| Net dividend in hand | ₹1,050 |
| Effective post-tax yield | ~0.32% |
Note: cess and surcharge (if applicable) are excluded for simplicity. This is a general illustration, not tax advice; actual liability depends on the investor’s total income.
Key Risks
- Cyclical demand: Luxury hospitality is highly sensitive to economic cycles, business travel, tourism and events. A downturn can hit occupancy and room rates quickly — and, as FY20–22 showed, the dividend can be cut to zero.
- Margin pressure: FY26 already saw OPM compress 2.6 points as costs grew faster than revenue. Wage inflation, energy costs and pre-opening expenses for new properties can keep margins under pressure.
- Earnings quality / one-offs: Reported profit fell partly on lower other income and a higher effective tax rate — items that can swing year to year and make headline EPS volatile.
- Heavy capex cycle: Investing outflow doubled to ~₹1,057 Cr. Aggressive expansion (new Oberoi/Trident keys, cruises) could pressure near-term free cash flow if new properties ramp up slower than planned.
- Low absolute yield: At ~0.45%, this is not an income stock. Dividend-focused investors get minimal cash return and rely almost entirely on capital appreciation.
- Valuation risk: A P/E around 29–31 leaves little room for earnings disappointment; the stock is down ~12–15% over the past year.
What To Monitor
- ARR, occupancy and RevPAR trends — the core operating drivers; watch whether pricing power holds as new supply enters the luxury segment.
- Operating margin (OPM) direction — whether the FY26 2.6-point compression reverses or continues in FY27 quarterly results.
- Free cash flow after capex — as the expansion cycle plays out, watch whether FCF recovers once new properties stabilise.
- Effective tax rate normalisation — whether the ~31% FY26 rate was one-off or a new base, since it materially affects reported EPS and the payout ratio optics.
- Dividend trajectory — whether EIH grows DPS beyond the flat ₹1.50, signalling confidence, or holds it while funding expansion.
- New-property ramp-up and pipeline execution — delivery of announced Oberoi/Trident keys, cruises and management contracts.
Conclusion
EIH Limited’s FY2025–26 final dividend of ₹1.50 per share (75%) is flat year-on-year and, at a yield of roughly 0.45%, is modest by design. This is a growth-oriented luxury hospitality business that reinvests aggressively rather than distributing cash.
Positives: the dividend is deeply covered (6.7x on earnings, 10.6x on operating cash flow), the balance sheet is almost debt-free, operating cash flow actually grew 20% to ₹993 Cr, and cash conversion is an excellent 121%.
Negatives / watch-outs: reported net profit fell 15% on margin compression, lower other income and a higher tax rate; the yield is very low; and the dividend has a history of being suspended in downturns (FY20–22).
Our classification: Cyclical/Recovering payer with a Sustainable current dividend. We present the positives, negatives and risks — the decision is yours.
Frequently Asked Questions
What dividend has EIH Limited announced for FY2025–26?
What is the EIH dividend yield?
What is the record date for the EIH dividend?
What is the ex-date?
When will the EIH dividend be paid?
Who is eligible to receive the dividend?
How is this dividend taxed?
Is the EIH dividend sustainable?
Why did EIH’s profit fall even though revenue grew?
What is EIH’s dividend history?
Why has the payout ratio risen if the dividend is flat?
How does EIH’s dividend compare to hotel-sector peers?
How much dividend does the promoter group receive?
Does EIH need AGM approval for this dividend?
What should investors monitor going forward?
Disclaimer
This article is for informational and educational purposes only and does not constitute investment, financial, legal or tax advice, nor a buy/sell/hold recommendation. Dividend event facts (type, per-share amount, record date, AGM date, payment date) are sourced from EIH Limited’s exchange filing dated 26 May 2026. Financial figures, market price, ratios, shareholding and peer data are compiled from third-party sources (including Screener.in and public market data) and may contain errors or be out of date. The ex-date of 30 July 2026 is inferred from settlement logic and is not an exchange-confirmed figure. Current market price and all derived yields must be verified against live NSE/BSE data before acting. Securities markets are subject to risk; please consult a SEBI-registered advisor and read all offer documents before investing. ShareBazaar Online and its authors accept no liability for any loss arising from use of this content.