
Dividend Snapshot
Current market price (₹205, Screener 27-Jul-2026) is research-time data and must be re-verified against live NSE/BSE quotes before publishing.
Dividend Announcement Summary
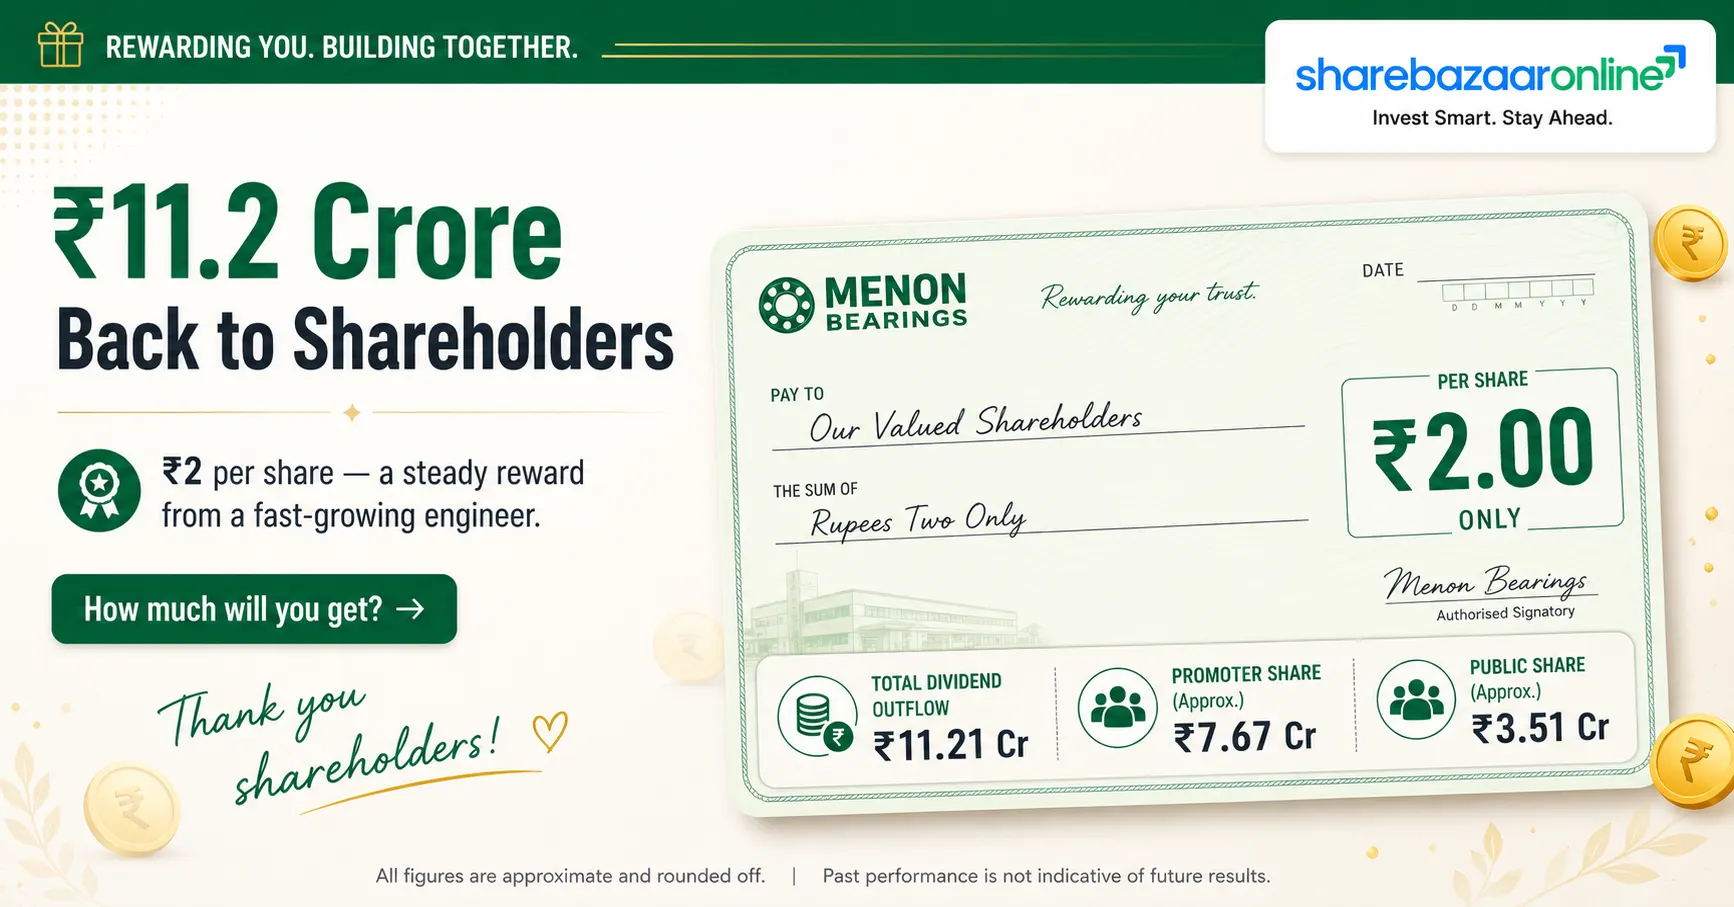
At its board meeting held on Thursday, 16 July 2026 (11:00 AM to 12:35 PM), the Board of Directors of Menon Bearings Limited approved the un-audited standalone and consolidated results for the quarter ended 30 June 2026 and declared an interim dividend of ₹2.00 per equity share — equal to 200% of the ₹1 face value — for the financial year 2026-27.
What was disclosed
- Interim dividend: ₹2.00/share under Regulation 30
- Record date: 22 July 2026 under Regulation 42
- Total sum absorbed: ₹1,120.80 lakh (₹11.21 Cr)
- Credit window: 27 July – 4 August 2026
Key nuance retail readers miss
Because this is an interim dividend declared by the board, it does not require a separate shareholder vote at the AGM before payment — unlike a final dividend. The board is empowered to pay it directly. A final dividend for FY27 (if any) would come later and be subject to AGM approval.
Key Dates Timeline
Ex-date is inferred from India's T+1 settlement cycle (ex-date aligns with record date) and was not separately disclosed by the company. The company disclosed only the record date (22-Jul-2026). The payment window is the company-disclosed credit/dispatch range, not a single statutory date.
Dividend Yield Analysis
At a market price of about ₹205, the ₹2 dividend gives a yield of roughly 0.98%. This is a low headline yield — typical for a growth-oriented small-cap rather than a classic high-yield income stock. The takeaway: investors are not buying MENONBE primarily for dividend income; the payout is a modest top-up to a stock whose story is earnings growth.
Yield at different prices
Yield reality check
The yield looks low because the price has run up hard — the stock is up roughly ~63% over the past year and hit a 52-week high near ₹221. A rising share price mechanically compresses the yield even though the rupee dividend held at ₹2. So the low yield reflects price strength, not a weak dividend.
CMP, 52-week range and 1-year return sourced from Screener/Tickertape (Jun–Jul 2026); verify against live quotes at publish time.
Dividend History Analysis
| Financial Year | Dividend/Share | Type | Record / Ex-Date |
|---|---|---|---|
| FY2026-27 | ₹2.00 | Interim | 22-Jul-2026 |
| FY2025-26 | ₹2.00 | Interim/Annual | 31-Jul-2025 |
| FY2024-25 | ₹2.00 | Interim/Annual | 26-Jul-2024 |
| FY2023-24 | ₹2.25 | Interim | 24-Jul-2023 |
| FY2022-23 | ₹2.00 | Interim | 27-Jul-2022 |
| FY2021-22 | ₹2.00 | Interim | 27-Oct-2021 |
| FY2020-21 | ₹1.50 | Interim | 03-Feb-2021 |
| FY2019-20 | ₹1.25 | Interim | 20-Mar-2020 |
| FY2018-19 | ₹1.25 | Interim | 26-Jul-2019 |
Pattern classification: Consistent, but flat lately
Menon has paid a dividend every year for over a decade, so it qualifies as a Consistent Payer. But the rupee amount has been stuck at ₹2.00 for four straight years (FY23-24's ₹2.25 was the recent high). Dividends have not grown in step with the sharp jump in profits — a sign the board is prioritising reinvestment over rising payouts.
A past cut worth noting
Third-party analysis flags that the dividend has been reduced at least once in the last 10 years (the payout was far smaller a decade ago, near ₹0.67, implying a long-run rising trend but with a wobble). The long-term direction is upward, yet the recent four-year plateau means investors should not assume automatic annual hikes.
Historical dividend data compiled from TipRanks, Trendlyne and SimplyWall.st (Jul 2025–Jul 2026). Fiscal-year attribution of interim dividends can differ across aggregators; treat older years as indicative.
Financial Performance Analysis
Q1 FY27 (quarter ended 30-Jun-2026) — Consolidated vs Standalone
| Metric (₹ Cr) | Consolidated | Standalone |
|---|---|---|
| Total Income | 94.30 | 68.47 |
| EBITDA | 22.38 | 17.01 |
| PBT | 18.51 | 14.85 |
| PAT | 14.11 | 11.23 |
| EPS (₹) | 2.52 | 2.00 |
Powerful positive operating leverage
On a consolidated basis, Q1 FY27 vs Q1 FY26:
- Total Income: +37.05%
- EBITDA: +56.80%
- PBT: +67.36%
- PAT: +67.35%
Profits grew almost twice as fast as revenue — margins expanded sharply. This is the good kind of operating leverage.
Why margins jumped
Consolidated operating margin rose to about 25% in the March 2026 quarter from the mid-teens a year earlier. The gain came from better product mix and operating scale across the Bi-metal, Alkop die-casting and Braking segments, with cost lines rising slower than sales. Full-year FY26 revenue grew ~21% to ₹294 Cr and net profit jumped ~54% to ₹38.3 Cr.
Cash Flow Analysis
Reported profit is an opinion; cash is a fact. This is where Menon's otherwise-strong story shows a wrinkle. Despite booming reported profits, the company's ability to convert profit into cash has been steadily weakening.
⚠ Cash conversion is deteriorating
Operating cash flow as a % of operating profit (consolidated):
- FY23: 95%
- FY24: 65%
- FY25: 60%
- FY26: 40%
More profit is getting stuck in working capital. Debtor days rose to 113 (from 91) and the cash conversion cycle stretched to 146 days.
⚠ FCF did not cover this dividend
FY26 free cash flow was only about ₹5 Cr, versus this interim dividend outflow of ₹11.21 Cr. That is an FCF coverage of just 0.45× — last year's free cash flow would not have been enough to fund the payout on its own. Operating cash flow (₹23 Cr) does cover it (2.05×), but the shortfall in free cash flow means part of the dividend leans on cash reserves rather than surplus cash generation.
How is the dividend funded?
Primarily from current operating earnings and accumulated reserves (₹180 Cr), not from robust free cash flow. Heavy capital expenditure (investing outflow ~₹18 Cr in FY26) is eating most of the operating cash, leaving thin free cash. There is no evidence the dividend is funded by one-off asset sales.
Cash-flow figures from Screener consolidated statements (FY23–FY26). Individual cash & bank balance is not separately isolable from the summary and is marked "Not Independently Verified".
Balance Sheet Strength
Read-through
Returns are genuinely high — ROCE 25.5% and ROE 22.2% are strong for an auto-component maker. But the balance sheet is not cash-rich: borrowings have climbed steadily from ₹15 Cr (FY23) to ₹47 Cr (FY26) while investments sit at just ₹6 Cr, leaving the company in a modest net-debt position (~₹41 Cr before bank cash). The company is paying dividends and raising debt at the same time — sustainable while returns stay high, but worth watching.
Dividend Sustainability Analysis
Overall Classification
MODERATELY SUSTAINABLE
Comfortably earnings-covered, but free-cash-flow coverage is thin.
✔ What supports the dividend
- Earnings coverage strong: FY26 EPS ₹6.83 vs ₹2 = 3.4× cover
- Modest payout on full-year basis: ~29% of FY26 consolidated PAT
- High returns (ROCE 25.5%, ROE 22.2%)
- Large reserve buffer of ₹180 Cr
- Long, unbroken payment record
✘ What pressures the dividend
- FCF coverage only 0.45× — free cash didn't fund it
- Cash conversion (CFO/OP) fell to 40%
- Borrowings rising (₹15 Cr → ₹47 Cr in 3 years)
- Working-capital days up to 89
- Dividend flat at ₹2 for 4 years despite profit surge
Verdict in plain English
The ₹2 dividend is easily affordable out of profit and unlikely to be cut while earnings keep growing. The caution is not about affordability today but about quality of funding: the company is generating strong profits but weak free cash, and topping up with debt. If working capital normalises and capex eases, coverage improves; if cash conversion keeps sliding, future dividend growth (not the base payout) is what gets squeezed.
Peer Comparison
| Company | Div Yield | Payout | ROE | ROCE | Balance Sheet |
|---|---|---|---|---|---|
| Menon Bearings | ~0.98% | ~29–42% | 22.2% | 25.5% | Modest net debt |
| NRB Bearings | ~1.5% | ~52% | NIV | ~16% | Deleveraging |
| Sundram Fasteners | ~0.77% | ~30% | NIV | >17% | Low debt |
| SKF / Schaeffler / Timken (MNC bearing peers) | NIV (low) | NIV | NIV | NIV | Cash-rich, premium P/E |
Where Menon sits
Menon offers a lower yield but higher return ratios than NRB Bearings, and a more conservative payout. Its ROCE (25.5%) and ROE (22.2%) are best-in-class within this small-cap peer set, which is exactly why the market awards it a premium and the yield stays low. Cells marked NIV = Not Independently Verified are left blank rather than filled with unverified data.
Peer figures compiled from Screener, TipRanks and third-party aggregators (2026). Blank/NIV cells require live verification before any hard peer claim is published.
Promoter Impact Analysis
What this means
With 68.44% promoter ownership, roughly ₹7.67 Cr of the ₹11.21 Cr dividend flows to the promoter family. That is a meaningful alignment signal — promoters gain most when the company pays out. Note promoter holding has drifted down from ~71% to 68.44% over recent years, while institutional interest remains negligible (FII+DII under 0.3%), meaning this is largely a promoter-and-retail owned stock. The flat ₹2 dividend despite surging profits suggests the family favours reinvestment over larger self-payouts.
Taxation Analysis
How dividends are taxed in India (post-2020 rules)
Since the abolition of the Dividend Distribution Tax, dividends are taxed in the hands of the shareholder at their applicable income-tax slab rate. The company deducts TDS at 10% under Section 194 if total dividend paid to a resident shareholder in a financial year exceeds ₹10,000 (threshold raised from ₹5,000 w.e.f. FY2025-26). TDS is 20% if PAN is not provided. TDS is only an advance credit — final tax is at your slab.
Worked example — small holder (1,000 shares)
- Gross dividend: 1,000 × ₹2 = ₹2,000
- TDS: Nil (below ₹10,000 threshold)
- Tax at 30% slab + 4% cess: ₹624
- Net in hand: ₹1,376
Worked example — larger holder (6,000 shares)
- Gross dividend: 6,000 × ₹2 = ₹12,000
- TDS at 10% (exceeds ₹10,000): ₹1,200 at source
- Final tax at 30% slab + cess: ₹3,744
- Net in hand: ₹8,256 · effective post-tax yield ~0.67%
Illustrative only; actual liability depends on your total income, slab, surcharge and cess. TDS thresholds/rates can change in future budgets — verify current rules or consult a tax adviser. Not tax advice.
Key Risks
1. Weakening cash conversion
CFO/operating-profit fell from 95% to 40% in three years; more profit is trapped in receivables and inventory.
2. Rising leverage
Borrowings tripled from ₹15 Cr to ₹47 Cr (FY23→FY26). Dividends are being paid while debt climbs.
3. Auto-cycle dependence
A single-segment auto-components business tied to CV/diesel-engine demand; a downturn hits volumes and margins together.
4. Rich valuation
P/E in the mid-20s to ~30 leaves little room for earnings disappointment; the low yield offers no downside cushion.
5. Input-cost & FX exposure
Aluminium/steel prices and a meaningful export book expose margins to commodity swings and rupee movements.
6. Stagnant dividend growth
₹2 flat for four years means the payout is not keeping pace with profits — an income investor sees no growth.
What To Monitor
1. Cash conversion (CFO/OP)
Watch whether it recovers above 60%. A rebound signals working-capital discipline returning.
2. Debtor & working-capital days
Debtor days at 113 and WC days at 89 — falling numbers would confirm collections improving.
3. Borrowing trajectory
Track whether debt stabilises or keeps rising alongside capex plans.
4. Segment ramp-up (Brakes/Alkop)
New capacity utilisation is the swing factor for the next leg of revenue and margins.
5. Full-year FY27 payout
Whether the board tops up with a final dividend, and if ₹2 finally rises after four flat years.
6. Export demand & FX
Overseas order flow and rupee levels, given the sizeable export mix.
Conclusion
The positives
Menon Bearings delivered a standout Q1 FY27 — consolidated PAT up 67% on revenue up 37%, with best-in-class returns (ROCE 25.5%, ROE 22.2%). The ₹2 interim dividend is well covered by earnings (3.4× on FY26 EPS), and the company has an unbroken multi-year payment record.
The negatives
The dividend was not covered by free cash flow (0.45×), cash conversion has slid to 40%, borrowings have tripled to ₹47 Cr, and the payout has been frozen at ₹2 for four years. The ~1% yield offers income investors little, and the valuation is full.
Net picture
This is a growth stock that happens to pay a small, dependable dividend — not an income play. The dividend is Moderately Sustainable: safe out of profit, but funded with the help of reserves and debt rather than surplus free cash. We present the facts; the decision is yours.
Frequently Asked Questions
What dividend has Menon Bearings announced?
What is the dividend yield?
What is the record date?
What is the ex-date?
When will the dividend be paid?
Who is eligible to receive it?
How is this dividend taxed?
Is the dividend sustainable?
What is Menon Bearings' dividend history?
Does an interim dividend need AGM approval?
How much of the dividend goes to promoters?
What should investors monitor going forward?
Why is the yield so low if the company is doing well?
Disclaimer
This article is for informational and educational purposes only and does not constitute investment, financial or tax advice, nor a recommendation to buy, sell or hold any security. Event facts (dividend, record date, payment window, financial results) are drawn from Menon Bearings Limited's exchange filing dated 16 July 2026. Market price, yield, peer data and historical dividends are sourced from third-party platforms (Screener, Tickertape, TipRanks, Trendlyne) as of research date and may be delayed or revised; several figures are marked "inferred" or "Not Independently Verified". Current market price must be re-verified against live NSE/BSE data before acting. Please conduct your own research and consult a SEBI-registered adviser. ShareBazaar Online and its authors accept no liability for decisions taken on the basis of this content.