
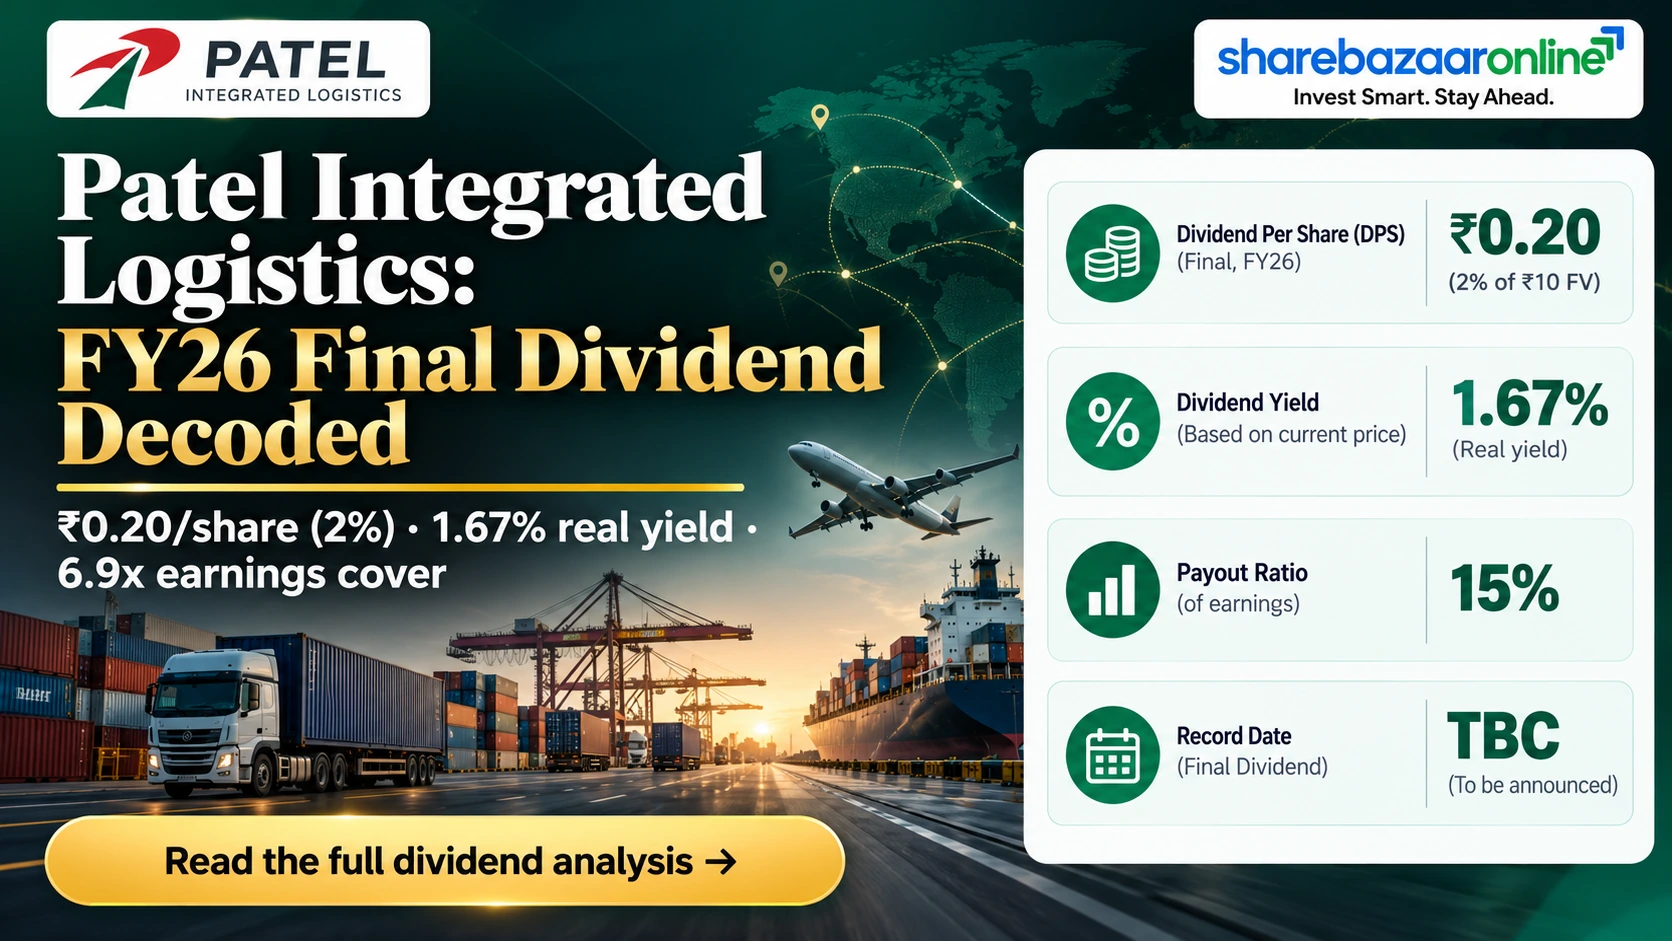
Dividend Snapshot – Patel Integrated Logistics Limited
Patel Integrated Logistics Limited (NSE: PATINTLOG, BSE: 526381) declared a Final Dividend of ₹0.20 per equity share for FY2025-26 — a payout equal to 2% on the ₹10 face value. The notable part is that this was a cut: the board had first recommended ₹0.40 (4%) on 12 May 2026, then halved it to ₹0.20 (2%) on 24 August 2026, citing cash used in its recent share buyback. At the current market price of ₹12.0, the real dividend yield works out to about 1.67%. Shareholders on the record date of 17 September 2026 were entitled, and members approved the dividend at the 64th AGM on 24 September 2026.
Dividend Per Share
₹0.20
Final · 2% of ₹10 face value · FY2025-26
Dividend Yield (on CMP ₹12.0)
1.67%
Yield on 12 May announcement price (₹11.49): 1.74%
Record Date
17 Sep 2026
Ex-Date: 17 Sep 2026 · Book closure 18–24 Sep 2026
AGM Approval
24 Sep 2026
64th AGM · Dividend approved by members
Company Overview – Patel Integrated Logistics Limited
Patel Integrated Logistics Limited is a Mumbai-headquartered logistics company and part of the “House of Patels,” originally founded as Patel Roadways in 1959 and incorporated in 1962. It provides integrated logistics solutions spanning air-cargo consolidation, surface transport, warehousing and express delivery, and was among the first Indian firms registered as a Multimodal Transport Operator. It is a micro-cap, with a market capitalisation of roughly ₹83 crore and trailing revenue of about ₹393 crore. The business is high-turnover, low-margin: operating margins run near 2.9%. The company is almost debt-free, with borrowings of only about ₹6 crore. For dividend analysis of Patel Integrated Logistics Limited, consolidated figures are used throughout, with standalone referenced only where required.
Patel Integrated Logistics Limited Financial Analysis at a Glance
On headline numbers, Patel Integrated Logistics Limited looks optically cheap: the stock trades at a P/E of about 7.98 and a price-to-book of roughly 0.64, below its book value of ₹17.8 per share. FY2025-26 consolidated revenue was around ₹357 crore with net profit near ₹9.6 crore and EPS of ₹1.38. Return ratios are modest — ROE of 7.82% and ROCE of 8.05% — which is typical for an asset-light freight-forwarding model with thin margins. The share has been weak, trading in a 52-week band of ₹8.01–₹16.6, and the low P/B reflects the market’s muted view of sustained earnings quality rather than deep value.
Patel Integrated Logistics Limited Dividend History Table
Final dividend per share, face value ₹10 (external data: exchange filings and market aggregators).
| Financial Year | Type | Dividend / Share | Dividend % |
|---|---|---|---|
| FY2025-26 | Final | ₹0.20 | 2% |
| FY2024-25 | Final | ₹0.30 | 3% |
| FY2023-24 | Final | ₹0.10 | 1% |
| FY2022-23 | Final | ₹0.10 | 1% |
| FY2021-22 | Final | ₹0.10 | 1% |
The FY2025-26 ₹0.20 is down 33% from last year’s ₹0.30 and 50% below the ₹0.40 the board first recommended.
Expert Commentary on the Patel Integrated Logistics Limited Dividend
The real story behind the Patel Integrated Logistics Limited dividend is capital allocation, not the headline number. In July 2026 the company completed a ₹10.80 crore buyback (54 lakh shares tendered at ₹20, roughly a 33% premium to the then-market price). Weeks later it halved the final dividend, explicitly pointing to the buyback funds. So of the roughly ₹12.1 crore returned to shareholders this cycle, the cash dividend is only about 11% — the buyback is 8.4x larger. That matters because a buyback rewards only those who tendered and exited at a premium, while continuing shareholders received a smaller recurring payout. The cut was a choice about where cash went, not a sign the dividend was unaffordable.
Patel Integrated Logistics Limited Dividend Outlook
Looking ahead, the Patel Integrated Logistics Limited dividend trajectory hinges on earnings consistency and capital-allocation priorities rather than on balance-sheet capacity, which is comfortable. Q1 FY2026-27 was encouraging — revenue of about ₹113.86 crore and net profit of ₹2.52 crore, up roughly 53% year-on-year. If this profit momentum holds and no further large buyback is undertaken, the company retains the cash headroom to restore or grow the payout. However, the FY2026 cut, a long record of only token ₹0.10–₹0.30 dividends, and thin 2.9% operating margins mean dividend growth is not something investors should assume. The company has not disclosed any forward dividend guidance, so future payouts remain uncertain.
Patel Integrated Logistics Limited Dividend Announcement Summary
The Patel Integrated Logistics Limited dividend announcement came in two stages. On 12 May 2026, alongside FY2025-26 results, the board recommended a final dividend of ₹0.40 per share (4%), subject to member approval. On 24 August 2026, after considering funds used in the recent buyback and the resultant cash position, the board revised the recommendation down to ₹0.20 per share (2%) for the year ended 31 March 2026. The reduced dividend was placed before shareholders and approved at the 64th Annual General Meeting on 24 September 2026. The dividend is payable to members on the register as of the record date, in accordance with the Companies Act, 2013 and SEBI LODR Regulations.
Patel Integrated Logistics Limited Key Dates Timeline
Original Recommendation
12 May 2026
Board proposed ₹0.40 (4%)
Revised Recommendation
24 Aug 2026
Cut to ₹0.20 (2%)
Record Date / Ex-Date
17 Sep 2026
Book closure 18–24 Sep 2026
AGM / Payment
24 Sep 2026
Approved at AGM; exact payment date Not Disclosed by Company (statutorily within 30 days of AGM)
Patel Integrated Logistics Limited Dividend Yield Analysis
A common confusion with the Patel Integrated Logistics Limited dividend is the “2%” label. That 2% is calculated on the ₹10 face value, giving ₹0.20 per share — it is not a 2% return on your investment. The real dividend yield is the dividend divided by the market price: at a CMP of ₹12.0, that is 1.67%. Because the stock trades close to its face value (about 1.2x), the headline percentage and the real yield are unusually close here — for higher-priced shares the gap can be enormous. On the original 12 May 2026 price of about ₹11.49, the yield would have been 1.74%. Either way, this is a modest cash yield, broadly in line with the thin payouts typical of the logistics sector.
Patel Integrated Logistics Limited Dividend History Analysis
The dividend track record of Patel Integrated Logistics Limited is best described as that of an irregular, low-payout payer rather than a dependable dividend compounder. After three years of a token ₹0.10 (FY2022–FY2024), the company stepped up to ₹0.30 in FY2025, then pulled back to ₹0.20 in FY2026 — and even that was halved from the ₹0.40 first proposed. There is no steady growth trend, no special dividends, and the payout ratio has swung from about 27% (FY25) to roughly 15% (FY26) even as earnings rose. For investors, the signal is clear: dividends from Patel Integrated Logistics Limited are small, discretionary and policy-driven, not a reliable annuity.
Patel Integrated Logistics Limited Financial Performance Analysis
On operating leverage, Patel Integrated Logistics Limited shows improving but fragile profitability. FY2025-26 consolidated revenue rose about 4% to ₹357 crore, while net profit improved to roughly ₹9.6 crore from ₹8 crore, lifting EPS to ₹1.38 from ₹1.09 — a profit growth of around 26% on modest sales growth, aided by lower interest costs as debt fell. The constraint is structural: operating margins are only about 2.9%, so small cost swings move the bottom line sharply. The trailing-twelve-month picture is stronger, with profit growth near 38% and Q1 FY2026-27 net profit up about 53% year-on-year. Earnings are recovering, but the thin-margin freight model keeps profitability vulnerable to fuel, employee and cargo-rate pressures.
Patel Integrated Logistics Limited Cash Flow Analysis
Reported profit is an opinion; cash is a fact — so the question is whether the Patel Integrated Logistics Limited dividend is funded by real cash. In FY2025-26 the company generated operating cash flow of about ₹8 crore and free cash flow of around ₹7 crore, comfortably covering the roughly ₹1.3 crore dividend outflow (about 5–6x cover). So the recurring dividend itself is clearly cash-funded from current earnings. The strain came from the buyback: the ₹10.80 crore buyback exceeded a full year’s free cash flow, so it drew down the cash pile rather than being met from annual cash generation. Cash conversion is a watch item — FY26 CFO was only about 36% of operating profit — but the dividend is not the cash pressure point here.
Patel Integrated Logistics Limited Balance Sheet Strength
The balance sheet of Patel Integrated Logistics Limited is a genuine strength and the reason the dividend was always affordable. As of March 2026 the company held cash and investments of about ₹32 crore against borrowings of just ₹6 crore, leaving a net cash position near ₹26 crore and a debt-to-equity ratio of roughly 0.05 — effectively debt-free. Net worth stood at about ₹124 crore (equity capital ₹70 crore plus reserves ₹54 crore), supporting a book value of ₹17.8 per share. Measured against the ₹1.3 crore dividend, cash cover is roughly 25x. The ₹10.80 crore buyback consumed about a third of the pre-buyback cash pile, which is why management flagged it when trimming the dividend.
Patel Integrated Logistics Limited Dividend Sustainability Analysis
Applying a four-test sustainability check to the Patel Integrated Logistics Limited dividend:
- Earnings cover: EPS ₹1.38 against ₹0.20 dividend = 6.9x — very comfortable.
- Operating cash cover: OCF ₹8 cr vs ₹1.3 cr outflow = 6.2x — strong.
- Free cash cover: FCF ₹7 cr = 5.4x — strong.
- Liquidity cover: cash ₹32 cr = roughly 25x — very strong.
On capacity, the dividend is easily sustainable. The weakness is willingness and consistency: the payout was cut despite ample cover, and history is erratic. Verdict: Moderately Sustainable — the company can clearly afford it; whether it chooses to maintain or grow it is the real uncertainty.
Patel Integrated Logistics Limited Peer Comparison
Indicative logistics-sector comparison (external market data; metrics vary by source and date).
| Company | Approx. Div Yield | P/E | Market Cap |
|---|---|---|---|
| Patel Integrated Logistics | ~1.67% | ~8.0 | ~₹83 cr |
| VRL Logistics | ~1.7% | ~19 | ~₹5,000 cr |
| TCI Express | ~1.2–2.5% | ~33 | ~₹2,200 cr |
| Gateway Distriparks | ~1% | ~10 | ~₹2,550 cr |
Patel Integrated Logistics Limited screens with a yield in line with larger logistics peers and the lowest P/E and ROE (7.82%) of the group. Its yield is flattered partly by a depressed share price rather than by a generous or growing payout — a classic yield reality check.
Patel Integrated Logistics Limited Promoter Impact Analysis
Promoter holding in Patel Integrated Logistics Limited is low at about 35% (September 2026), with FII and DII holding near zero and the public holding roughly 65%. On the ₹0.20 dividend, the estimated total outflow of about ₹1.3 crore splits into roughly ₹0.45 crore to promoters and ₹0.84 crore to public shareholders. Because promoters own a minority stake, the cash dividend flows mostly to public investors — but the far larger capital return, the ₹10.80 crore buyback, benefited only those who tendered. Promoter holding has also drifted down, and promoter Asgar Shakoor Patel disclosed the sale of 2,63,832 shares on 1 October 2026 under SEBI SAST rules — a governance point worth tracking, though legally disclosed and routine in form.
Patel Integrated Logistics Limited Dividend Taxation Analysis
Since FY2020-21, dividends are taxed in the shareholder’s hands at their income-tax slab rate (no DDT). Under Section 194, the company deducts 10% TDS only if total dividend from it exceeds ₹10,000 in a financial year (threshold raised from ₹5,000 effective 1 April 2025); no PAN means 20%.
General worked example (template)
1,000 shares × ₹10 dividend = ₹10,000 gross. At the ₹10,000 threshold, no TDS. At a 30% slab (+4% cess): tax ₹3,120, net ₹6,880.
PATINTLOG-specific example
1,000 shares × ₹0.20 = ₹200 gross. Well below the TDS limit, so no TDS. At a 30% slab (+cess): tax ₹62.40, net ₹137.60 — a net yield of about 1.15% on a ₹12,000 holding.
Key Risks for Patel Integrated Logistics Limited Dividend Investors
- Erratic dividend policy: the payout was halved from ₹0.40 to ₹0.20 and cut 33% year-on-year — there is no reliable, growing dividend to depend on.
- Wafer-thin margins: operating margins of about 2.9% mean fuel, wage or freight-rate shocks can quickly erode profit and future payout capacity.
- Weak cash conversion: FY26 operating cash flow was only about 36% of operating profit, and debtor days near 74 tie up working capital.
- Capital-allocation risk: management has prioritised buybacks over dividends, so recurring payouts may stay small or volatile.
- Micro-cap & liquidity risk: a ~₹83 crore market cap, low 35% promoter holding and declining promoter stake add governance and price-volatility risk.
What to Monitor in Patel Integrated Logistics Limited
- Operating margin trend: whether OPM can sustainably move above the current ~2.9%, which drives all future payout capacity.
- Cash conversion: operating cash flow as a share of operating profit and movement in debtor days each quarter.
- Dividend policy signals: whether the next final dividend is restored toward ₹0.30–₹0.40 or stays at the reduced level.
- Capital-allocation choices: any further buybacks, capex or acquisitions that compete with the dividend for cash.
- Promoter holding: further changes in the ~35% promoter stake and any additional insider sales disclosed under SAST.
Conclusion – Patel Integrated Logistics Limited Dividend
The Patel Integrated Logistics Limited FY2025-26 final dividend of ₹0.20 per share (2%) is a small, cash-covered payout attached to a bigger capital-allocation story. The balance sheet is strong — near debt-free, with roughly 25x cash cover and 6.9x earnings cover — so affordability was never the issue. The dividend was halved because the company chose to route cash into a ₹10.80 crore buyback, which dwarfed the ₹1.3 crore dividend. For income seekers, the real yield of about 1.67% is modest and the payout history is irregular. The positives are a clean balance sheet and recovering profits; the negatives are thin margins, weak cash conversion and an inconsistent dividend. Investors should weigh these facts and risks and reach their own view.
Frequently Asked Questions About Patel Integrated Logistics Limited Dividend
What dividend has Patel Integrated Logistics Limited announced?
What is the Patel Integrated Logistics dividend yield?
What was the record date for the PATINTLOG dividend?
What is the ex-dividend date for Patel Integrated Logistics?
When will the Patel Integrated Logistics dividend be paid?
Who was eligible for the Patel Integrated Logistics dividend?
How is the Patel Integrated Logistics dividend taxed?
Is the Patel Integrated Logistics dividend sustainable?
Why did Patel Integrated Logistics cut its dividend?
What is the Patel Integrated Logistics dividend history?
What should investors monitor in Patel Integrated Logistics?
What are the NSE symbol, BSE code and ISIN of Patel Integrated Logistics?
Disclaimer
This article on the Patel Integrated Logistics Limited dividend is for informational and educational purposes only and does not constitute investment, legal or tax advice, or any recommendation to buy, sell or hold securities. ShareBazaar Online is not a SEBI-registered investment adviser. Dividend details are based on company filings with the stock exchanges and publicly available market data; figures from external sources (market price, financial ratios, shareholding, peer data and dividend history) are indicative and may differ by source and date. Tax treatment depends on individual circumstances and prevailing law. Investors should verify all figures with official company disclosures and consult a qualified financial or tax professional before making any investment decision. Investments in securities are subject to market risks.