
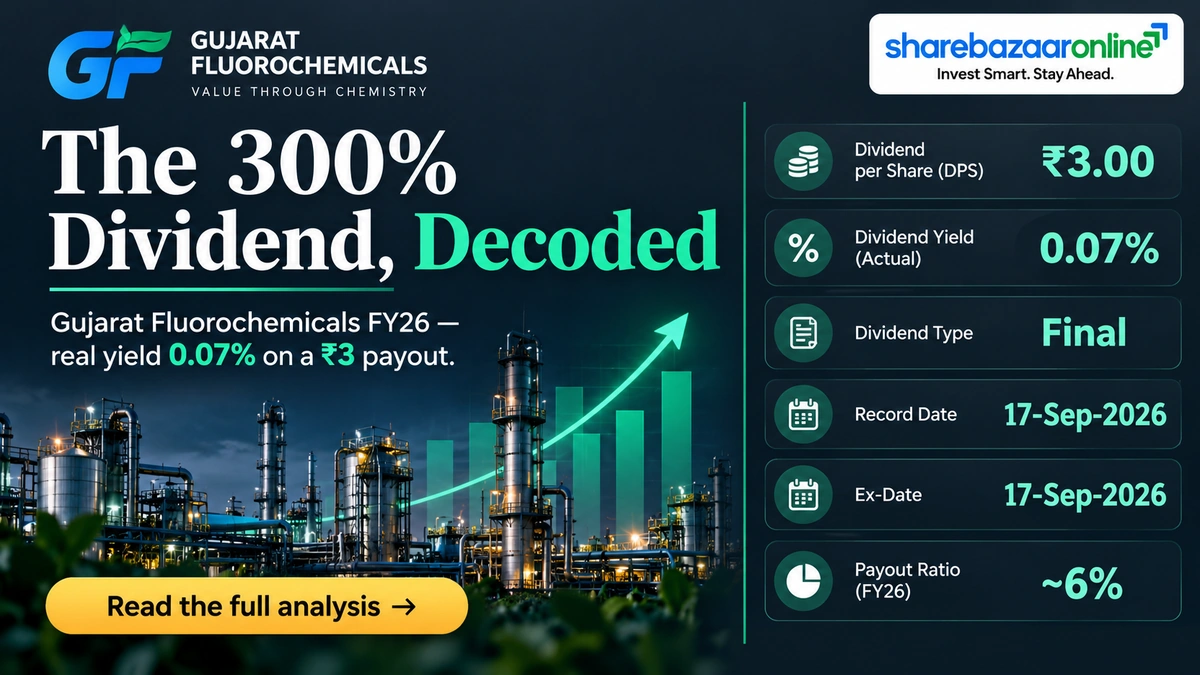
Dividend Snapshot – Gujarat Fluorochemicals Limited
Gujarat Fluorochemicals Limited (NSE: FLUOROCHEM) has declared a final dividend of ₹3.00 per share for FY2025–26, a headline 300% on its ₹1 face value. On the current market price of ₹4,454, that converts to a real dividend yield of just 0.07% — the classic gap between a big percentage and a small cash return.
Company Overview – Gujarat Fluorochemicals Limited
Gujarat Fluorochemicals Limited is a specialty-chemicals manufacturer and part of the INOX GFL Group. It was demerged from GFL Limited and listed as a separate entity in 2019. The company is one of India’s leading producers of fluoropolymers, fluoro-specialities, refrigerants and bulk chemicals, and ranks among the top five global fluoropolymer players, exporting to Europe, the Americas, Japan and Asia.
It is also building out high-growth verticals in battery materials and new-energy chemistry. In FY2025–26, Gujarat Fluorochemicals reported consolidated revenue of ₹4,996 Cr and net profit of ₹574 Cr. The business is capital-intensive and currently in a heavy expansion phase, which is the single most important lens for reading its small dividend. (Financials: company filings via Screener.in.)
Gujarat Fluorochemicals Financial Analysis at a Glance
Earnings are recovering off a cyclical trough, but returns are modest (ROE under 8%) and free cash flow is negative — a direct result of aggressive capex. These two facts frame the dividend story more than the 300% headline does. (Figures: Screener.in consolidated.)
Gujarat Fluorochemicals Dividend History Table
| Financial Year | Dividend / Share | Type | Payout Ratio | Record Date |
|---|---|---|---|---|
| FY2025–26 | ₹3.00 | Final | ~6% | 17 Sep 2026 |
| FY2024–25 | ₹3.00 | Final | ~6% | 22 Sep 2025 |
| FY2023–24 | ₹3.00 | Final | ~8% | 20 Sep 2024 |
| FY2022–23 | ₹3.00 | Final | ~3% | Sep 2023 |
| FY2021–22 | Initiated | Final | ~6% | Sep 2022 |
| FY2019–21 | Nil | – | 0% | – |
Dividend per share for FY24–FY26 confirmed via exchange corporate-action records; FY22–FY23 shown by payout ratio (Screener.in). Payment was suspended during the FY19–FY21 post-demerger period.
Expert Commentary on the Gujarat Fluorochemicals Dividend
The 300% figure is calculated on a ₹1 face value, not on the market price. In cash terms, each share returns ₹3 — a real yield of 0.07%. This is the face-value illusion that trips up many retail readers: a large percentage attached to a tiny base.
Gujarat Fluorochemicals has paid a flat ₹3.00 for three straight years even as profit recovered from the FY24 trough. That consistency signals a deliberate choice: management is retaining cash to fund expansion (fluoropolymers, refrigerants, battery materials) rather than scaling up distributions. The dividend is best read as a token return from a growth-and-capex company, not an income stream. Readers chasing yield will find far more elsewhere; readers backing the capex thesis should expect the payout to stay small.
Gujarat Fluorochemicals Dividend Outlook
Future dividend policy has not been formally guided by the company, so the following is editorial reading of disclosed facts, not a forecast. With capital work-in-progress at ₹1,900 Cr, negative free cash flow, and rising borrowings, the structural setup favours continued reinvestment over a larger payout.
A meaningfully higher dividend would most likely require the capex cycle to peak and free cash flow to turn positive. If earnings keep recovering — FY26 PAT rose 5.1% and the TTM figure is already ₹600 Cr — the payout could be nudged up, but the base is so low that even a doubling would leave the yield under 0.2%. For now, the sensible expectation is a steady, modest ₹3-range dividend, with the investment case resting on growth, not income.
Gujarat Fluorochemicals Dividend Announcement Summary
The Board of Gujarat Fluorochemicals recommended a final dividend of ₹3.00 per equity share (300%) for the financial year ended 31 March 2026, alongside its annual results in late May 2026. The company subsequently fixed 17 September 2026 as the record date under Regulation 42 of SEBI (LODR) Regulations, 2015.
The dividend was approved by shareholders at the Eighth Annual General Meeting on 24 September 2026. Per the company’s intimation, the payout is subject to deduction of tax at source as applicable, and is to be paid within the statutory timeline following declaration. The exact payment/credit date was Not Disclosed by Company in the record-date filing. (Source: BSE/NSE filings, 27 Aug 2026.)
Gujarat Fluorochemicals Dividend Key Dates Timeline
Under India’s T+1 settlement, the ex-dividend date and record date fall on the same day (17 September 2026), as confirmed by exchange data. Shareholders on the register as of the record date were eligible. The statutory window requires dividend payment within 30 days of declaration at the AGM.
Gujarat Fluorochemicals Dividend Yield Analysis
Dividend yield = dividend per share ÷ share price. At the current price of ₹4,454, the ₹3 dividend yields 0.07%. Around the May 2026 announcement, when the stock traded near ₹3,650, the yield was roughly 0.08% — essentially the same tiny figure.
The 300% “percentage” readers see is the dividend expressed on the ₹1 face value (₹3 ÷ ₹1 = 300%). It is not an investment return. On what an investor actually pays — the market price — the return is under one-tenth of one percent. For context, a standard savings account or liquid fund returns many multiples of this. Gujarat Fluorochemicals is therefore not a dividend-yield stock; its appeal, if any, is capital appreciation driven by its chemicals and new-energy expansion.
Gujarat Fluorochemicals Dividend History Analysis
Gujarat Fluorochemicals has distributed a flat ₹3.00 per share each year across FY2023–24, FY2024–25 and FY2025–26. Before that, it paid no dividend from FY2019 to FY2021 as the newly demerged entity conserved cash, and initiated distributions around FY2022.
On the four-test classification, this makes Gujarat Fluorochemicals a consistent but static payer: the rupee amount has not moved in three years, even though FY23 profit spiked to ₹1,323 Cr and then normalised. There have been no special dividends and no cuts during the paying period. The flat payout, against a swinging profit line, confirms the dividend is set as a fixed token rather than a share of earnings — payout ratio has ranged only from ~3% to ~8%.
Gujarat Fluorochemicals Financial Performance Analysis
In FY2025–26, revenue rose 5.5% to ₹4,996 Cr, operating profit grew 9.2% to ₹1,201 Cr, and net profit rose 5.1% to ₹574 Cr. Operating profit outpacing revenue points to modest positive operating leverage as margins recover.
The longer picture is cyclical. Profit peaked at ₹1,323 Cr in FY23 on a refrigerant and specialty up-cycle, then collapsed 67% to ₹435 Cr in FY24 as prices normalised, before climbing back to ₹574 Cr. ROE remains subdued at 7.82% and ROCE at 9.64% — below where a company trading at a 79x P/E would ideally sit. The market is clearly pricing future battery-materials and fluoropolymer growth, not current returns. (Consolidated; Screener.in.)
Gujarat Fluorochemicals Cash Flow Analysis
Reported profit is an accounting figure; cash is the test. In FY26, Gujarat Fluorochemicals generated healthy operating cash flow of ₹961 Cr — comfortably above net profit of ₹574 Cr, so cash conversion is sound. The problem sits below that line.
After capex of roughly ₹1,168 Cr (investing outflow), free cash flow was negative ₹292 Cr — the third straight year of negative FCF (FY24: –₹330 Cr; FY25: –₹335 Cr). This means the company is spending more on growth than its operations throw off, and the shortfall is being bridged by borrowing. The dividend itself is tiny (₹33 Cr) and is easily covered by operating cash, but on a strict free-cash basis, every rupee of dividend is effectively funded from the balance sheet, not surplus cash.
Gujarat Fluorochemicals Balance Sheet Strength
The balance sheet carries a net-debt position of about ₹2,444 Cr, and borrowings rose ₹641 Cr in FY26 to fund expansion. Large reserves of ₹7,855 Cr provide a cushion, but these are not all liquid cash. Debt rising while dividends are paid is a flag worth noting, though the dividend (₹33 Cr) is immaterial — just 1.2% of borrowings. (Screener.in consolidated.)
Gujarat Fluorochemicals Dividend Sustainability Analysis
On earnings and operating cash, the dividend is overwhelmingly covered — EPS covers it 17.5 times and operating cash 29 times. The only failing test is free cash flow, which is negative because of heavy capex. Given the trivial size of the payout versus the company’s cash generation and reserves, the verdict is Sustainable but structurally minimal: the ₹3 dividend is in no danger, but there is no basis to expect it to grow materially while the capex cycle runs.
Gujarat Fluorochemicals Peer Comparison
| Company | Dividend Yield | ROE |
|---|---|---|
| Gujarat Fluorochemicals | 0.07% | 7.34% |
| SRF Ltd | 0.38% | 13.06% |
| Pidilite Industries | 0.99% | 22.60% |
| Deepak Nitrite | 0.44% | – |
| Atul Ltd | 0.44% | 10.89% |
| Aarti Industries | 0.20% | 7.03% |
Gujarat Fluorochemicals has the lowest dividend yield in its specialty-chemicals peer set — roughly one-fifth of SRF’s and a fraction of Pidilite’s. Its ROE is also at the low end. The takeaway: GFCL distributes less and earns lower returns than most listed peers, consistent with a company reinvesting heavily for a later payoff. (Peer data: Motilal Oswal screener, Aug 2026.)
Gujarat Fluorochemicals Promoter Impact Analysis
Of the ~₹33 Cr total outflow, the promoter group (INOX GFL) receives about ₹20.2 Cr on its 61.39% stake, while non-institutional public shareholders share roughly ₹6.8 Cr. Because the payout is small and paid equally per share, there is no structural tilt favouring promoters beyond their proportionate holding. The more important signal is directional: the controlling group, which benefits most from any dividend, has kept the payout deliberately low — reinforcing that retained capital is the priority.
Gujarat Fluorochemicals Dividend Taxation Analysis
Since the Finance Act 2020, dividends are taxable in the shareholder’s hands at their income-tax slab rate. Under Section 194, the company deducts TDS at 10% if total dividend from it exceeds ₹10,000 in a financial year (threshold raised from ₹5,000 w.e.f. FY2025–26); 20% applies if PAN is not provided. NRIs are taxed under Section 195 at 20% plus surcharge and cess, subject to any DTAA relief.
Worked example (at ₹3/share): an investor holding 5,000 shares receives a gross dividend of ₹15,000. As this exceeds ₹10,000, TDS of ₹1,500 is deducted (net received ₹13,500). For a 30%-slab investor, total tax is ₹4,500, leaving a post-tax ₹10,500 — an effective post-tax yield of about 0.05% on the current price. This is general information, not tax advice.
Key Risks for Gujarat Fluorochemicals Investors
- Negligible income return: at a 0.07% yield, the stock offers effectively no dividend income — unsuitable for income-focused investors.
- Negative free cash flow: three consecutive years of negative FCF (FY24–FY26) mean growth is funded by debt; a prolonged capex overrun could pressure the balance sheet.
- Rising leverage: borrowings rose ₹641 Cr in FY26 to ₹2,721 Cr, lifting interest and financial risk.
- Earnings cyclicality: profit swung from ₹1,323 Cr (FY23) to ₹435 Cr (FY24); refrigerant and fluoropolymer prices are volatile.
- Rich valuation: a 79x P/E on sub-8% ROE leaves little room for execution slips in the battery-materials ramp.
- Static payout: a flat ₹3 dividend provides no inflation protection or growing income.
What to Monitor in Gujarat Fluorochemicals
- Free cash flow turn: watch for FCF moving back to positive — the key trigger for any dividend increase.
- Capex peak and CWIP conversion: track how the ₹1,900 Cr CWIP converts into revenue-generating assets.
- Battery-materials and new-energy ramp: monitor commercialisation and margins of the new verticals driving the premium valuation.
- Debt trajectory: whether borrowings stabilise or keep climbing as expansion proceeds.
- Margin recovery: sustainability of the operating-margin rebound toward prior-cycle levels.
- Dividend policy signals: any shift from the flat ₹3 payout in future board commentary.
Should You Consider Gujarat Fluorochemicals for Dividend Income?
Gujarat Fluorochemicals’ FY26 final dividend of ₹3.00 (300%) looks striking on paper but delivers a real yield of only 0.07% — the lowest among its specialty-chemicals peers. The payout is comfortably sustainable on earnings (17.5x cover) and operating cash (29x cover), yet structurally minimal: it has stayed flat at ₹3 for three years and is dwarfed by the company’s capex, which pushes free cash flow negative.
The honest reading is that this is a growth and capital-appreciation story, not an income one. The strengths are strong cash conversion, a top-five global fluoropolymer position and a battery-materials option; the concerns are negative FCF, rising debt, cyclical earnings and a rich 79x valuation. Income seekers will look elsewhere; those backing the expansion should treat the dividend as a rounding error. The facts are laid out above for readers to weigh for themselves.
Frequently Asked Questions About Gujarat Fluorochemicals Dividend
What dividend has Gujarat Fluorochemicals announced for FY2025–26?
What is the Gujarat Fluorochemicals dividend yield?
What is the record date for the Gujarat Fluorochemicals dividend?
What is the ex-dividend date for Gujarat Fluorochemicals?
When will the Gujarat Fluorochemicals dividend be paid?
Who was eligible for the Gujarat Fluorochemicals dividend?
How is the Gujarat Fluorochemicals dividend taxed?
Is the Gujarat Fluorochemicals dividend sustainable?
What is the Gujarat Fluorochemicals dividend history?
How does Gujarat Fluorochemicals’ yield compare with peers?
What should investors monitor in Gujarat Fluorochemicals?
What is the total dividend outflow for Gujarat Fluorochemicals?
Disclaimer – Gujarat Fluorochemicals Dividend Analysis
This article is for informational and educational purposes only and does not constitute investment, legal or tax advice. ShareBazaar Online is not a SEBI-registered investment adviser. Disclosed facts (dividend amount, dates, face value) are drawn from Gujarat Fluorochemicals Limited’s exchange filings; financial and market figures are sourced from public data providers including Screener.in, exchange records and Motilal Oswal, and are cited within the article. Editorial analysis reflects interpretation of disclosed information, not forecasts of future corporate action or regulatory outcomes. Market prices and yields change continuously; figures are as of the stated dates. No buy, sell or hold recommendation is made. Investors should verify data independently and consult a qualified financial or tax professional before making any decision. Dividend taxation depends on individual circumstances.